Loading...
HOME2023-01-22T13:43:33-07:00

Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (PM) - 09/14/26 {{catlist}}
September 14, 2026
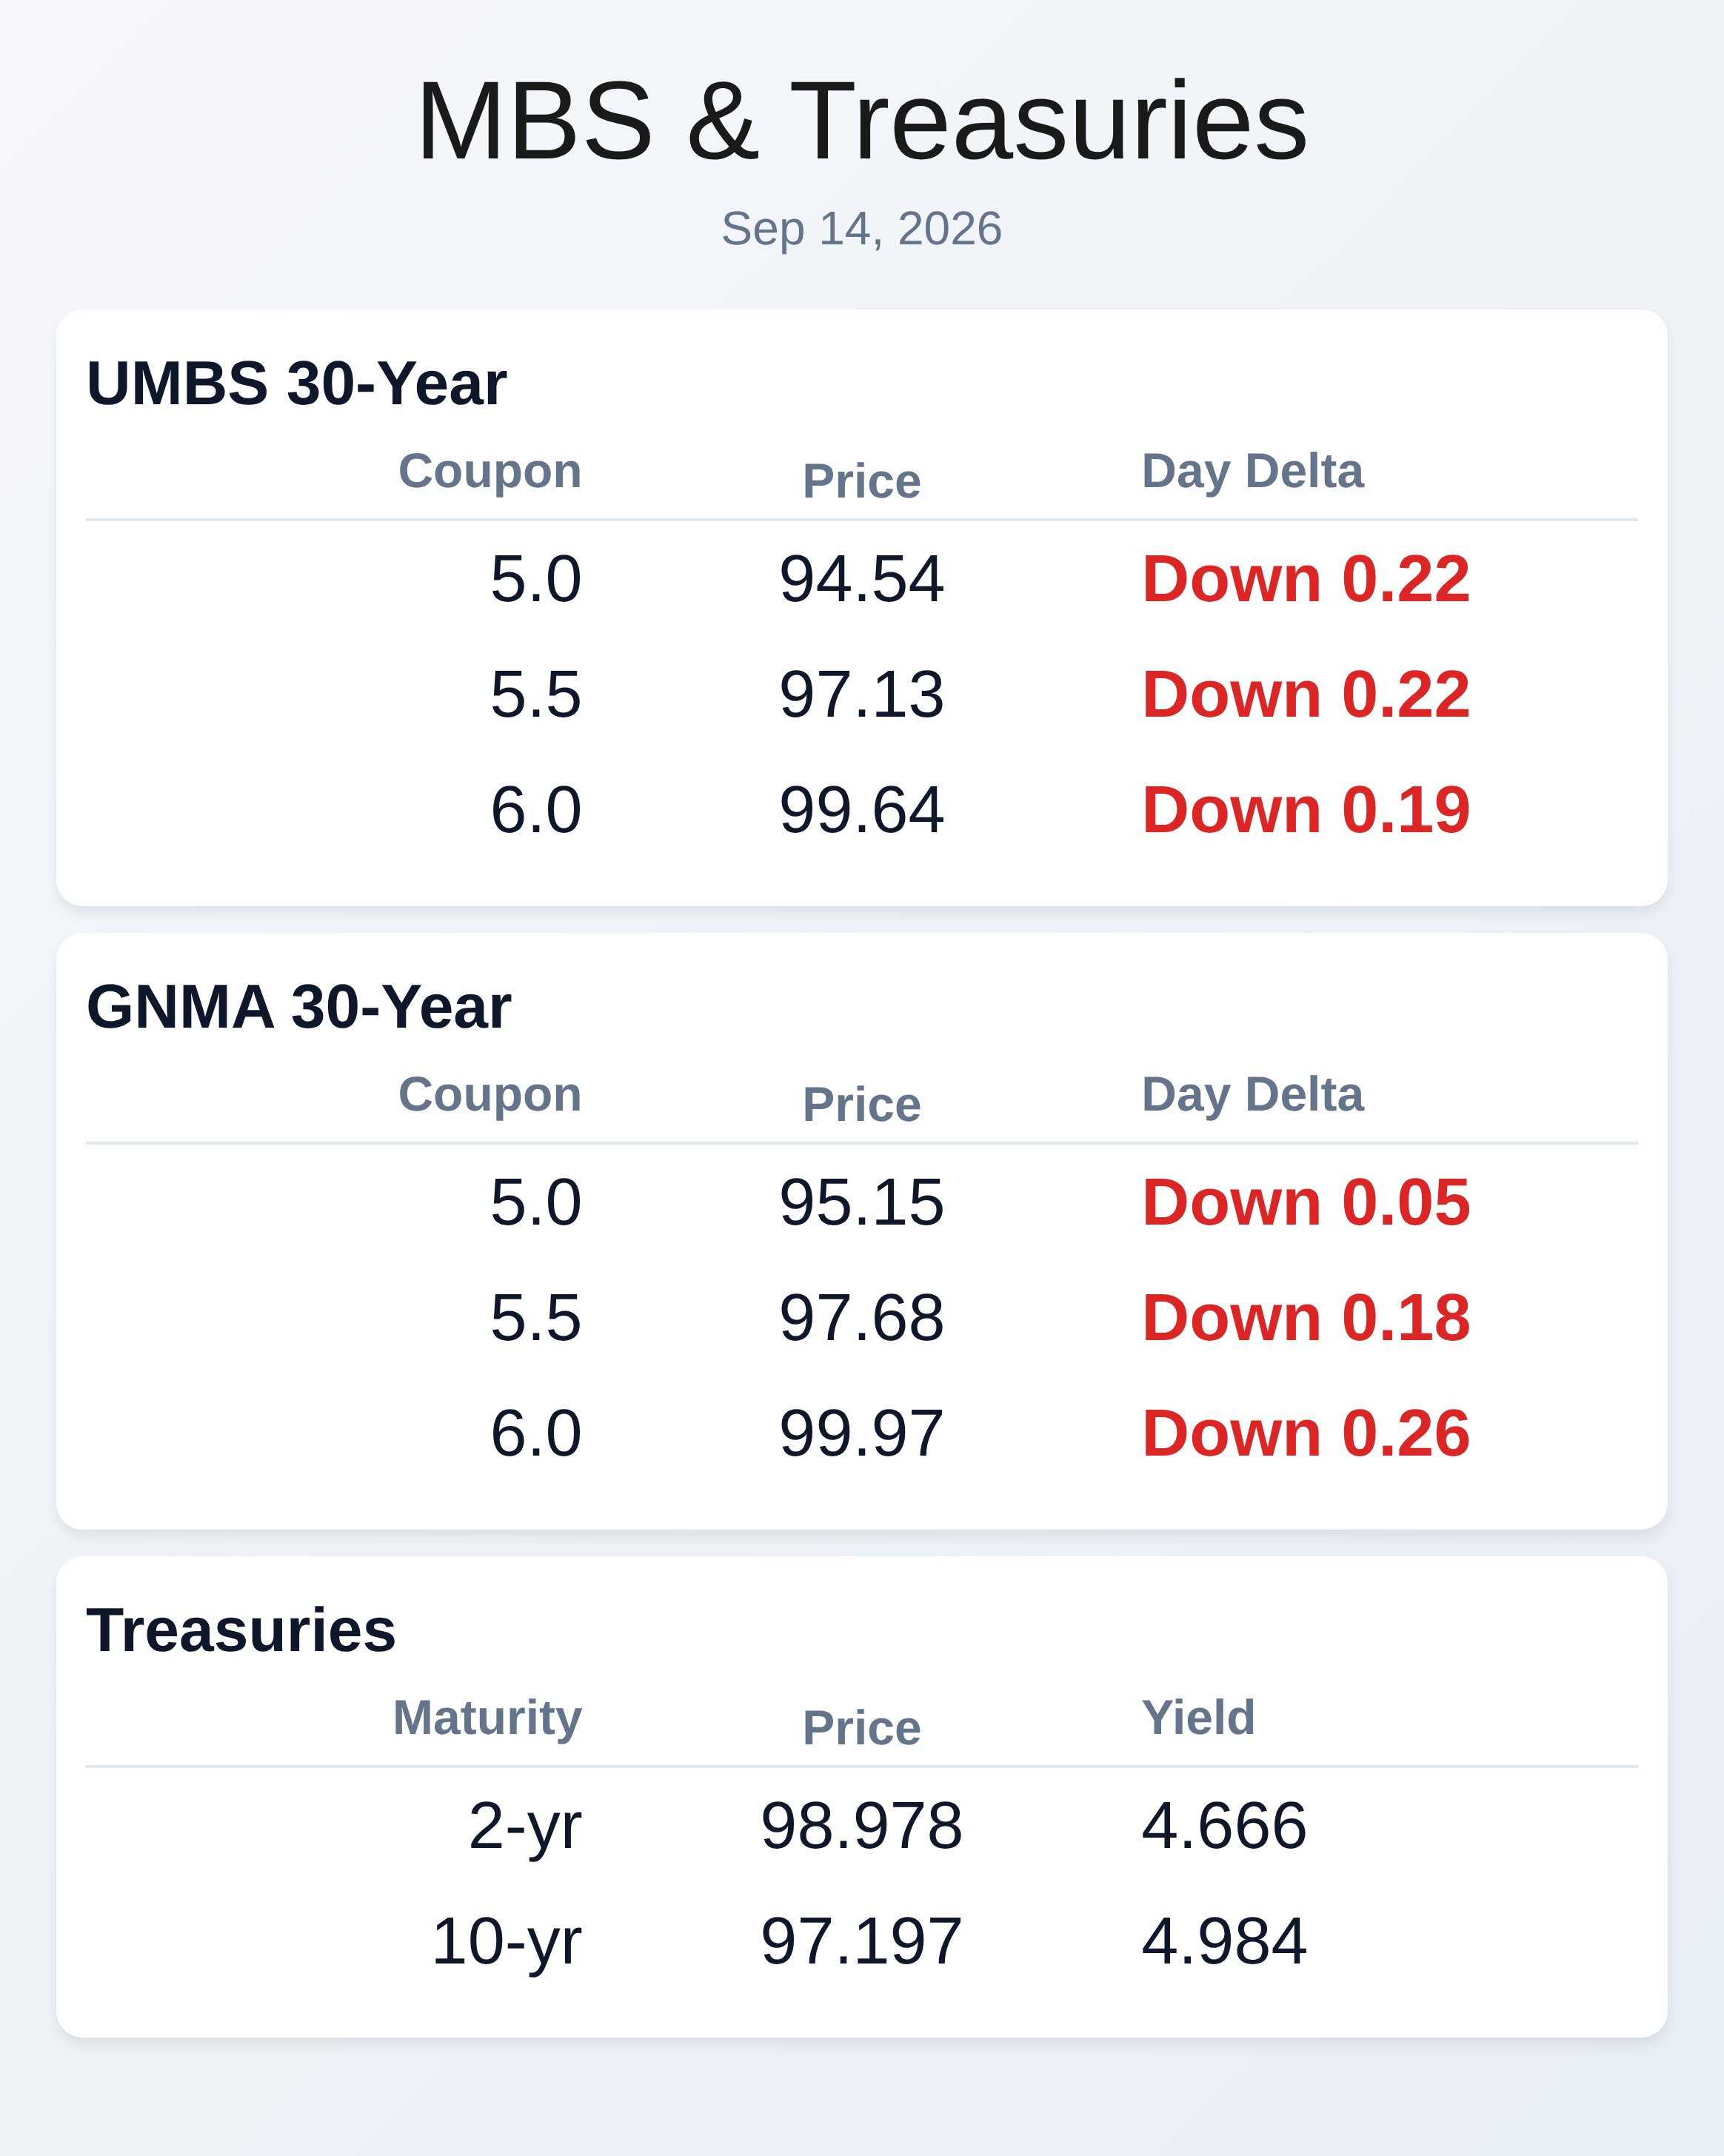
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 09/14/2026** The 10-year Treasury yield hit 5% for the first time since 2007 today as MBS fell sharply, leaving originators facing a pivotal Fed announcement Wednesday that could determine whether rates stabilize or climb further. UMBS 5.5 coupons dropped 22 basis points intraday despite a mid-day rally triggered by war-related headlines suggesting diplomatic progress between the U.S. and Iran. Slower selling momentum and intraday bounces are tempting traders to catch falling knives, but market strategists warn the bigger picture remains unresolved. Mortgage-backed securities showed genuine weakness on Monday, with GNMA 5.5 coupons down 18 basis points and UMBS down more than an eighth from morning highs. Mid-day relief came fast when Trump signaled Iran wanted to make a deal, helping bond yields retreat 3.4 basis points and temporarily reversing negative reprice risk. However, technical ceilings remain in place, and Treasury yields could exceed 5.2% by year-end if analyst Steven Barrow's forecast proves accurate. The real test arrives with Wednesday's Fed decision and Kevin Warsh's subsequent guidance. Smaller and mid-sized mortgage companies face growing M&A pressure as profitable lenders recognize they lack capital for the next rate cycle. STRATMOR data shows roughly 40 M&A transactions last year, up from 25 in 2024, with pricing now attractive enough to pull in healthy sellers rather than just distressed shops. Atlantic Bay Mortgage is aggressively hunting targets outside its Southeastern stronghold, aiming for top-five status in new purchase markets while competing against giants through nimbleness and personalized support. Primis Mortgage, operating inside a bank balance sheet, projects hitting $3 billion organically next year while avoiding the LO recruiting arms race with massive upfront contracts. Chase initiated mortgage rate discounts of up to 25 basis points ahead of the Fed meeting, demonstrating how large banks leverage customer relationships and balance sheets to move independently of broader market weakness. The promotion underscores that Wednesday's rate decision matters less than how individual lenders reprrice immediately after the announcement. Originators holding tight to defensive lock strategies remain wise until confirmed trend shifts emerge. War-related volatility and Fed uncertainty create 2-way risks through at least midweek. Standard Bank strategist Steven Barrow raised his 10-year Treasury estimates to 5.3% in Q1 2027, citing unfinished bond market correction and potential inflation persistence. Market traders increasingly expect a Fed rate hike this week despite modest bond market recoveries today. The combination of sticky inflation, geopolitical tension, and technical ceiling breaks suggests upward pressure on yields could resume quickly after any mid-day relief proves temporary. Mortgage companies should monitor Treasury technical levels closely rather than assume Fed guidance will bring certainty. Credit card debt is driving homeowners toward home equity solutions, creating a meaningful origination opportunity for refinance-focused shops. Figure's partnership with Sierra reportedly lifted HELOC conversion rates by 143% using AI to identify and connect borrowers with human originators. Meanwhile, regulators proposed risk-based vendor oversight frameworks that could ease compliance pressures on mortgage companies using third-party technology. The week ahead will reshape lock-float decisions and production strategy. **Locking vs Floating** Slower selling pace and decent intraday bounces are increasing temptation to abandon defensive positioning and catch falling knives. MBS Live strongly advises waiting for a confirmed trend shift before adjusting lock-float strategy. High volatility through Wednesday's Fed announcement remains probable, and geopolitical headlines create two-way risks until further clarity emerges. **Today's Events** No scheduled economic data releases reported for September 14, 2026. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.0 | 94.54 | -0.22 | | 5.5 | 97.13 | -0.22 | | 6.0 | 99.64 | -0.19 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | | 5.0 | 95.15 | -0.05 | | 5.5 | 97.68 | -0.18 | | 6.0 | 99.97 | -0.26 | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change |

Market Data
Mortgage Today (AM) - 09/14/26 {{catlist}}
September 14, 2026
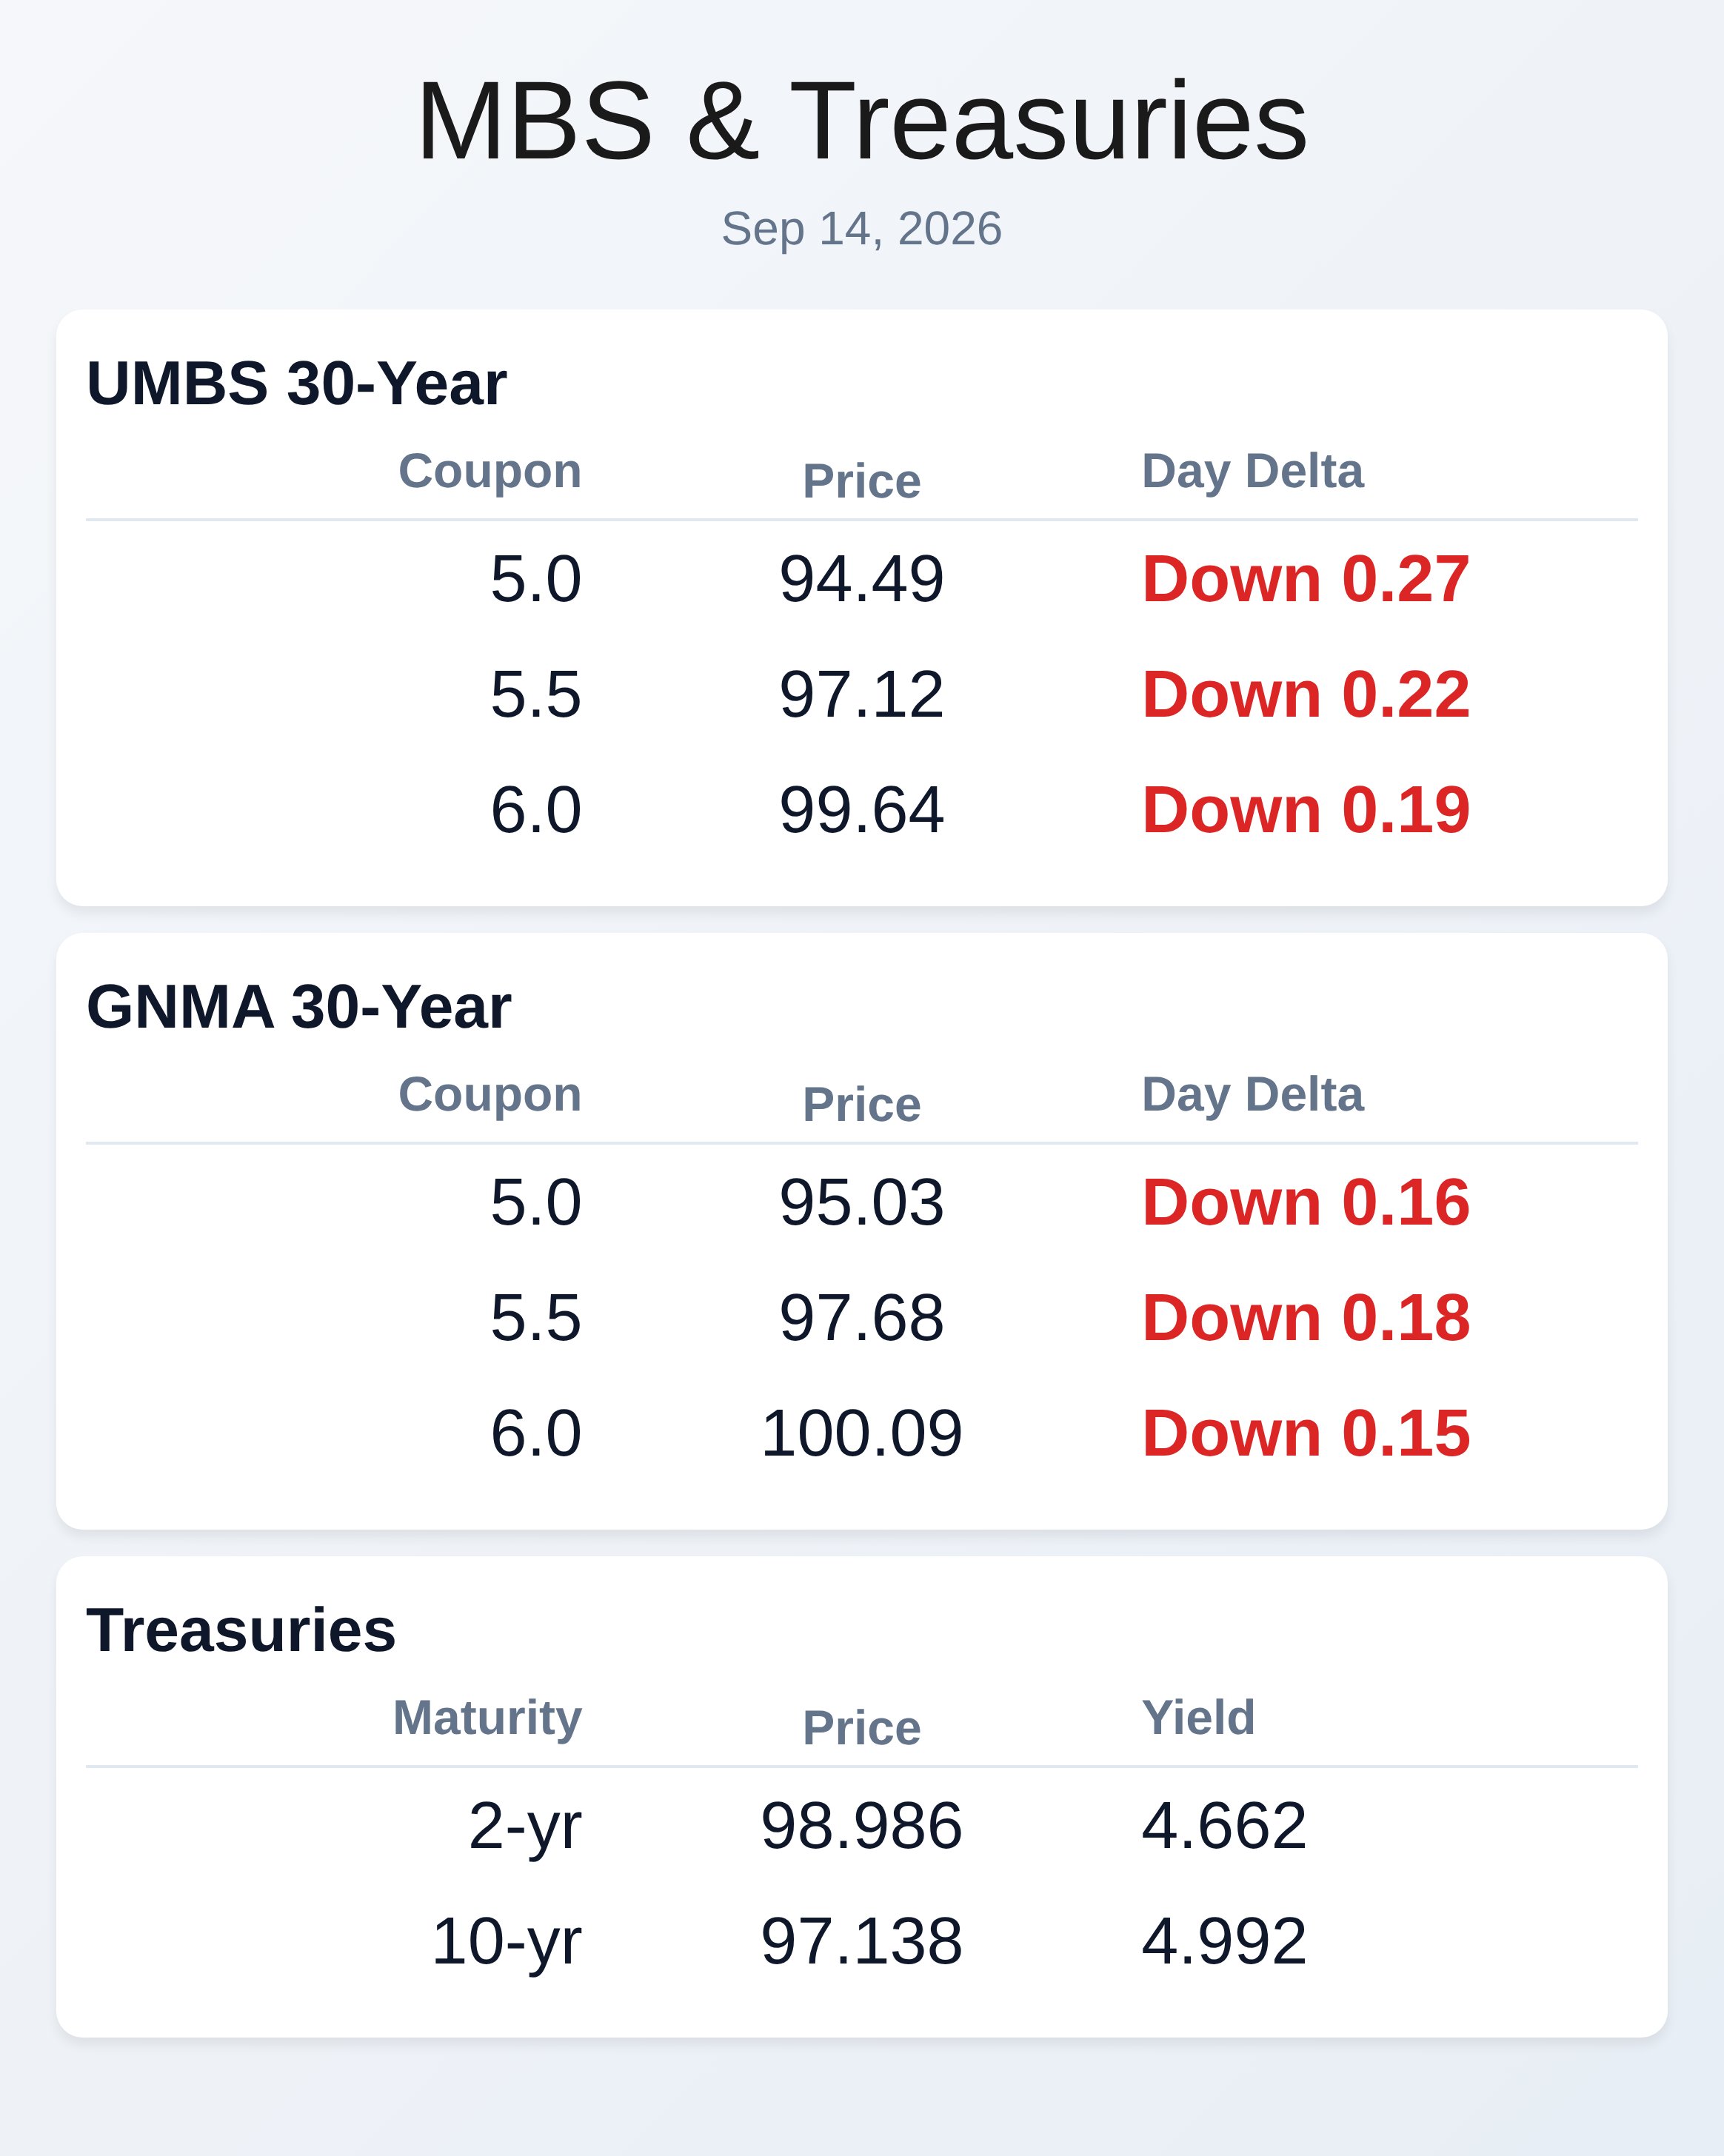
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/14/2026** This morning's market opened with a rally that has completely erased by the close, as UMBS securities fell sharply and the 10-year Treasury yield pushed toward 5 percent on renewed inflation concerns. MBS prices reflected heavy selling pressure with current coupons losing ground across all coupon levels, signaling investor anxiety ahead of Wednesday's Federal Reserve decision. The rally that began the session fell victim to snowball selling momentum, a reminder that even intraday gains offer no guarantee of recovery in a bear market. August's CPI report hit expectations with core inflation rising 0.3 percent month over month—hotter than forecast—pushing CME FedWatch odds of a September 16 rate hike to 85.4 percent. Existing home sales fell 10.7 percent from July to August while inventory reached its highest level in years, yet falling prices still fail to attract buyers as borrowing costs climb relentlessly. The path to rate relief now depends entirely on inflation moderating, a scenario that remains firmly out of reach for homebuyers this quarter. Mortgage servicers and foreclosure attorneys face AI litigation risk that extends far beyond the AI tools they directly control. A Washington D.C. appellate court struck Deutsche Bank's foreclosure brief after its outside law firm cited four fictitious court cases generated by Google's AI search tool, with the court referring the matter to disciplinary counsel. This warning signals that compliance exposure flows through every external vendor and third-party counsel involved in loan servicing, title work, and legal defense—creating enterprise-wide accountability for AI failures originators never knew were happening. Nonbank lenders are rapidly capturing share in the home equity market, growing HELOC originations 140 percent between 2023 and 2025 compared to just 7 percent at large banks. American homeowners hold a record $34.9 trillion in residential real estate equity, with mortgage borrowers commanding $17.9 trillion of that, including roughly $11 trillion available to tap. The competitive dynamics have shifted decisively: nonbanks now capture 29 percent of subordinate-lien originations, up from just 8 percent in 2022, forcing institutions to decide whether to compete or accept margin compression. Oil prices surged above $100 per barrel following Saudi Arabia's closure of its East-West pipeline, reigniting energy-driven inflation concerns that complicate the Fed's policy path this week. The 10-year Treasury yield rose 20 basis points over last week to 4.98 percent while the 2-year climbed 27 basis points to 4.64 percent, bearing-flattening the curve by 8 basis points. Global equities tumbled as AI firms proposed slowing development, with tech stocks falling 5 percent and the Nasdaq 100 futures down 1.5 percent in early trading. Market consensus now prices a 25-basis-point Fed hike on Wednesday as fait accompli, with traders increasingly betting on a second increase before year-end. The key question this week shifts from whether the Fed hikes to what new "dot plot" projections imply about the path beyond September and whether energy inflation becomes a persistent economic headwind. With housing starts, building permits, pending home sales, and leading indicators all reporting this week, originators should expect continued volatility as the market reprices expectations for both monetary policy and economic growth. **Locking vs Floating** Today reinforced the power of prevailing market momentum once again. When bonds enter snowball selling mode, even morning rallies offer no lasting protection—a defensive locking strategy remains the only reliable stance. Heavy selling does introduce occasional bounce opportunities, but these are notoriously difficult to time and carry no guarantee of becoming sustained turning points. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.0 | 94.49 | -0.27 | | 5.5 | 97.12 | -0.22 | | 6.0 | 99.64 | -0.19 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | |---:|---:|---:| | 5.0 | 95.03 | -0.16 | | 5.5 | 97.68 | -0.18 | | 6.0 | 100.09 | -0.15 | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | |---|---:|---:|---:| | 2 yr | 4.662 | 98.986 | 0.043 | | 3 yr | 4.756 | 98.945 | 0.036 | | 5 yr | 4.822 | 98.036 | 0.037 | | 7 yr | 4.901 | 97.647 | 0.04 | | 10 yr | 4.992 | 97.138 | 0.023 | | 30 yr | 5.364 | 96.453 | 0.009 | Stay ahead of market shifts—subscribe free to WTMS Blog at WellThatMakesSense.com. Market Data
Mortgage Today (AM) - 09/11/26 {{catlist}}
September 11, 2026
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/11/2026** Bond markets logged a paradoxical rally today as inflation data sparked a 90% probability of a Federal Reserve rate hike next week. The August core CPI came in at 0.3% month-over-month versus a 0.2% forecast, pushing the 10-year Treasury yield to near 5% before recovering slightly to 4.947%. UMBS securities strengthened across all coupons, with the 30-year 5.5 coupon climbing 30 basis points intraday to 97.75, signaling bond investors' appetite for inflation-fighting policy. Mortgage rates have crested above 7% for the first time since May 2025, hitting 7.07% on the 30-year fixed as rising oil prices and Treasury yields compressed lending margins. Lenders are responding by tightening credit availability on jumbo and cash-out refinance products, with the MBA's Mortgage Credit Availability Index falling 1% in August to 107.3. For originators, the tightened credit box means fewer program options and higher qualification standards for borrowers sitting in the jumbo zone. Rocket Mortgage and CrossCountry Mortgage jumped ahead of the FHFA's official announcement by raising their conforming loan limits to $845,000, effective immediately and representing a $12,250 increase from 2026's $832,750 ceiling. This proactive move keeps more high-balance borrowers in the conventional channel rather than forcing them into jumbo underwriting and pricing. The implied 1.47% increase for 2027 suggests a slower pace of home-price appreciation compared to prior years. Home insurance premiums hit a record high at $209 monthly in Q2 2026, now consuming 9.6% of the average mortgage payment, according to ICE data tracking over 650,000 properties. Regional disparities remain stark, with New Orleans seeing insurance represent 24.3% of total monthly housing costs while San Jose holds at just 4.3%. The 8.7% annual increase represents an 80% surge since 2020, though the quarterly pace of increases appears to be moderating. Prepayment speeds for UMBS securities have slowed sharply, with Fannie Mae 30-year speeds declining 12% month-over-month to 7.1 CPR in August—the slowest pace since April 2025. With only 3.4% of conventional borrowers currently refinance-incentivized at today's higher rates, originators face muted purchase and refinance volume heading into fall. Servicer composition continues to matter, with Rocket/Quicken, Huntington, and Fifth Third showing faster speeds while Rushmore and Marlin remain slower. Oil prices surged overnight and Treasury Secretary Bessent's first Treasury buyback operation fell short of expectations, keeping downward pressure on bonds despite the Fed's hawkish inflation stance. The 10-year yield remains elevated near 5%, and a breach above that psychological level could strain equities and heighten concerns over the sustainability of public finances. Traders now price two Fed rate hikes by January 2027, betting heavily that higher rates will finally cool inflation and stabilize the mortgage market. **Locking vs Floating** August inflation data has shifted the lock-versus-float equation decisively toward locking. With the Fed highly likely to hike rates next week and mortgage rates already above 7%, borrowers face a narrowing window to lock in protection. The bond market's aggressive repricing reflects inflation pressures that the Fed must address, meaning further rate hikes remain probable. Floating strategies carry substantial risk given the hawkish pivot. **Today's Events** August Consumer Price Index (CPI) m/m Headline: 0.4% vs. 0.4% forecast August CPI m/m Core: 0.3% vs. 0.2% forecast, 0.2% prior August CPI y/y Headline: 3.4% vs. 3.4% forecast August CPI y/y Core: 2.4% vs. 2.4% forecast, 2.5% prior September Preliminary University of Michigan Consumer Sentiment (later today) August Treasury Budget (later today) **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.0 | 95.06 | 0.27 | | 5.5 | 97.68 | 0.23 | | 6.0 | 100.11 | 0.20 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | | 5.0 | 95.44 | 0.08 | | 5.5 | 98.15 | 0.06 | | 6.0 | 100.56 | 0.10 | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2 yr | 4.588 | 99.124 | 0.009 | | 3 yr | 4.674 | 99.172 | -0.009 | | 5 yr | 4.742 | 98.382 | -0.015 | | 7 yr | 4.832 | 98.047 | -0.024 | | 10 yr | 4.933 | 97.594 | -0.033 | | 30 yr | 5.331 | 96.939 | -0.035 | Market Data
LATEST ARTICLES

RECENT ARTICLES

Article Archive

Subscribe

Send me some brain food

Go to Top