Loading...
HOME2023-01-22T13:43:33-07:00

Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (AM) - 09/16/26 {{catlist}}
September 16, 2026
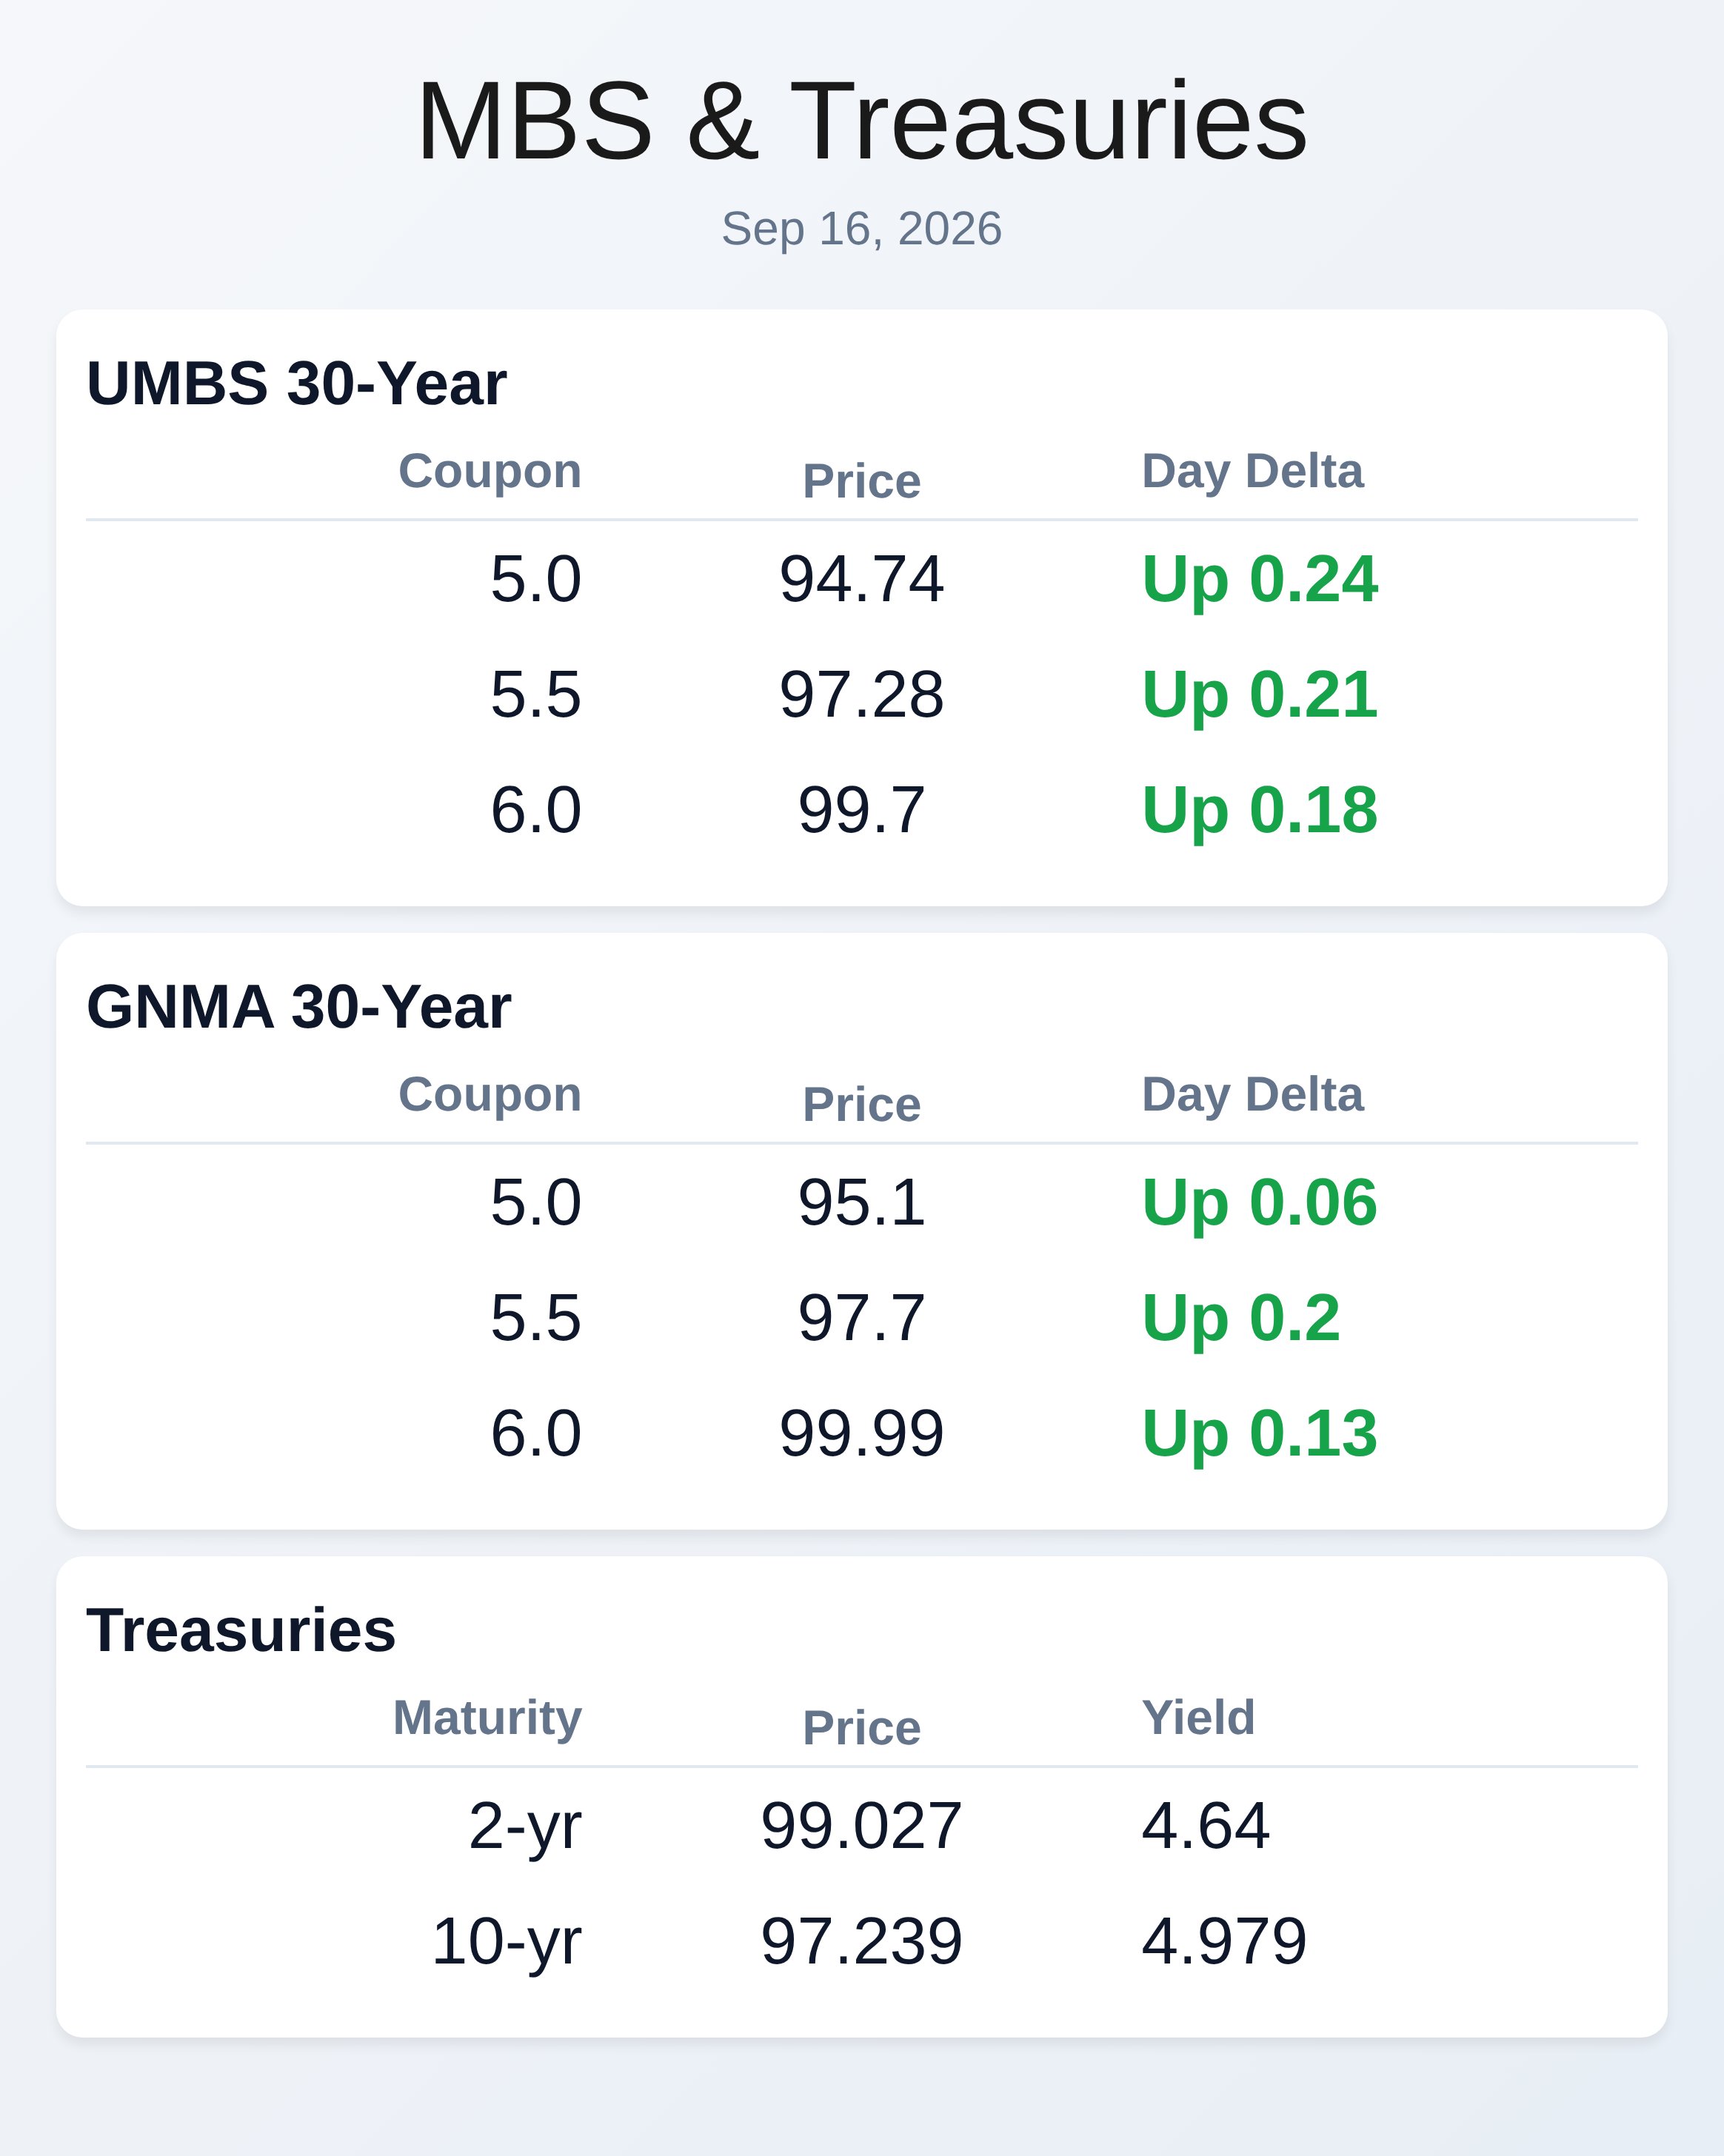
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/16/2026** The Federal Reserve faces the market's spotlight this afternoon as traders price in a 90%+ probability of the first rate hike since 2023, a move widely expected to lift borrowing costs across mortgages and refinance activity. MBA applications fell 4.1% last week as rising energy prices and Treasury yields pushed the 10-year yield toward 5%, while refinance activity plummeted 9% week-over-week and remains down 65% year-over-year. August retail sales beat expectations at 1.2% versus a 0.8% forecast, demonstrating consumer resilience despite inflation concerns that sparked this rate-hike cycle. Import prices also surprised upward at 0.7% monthly, reinforcing inflation pressures that justify the Fed's tightening stance. The tone of Fed Chair Kevin Warsh's press conference will matter more than the rate decision itself, as any hawkish messaging could trigger another leg higher in yields. Agency MBS and Treasury prices found slight relief early Wednesday as crude oil dipped below $108 per barrel and traders prepared for the central bank's announcement. UMBS 30-year coupons improved modestly, with the 6.0 coupon closing at 99.70 (up 0.18), while the 10-year Treasury yield moved to 4.97% from 4.98% overnight. Foreign demand for longer-duration Treasuries remains soft, evidenced by the weak 20-year Treasury reopening that required a 5.42% yield to clear, nearly 60 basis points higher than the prior auction. The dollar pared losses and equities positioned for a morning rally, though sentiment remains fragile. Warsh's communications strategy—whether he signals further tightening beyond today or commits to a data-dependent path—will determine bond market direction heading into year-end. Purchase mortgage applications declined 1% seasonally adjusted and sit 19% below last year's levels, underscoring persistent headwinds from higher rates and compressed affordability that shows no sign of easing. Refinance volume dropped even more sharply, signaling that borrowers with existing mortgages have largely locked in rates and view opportunities for refi as limited. Applications data released this morning revealed the human cost of Fed policy: stretched borrowers with thinner margins for error in their loan files. Each rate move ripples through origination pipelines as would-be homebuyers delay purchase decisions. Disaster declarations from FEMA (Indiana tornadoes and Hawaii earthquakes) add additional operational complexity for lenders and servicers in affected regions. The economic calendar this afternoon piles on the Fed's evidence: July Business Inventories, September NAHB Housing Market Index, and crude oil inventory levels all arrive before the 2 p.m. rate decision. These data points collectively paint a picture of an economy still firing on cylinders—strong consumption, robust job markets, and pricing power in the supply chain. Treasury yields have already climbed to multiyear highs on inflation concerns, leaving the bond market little room to rally if Warsh disappoints hawks. The combination of above-target inflation, surging energy costs, healthy employment, and solid GDP growth leaves policymakers with minimal political cover to hold steady. Mortgage originators now face the reality that rate lock periods could face pressure if Fed communication signals further tightening down the road. Private equity continues reshaping industry peripherals beyond just mortgage lending and servicers. Genstar Capital and Aksia announced a strategic growth investment in Richey May, a top 50 U.S. accounting and advisory firm, signaling continued M&A appetite among financial sponsors. The capital will fund Richey May's organic growth and acquisition strategy as it builds a national platform, though founder ownership remains materially intact. Tech transitions dominate vendor conversations as credit unions and lenders evaluate platform upgrades ahead of the November 2 Uniform Appraisal Dataset (UAD) 3.6 deadline. Floify emphasized the need for vendors to shoulder implementation heavy lifting and maintain post-go-live support, a lesson learned from prior mortgage system conversions. Jumbo lending tools like Symmetry's piggyback HELOC structure gain traction as borrowers navigate affordability challenges with bridge alternatives. Subscribe free at **WellThatMakesSense.com** for daily mortgage market updates and origination insights. **Locking vs Floating** Markets face elevated uncertainty heading into the Fed announcement, with oil prices and inflation data creating volatility in both directions. Technical support emerged in bond markets today, yet momentum remains contested and could shift dramatically on Warsh's guidance. Originators should prepare for continued rate volatility through the weekend as traders digest the policy decision and guidance on future tightening. Any signal of additional hikes beyond today will pressure purchase and refi demand further. Lock recommendations depend on pipeline composition, but defensive positioning seems warranted until a clearer reversal in bond yields takes hold. **Today's Events** Import prices (August): 0.7% vs. 0.4% forecast, -0.4% prior Retail sales (August): 1.2% vs. 0.8% forecast, -0.6% prior Retail sales control group (August): 1.4% vs. 0.4% forecast, -0.4% prior Headline CPI (August): 3.4% vs. 3.4% forecast, 3.4% prior MBA mortgage applications: Down 4.1% week-over-week; refinance down 9% w/w, -65% year-over-year; purchase applications down 1% seasonally adjusted, -19% year-over-year July business inventories (afternoon) September NAHB Housing Market Index (afternoon) Weekly crude oil inventories (afternoon) September FOMC decision and press conference (2 p.m. EDT) **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2yr | 4.64 | 99.027 | -0.023 | | 3yr | 4.736 | 99.001 | -0.028 | | 5yr | 4.804 | 98.114 | -0.024 | | 7yr | 4.889 | 97.72 | -0.020 | | 10yr | 4.979 | 97.239 | -0.023 | | 30yr | 5.351 | 96.641 | -0.017 | Market Data
Mortgage Today (AM) - 09/15/26 {{catlist}}
September 15, 2026
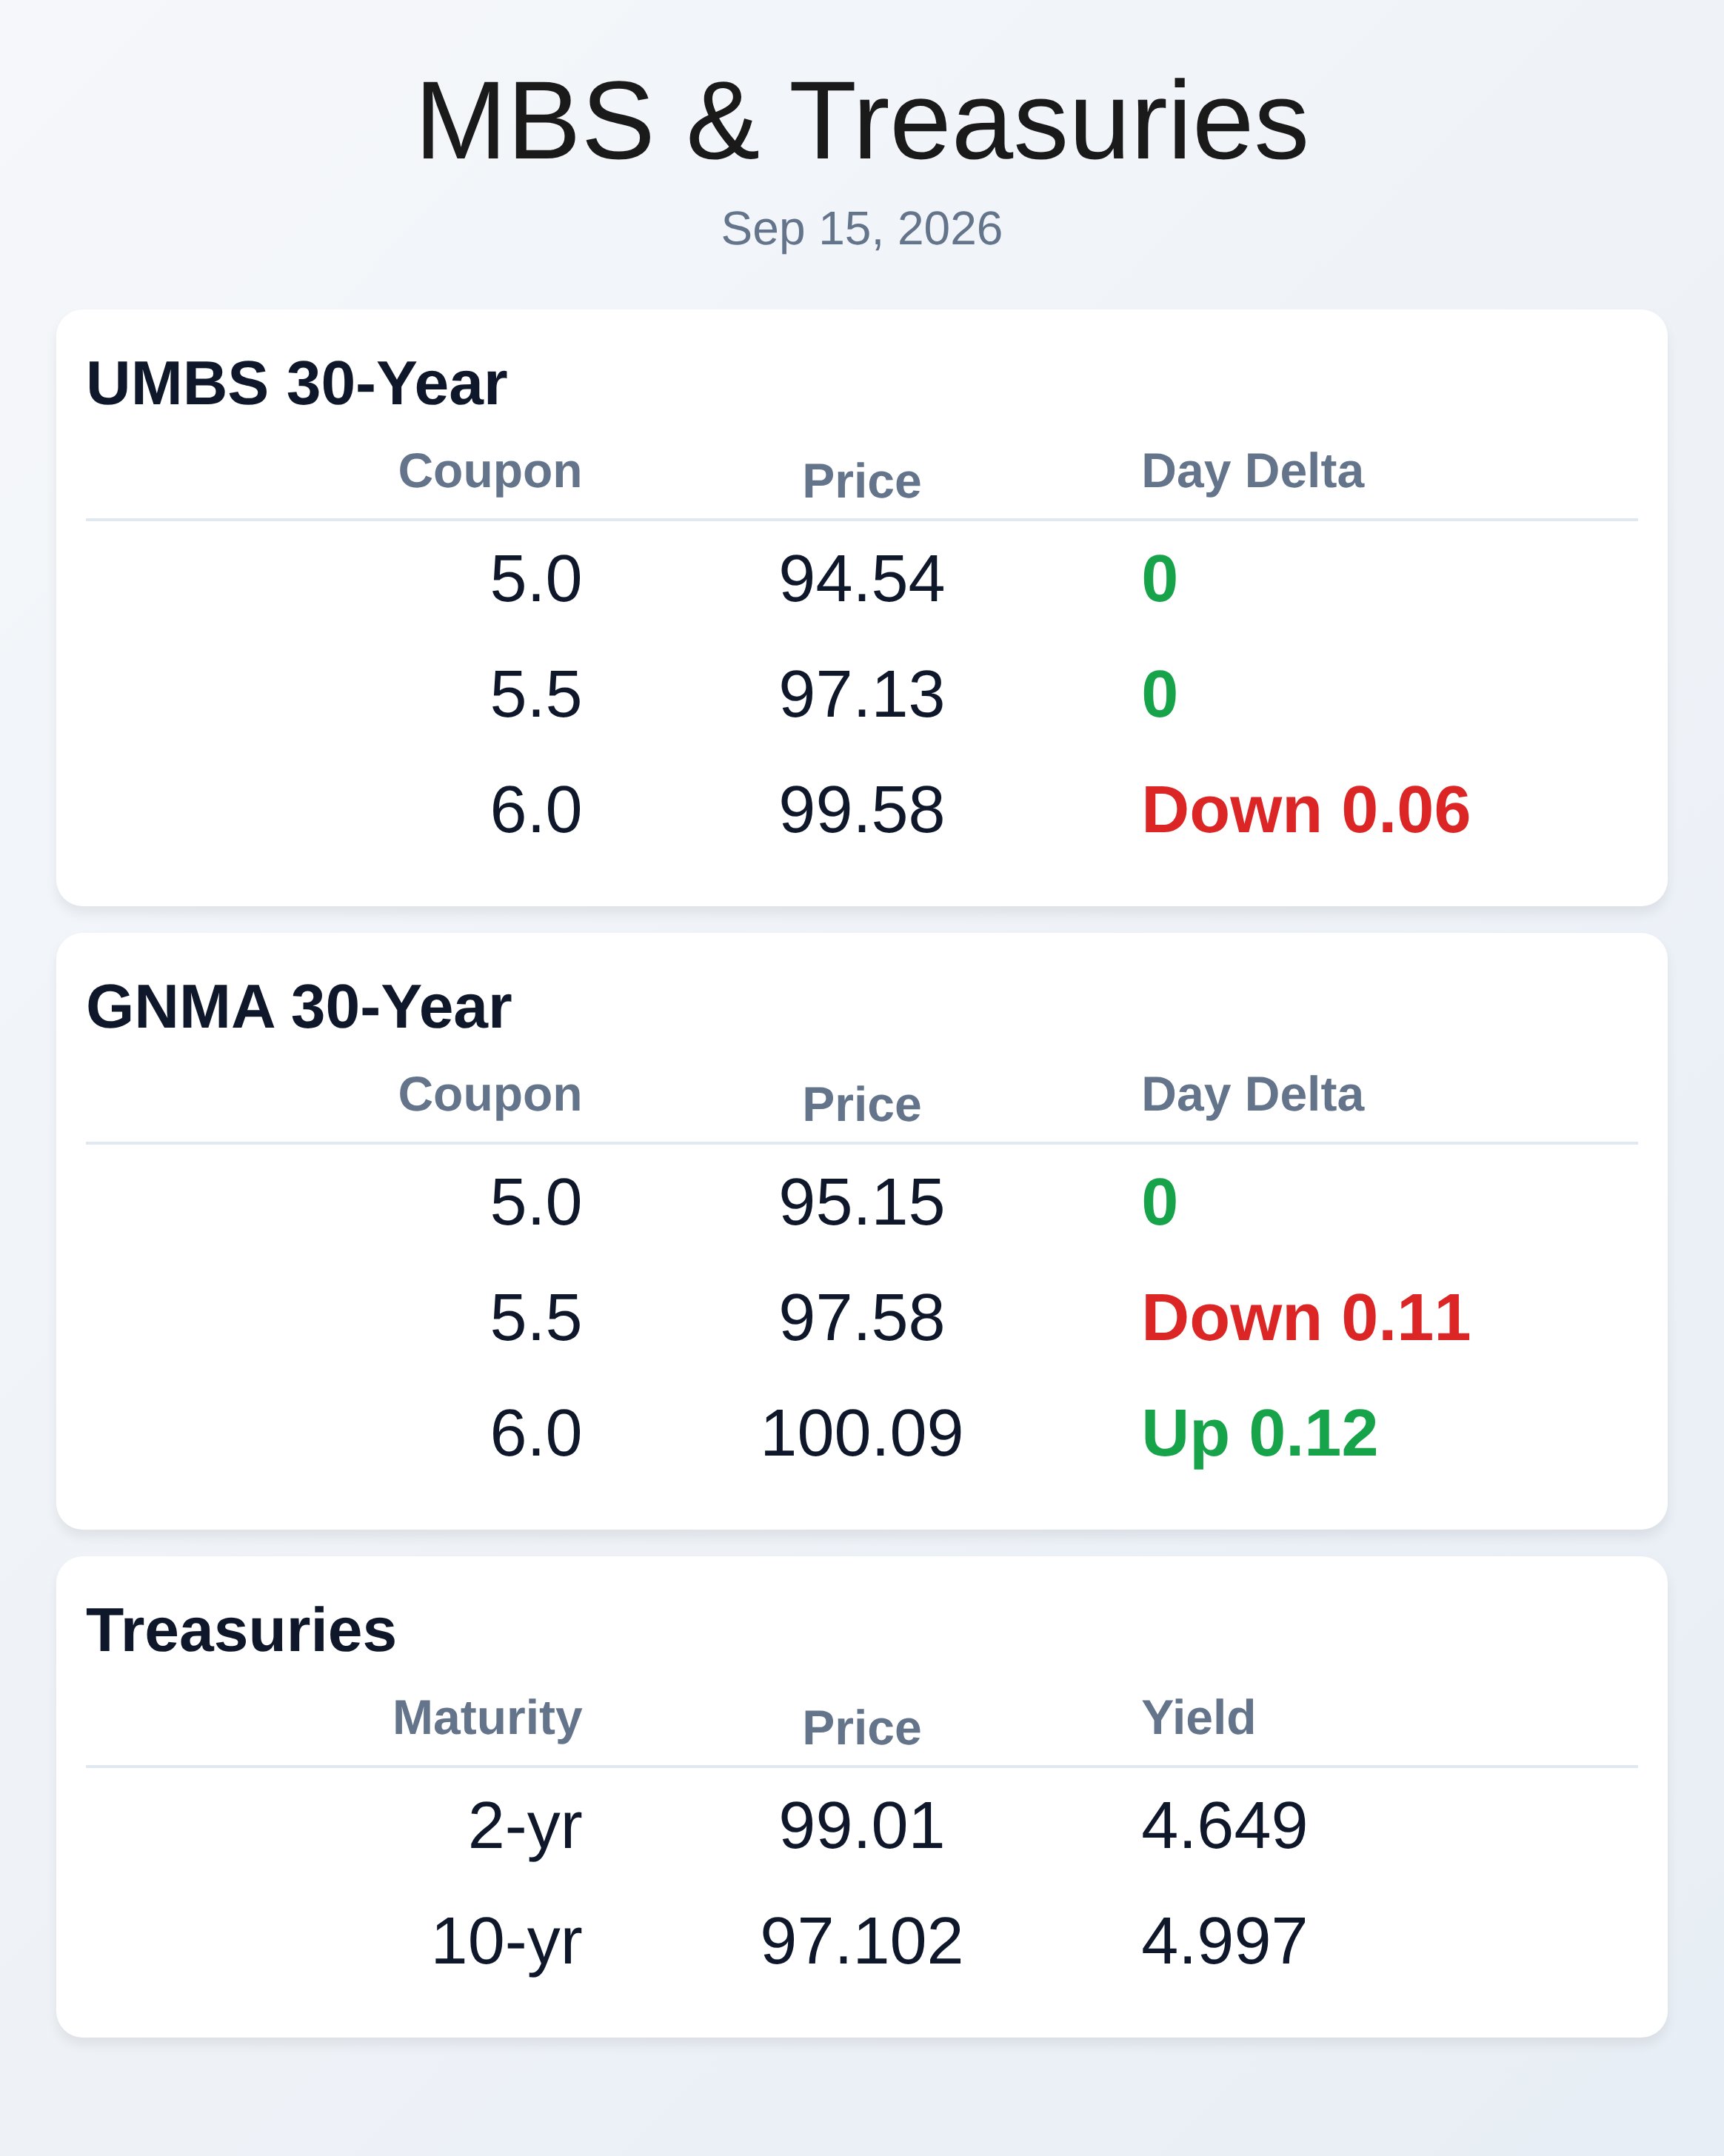
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/15/2026** The 10-year Treasury yield breached 5 percent—for only the third time in two decades—as oil prices surge and bond investors demand higher compensation for inflation risk ahead of tomorrow's Federal Reserve decision. The yield hit 5.04% this morning, matching a 19-year high last seen in 2007 before the financial crisis. Energy prices are the culprit: Brent crude climbed toward $107 a barrel after attacks on Saudi infrastructure, feeding persistent inflation fears. The Fed faces mounting pressure to raise rates tomorrow to defend its credibility after years of inflation overshooting targets. Investors are already pricing in a greater than 90% probability of a 25-basis-point hike. UMBS 30-year coupons showed mixed intraday movement, with the 6.0 coupon down just 0.06 points while the 5.0 and 5.5 coupons held flat at 94.54 and 97.13 respectively. GNMA 30-year bonds displayed similar sideways pressure, with the 6.0 coupon up 0.12 points and the 5.5 coupon down 0.11 points. These muted price swings reflect dealers and originators sitting on their hands while awaiting clarity on the Fed's rate trajectory and its impact on future refinance supply. Mortgage origination volume continues deteriorating, with the MBA refinance index down 58 percent over six months, driven by government borrowers especially VA applicants, which have plummeted 77 percent in that timeframe. Bond market weakness poses a structural headache for mortgage sellers: MBS issuance could fall below $100 billion per month by year-end if refinance activity continues eroding and prepayments remain suppressed. The administration wants lower 10-year yields to boost housing affordability ahead of midterm elections, but Treasury supply pressures and cooling demand from foreign buyers are working in the opposite direction. With only 3.4 percent of borrowers retaining a meaningful refinance incentive today, rate-driven supply shock seems unlikely in the near term. The yield-curve continues flattening, pinching the income margin for loan production and servicing portfolios. Expectations for a sharp decline in yields have been scaled back: strategists now target year-end 10-year yields around 4.60 percent—still above current levels—with persistent upward pressure from both geopolitical oil risks and federal debt issuance needs. Treasury curve is steepening with 2-year yields richer than 10-year yields on a relative basis, a sign that rate-cut expectations beyond 2026 have dimmed considerably. Persistent inflation swaps suggest the bond market has already factored in higher-for-longer rate expectations. The concern among a third of fund managers surveyed is that a disorderly rise in yields could cascade into credit spreads and equity volatility, creating portfolio contagion. Mortgage lock/float decisions remain defensive: slower pace of selling and modest intraday bounces continue to tempt originators to catch falling knives, but advisors recommend waiting for a confirmed trend shift before adjusting lock positioning. Volatility potential remains elevated through at least Wednesday's Fed announcement, with war-related headlines adding two-way risks to markets. The 10-year yield ceiling and floor levels tracked by MBS market watchers are showing bigger-picture bond momentum deterioration. Lenders should use MBS price action for intraday risk management but rely on Treasury yields for strategic positioning decisions. Retail-funded mortgage rates in August averaged 6.52 percent, up 10 basis points from July but still 16 basis points lower than a year ago, according to Curinos data from lenders across the market. Purchase activity remains essentially flat, down less than 1 percent over both six-month and 12-month periods, suggesting housing demand has stabilized at current price levels. The conventional refinance sector showed a 12 percent uptick over three months despite elevated rates, hinting that some borrowers with equity are bypassing rates and capturing home value instead. Cash-out refinances remain the lone origination category showing month-over-month growth, a sign that equity extraction is driving demand more than rate arbitrage. Tomorrow's Fed decision and press conference will reset market expectations and potentially unlock new supply pipelines if officials signal patience on future tightening. **Locking vs Floating** Originators face persistent temptation to lock loans during the intraday bounces we've seen recently, but strategists caution that a single bounce does not confirm a trend reversal in this volatile environment. Continue defending your pipeline with a cautious stance until the 10-year yield shows sustained settlement below the 5 percent psychological level. Volatility should remain elevated at minimum through Wednesday's Fed announcement, and geopolitical risks on oil and Middle East conflict could create sharp intraday swings in either direction. MBS price action can help manage intraday tactical positioning, but base strategic lock/float decisions on longer-dated Treasury yield momentum and ceilings and floors that track the bigger picture. **Today's Events** September Empire State Manufacturing Index (minor data point). Treasury auction for $13 billion of 20-year bonds. Federal Reserve rate decision and press conference (tomorrow, September 16). **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.0 | 94.54 | 0 | | 5.5 | 97.13 | 0 | | 6.0 | 99.58 | -0.06 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | | 5.0 | 95.15 | 0 | | 5.5 | 97.58 | -0.11 | | 6.0 | 100.09 | 0.12 | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2 yr | 4.649 | 99.01 | -0.017 | | 3 yr | 4.748 | 98.968 | -0.008 | | 5 yr | 4.818 | 98.051 | -0.001 | | 7 yr | 4.904 | 97.63 | 0.001 | | 10 yr | 4.997 | 97.102 | 0.012 | | 30 yr | 5.37 | 96.368 | 0.022 | Market Data
Mortgage Today (PM) - 09/14/26 {{catlist}}
September 14, 2026
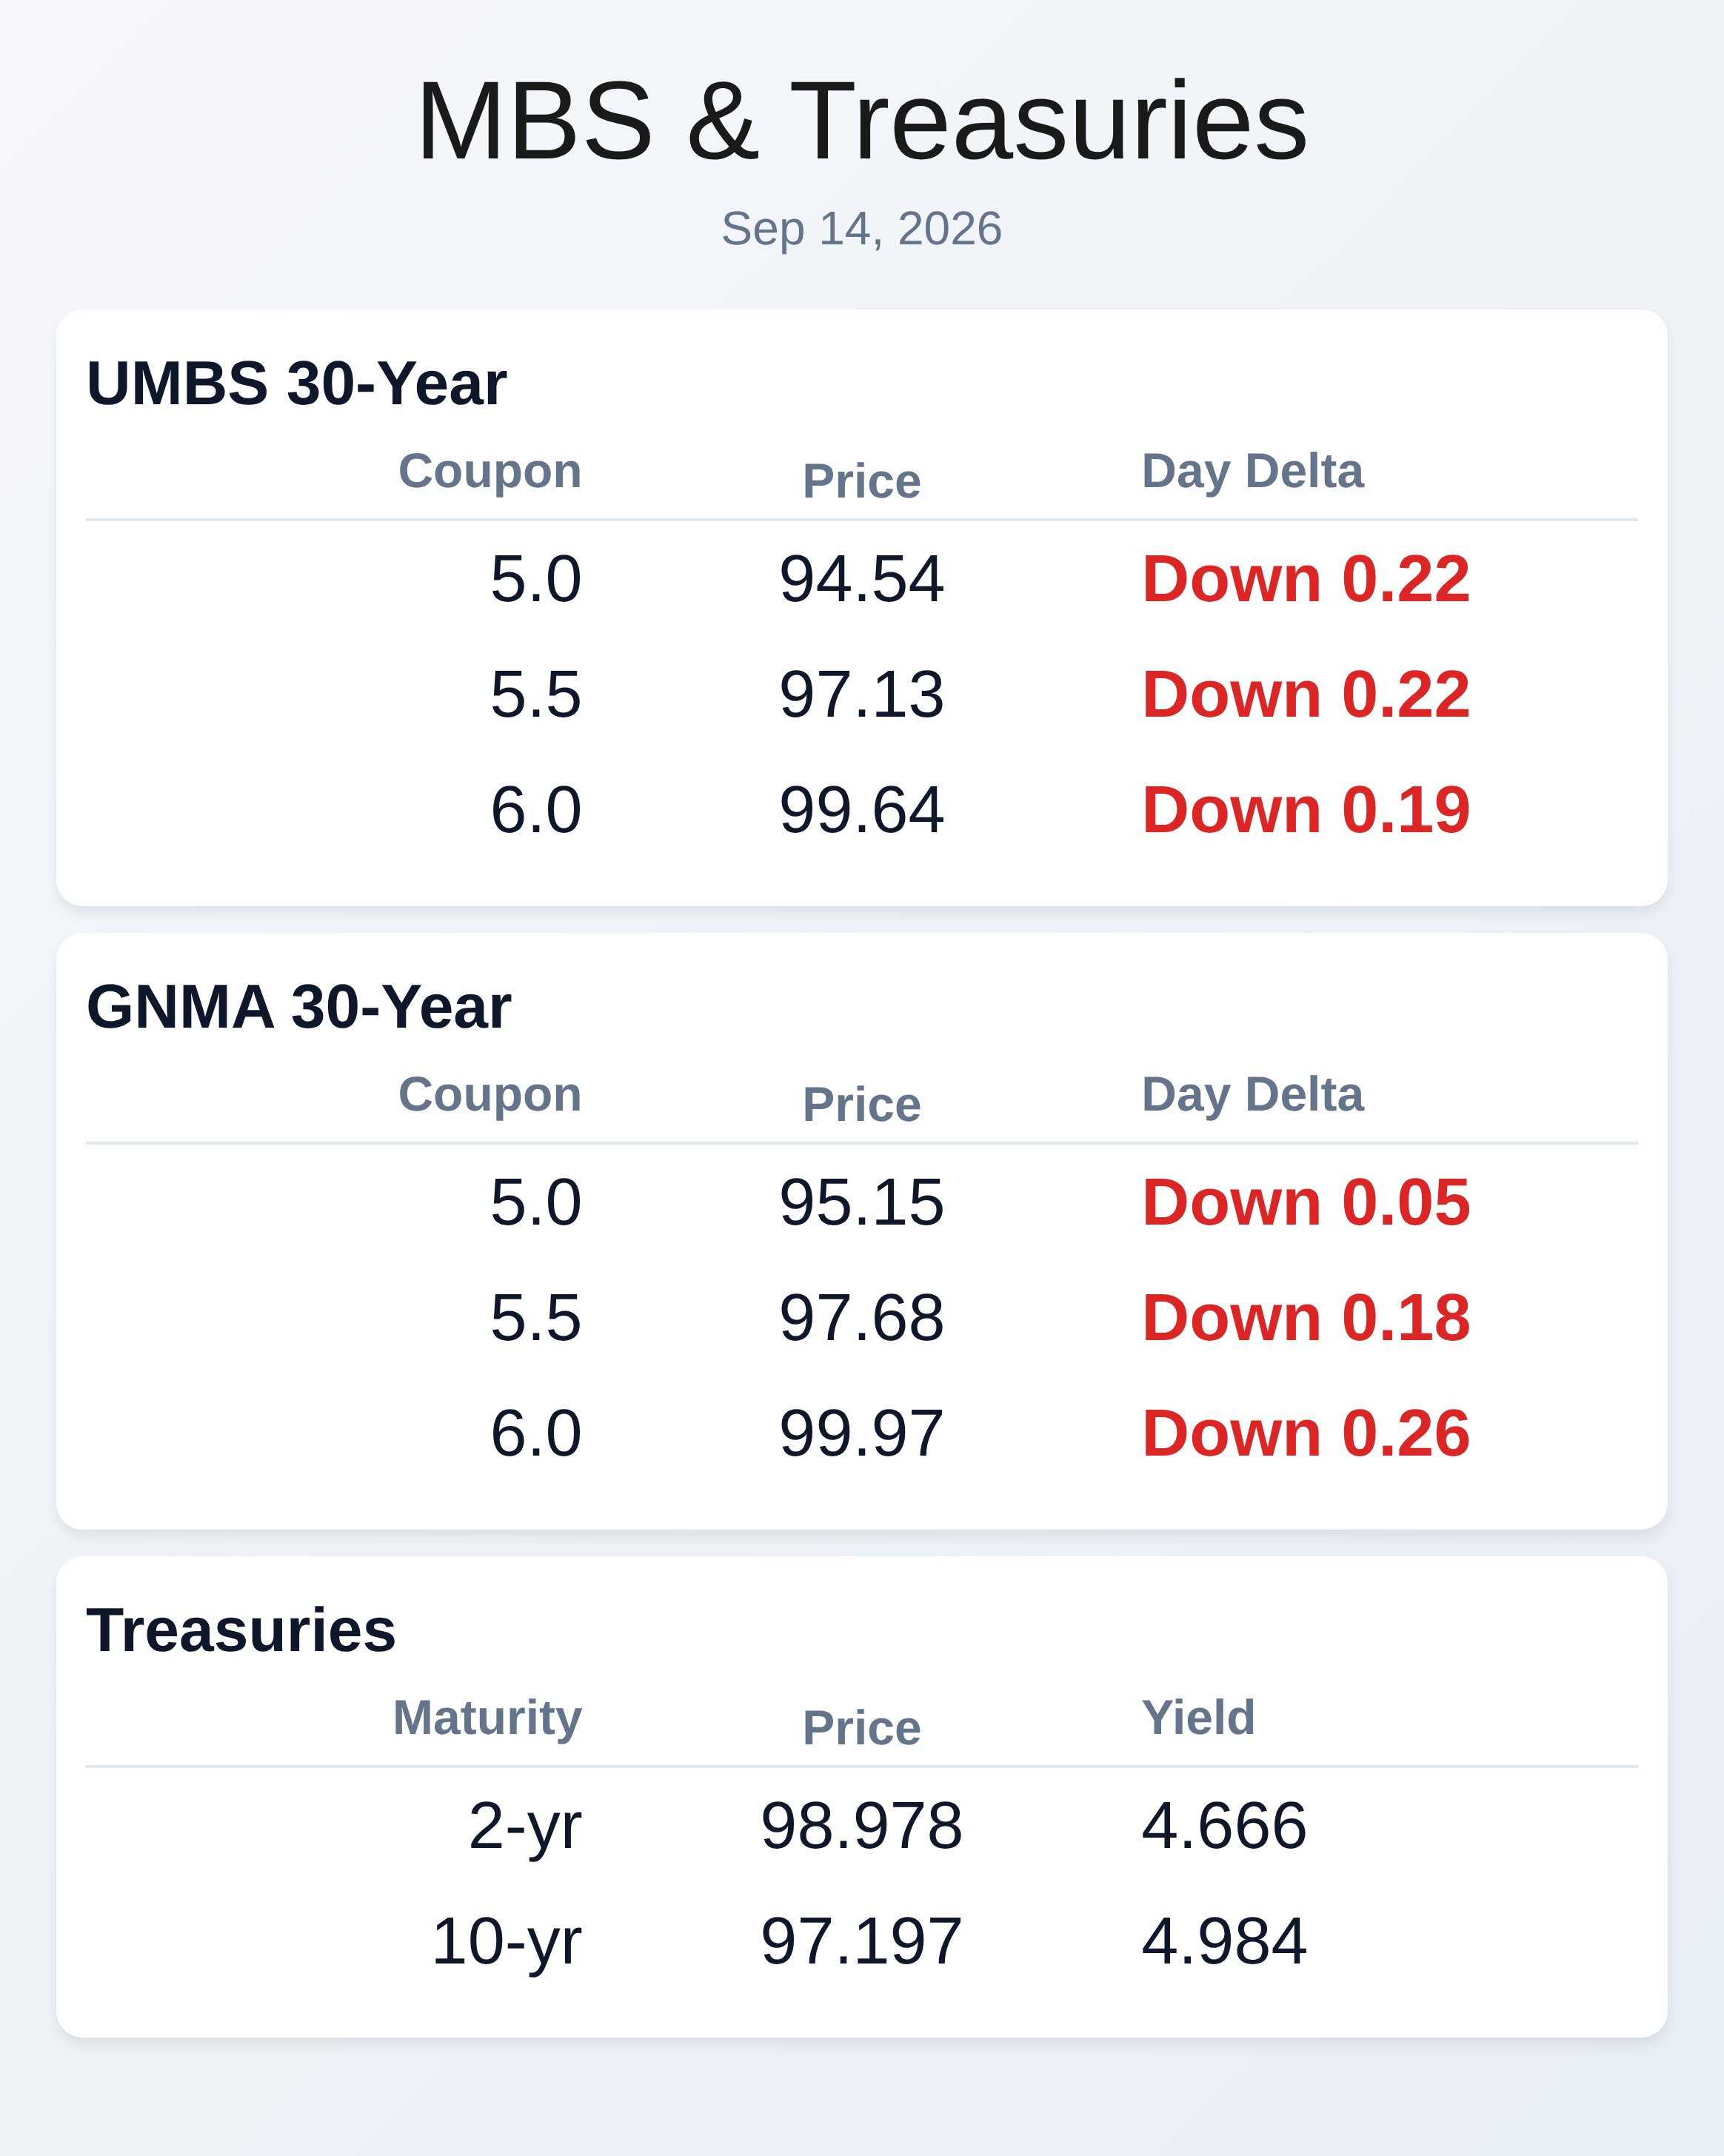
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 09/14/2026** The 10-year Treasury yield hit 5% for the first time since 2007 today as MBS fell sharply, leaving originators facing a pivotal Fed announcement Wednesday that could determine whether rates stabilize or climb further. UMBS 5.5 coupons dropped 22 basis points intraday despite a mid-day rally triggered by war-related headlines suggesting diplomatic progress between the U.S. and Iran. Slower selling momentum and intraday bounces are tempting traders to catch falling knives, but market strategists warn the bigger picture remains unresolved. Mortgage-backed securities showed genuine weakness on Monday, with GNMA 5.5 coupons down 18 basis points and UMBS down more than an eighth from morning highs. Mid-day relief came fast when Trump signaled Iran wanted to make a deal, helping bond yields retreat 3.4 basis points and temporarily reversing negative reprice risk. However, technical ceilings remain in place, and Treasury yields could exceed 5.2% by year-end if analyst Steven Barrow's forecast proves accurate. The real test arrives with Wednesday's Fed decision and Kevin Warsh's subsequent guidance. Smaller and mid-sized mortgage companies face growing M&A pressure as profitable lenders recognize they lack capital for the next rate cycle. STRATMOR data shows roughly 40 M&A transactions last year, up from 25 in 2024, with pricing now attractive enough to pull in healthy sellers rather than just distressed shops. Atlantic Bay Mortgage is aggressively hunting targets outside its Southeastern stronghold, aiming for top-five status in new purchase markets while competing against giants through nimbleness and personalized support. Primis Mortgage, operating inside a bank balance sheet, projects hitting $3 billion organically next year while avoiding the LO recruiting arms race with massive upfront contracts. Chase initiated mortgage rate discounts of up to 25 basis points ahead of the Fed meeting, demonstrating how large banks leverage customer relationships and balance sheets to move independently of broader market weakness. The promotion underscores that Wednesday's rate decision matters less than how individual lenders reprrice immediately after the announcement. Originators holding tight to defensive lock strategies remain wise until confirmed trend shifts emerge. War-related volatility and Fed uncertainty create 2-way risks through at least midweek. Standard Bank strategist Steven Barrow raised his 10-year Treasury estimates to 5.3% in Q1 2027, citing unfinished bond market correction and potential inflation persistence. Market traders increasingly expect a Fed rate hike this week despite modest bond market recoveries today. The combination of sticky inflation, geopolitical tension, and technical ceiling breaks suggests upward pressure on yields could resume quickly after any mid-day relief proves temporary. Mortgage companies should monitor Treasury technical levels closely rather than assume Fed guidance will bring certainty. Credit card debt is driving homeowners toward home equity solutions, creating a meaningful origination opportunity for refinance-focused shops. Figure's partnership with Sierra reportedly lifted HELOC conversion rates by 143% using AI to identify and connect borrowers with human originators. Meanwhile, regulators proposed risk-based vendor oversight frameworks that could ease compliance pressures on mortgage companies using third-party technology. The week ahead will reshape lock-float decisions and production strategy. **Locking vs Floating** Slower selling pace and decent intraday bounces are increasing temptation to abandon defensive positioning and catch falling knives. MBS Live strongly advises waiting for a confirmed trend shift before adjusting lock-float strategy. High volatility through Wednesday's Fed announcement remains probable, and geopolitical headlines create two-way risks until further clarity emerges. **Today's Events** No scheduled economic data releases reported for September 14, 2026. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.0 | 94.54 | -0.22 | | 5.5 | 97.13 | -0.22 | | 6.0 | 99.64 | -0.19 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | | 5.0 | 95.15 | -0.05 | | 5.5 | 97.68 | -0.18 | | 6.0 | 99.97 | -0.26 | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change |

Market Data
LATEST ARTICLES

RECENT ARTICLES

Mortgage Today (PM) – 05/11/26

May 11th, 2026|Week In Review|

  WTMS Blog Today = What's up in Mortgage Today (PM) - 05/11/2026 Bonds ended Monday where they started, trapped in a range after geopolitical news priced in overnight and the market spent the rest [...]

Mortgage Today (AM) – 05/11/26

May 11th, 2026|Week In Review|

WTMS Blog Today = What's up in Mortgage Today (AM) - 05/11/2026   The 10-year Treasury yield jumped 3.2 basis points to 4.39% as crude oil climbed past $97 per barrel on Middle East tensions [...]

Mortgage Today (AM) – 05/08/26

May 8th, 2026|Week In Review|

WTMS Blog Today = What's up in Mortgage Today (AM) - 05/08/2026 Carrington is absorbing Valon Mortgage and its $197 billion servicing portfolio, while also adopting Valon's AI-native servicing platform to replace legacy technology. The [...]

Article Archive

What’s up in Mortgage Today (09/25/2025)

September 25th, 2025|0 Comments

WTMS Blog Today = What's up in Mortgage Today (09/25/2025) Mortgage-backed securities (MBS) markets showed a mixed performance at the start of today, with UMBS 30-year prices experiencing slight declines while GNMA securities saw modest [...]

What’s up in Mortgage Today (09/24/2025)

September 24th, 2025|0 Comments

WTMS Blog Today = What's up in Mortgage Today (09/24/2025) Mortgage-backed securities (MBS) traded mixed today with overall pressure on prices, especially in the UMBS sector. While the UMBS 30-year coupon prices slipped by a [...]

What’s up in Mortgage Today (PM) – 09/23/2025

September 23rd, 2025|0 Comments

WTMS Blog Today = What's up in Mortgage Today (PM) - 09/23/2025 Treasury yields showed mixed movement today as Federal Reserve officials continued their policy discussions following last week's rate cut decision. The 10-year Treasury [...]

What’s up in Mortgage Today (09/23/2025)

September 23rd, 2025|0 Comments

WTMS Blog Today = What's up in Mortgage Today (09/23/2025) Mortgage-backed securities (MBS) experienced mixed movements today with UMBS 30-Year prices showing slight declines, while GNMA 30-Year securities demonstrated modest gains. The UMBS 30-Year prices [...]

What’s up in Mortgage Today (PM) – 09/22/2025

September 22nd, 2025|0 Comments

**WTMS Blog Today = What's up in Mortgage Today (PM) - 09/22/2025** Mortgage markets experienced continued pressure today as both mortgage-backed securities and Treasury bonds faced headwinds. The 10-year Treasury yield climbed to 4.149%, up [...]

What’s up in Mortgage Today (09/22/2025)

September 22nd, 2025|0 Comments

WTMS Blog Today = What's up in Mortgage Today (09/22/2025) Mortgage-backed securities (MBS) markets showed mixed activity today with a general softening observed in UMBS prices, reflecting cautious sentiment among investors. The UMBS 30-Year prices [...]

What’s up in Mortgage Today (PM) – 09/19/2025

September 19th, 2025|0 Comments

**WTMS Blog Today = What's up in Mortgage Today (PM) - 09/19/2025** Treasury yields climbed higher today as investors continued to digest Wednesday's Federal Reserve decision to cut interest rates by 50 basis points. The [...]

What’s up in Mortgage Today -AM- (09/19/2025)

September 19th, 2025|0 Comments

WTMS Blog Today = What's up in Mortgage Today (09/19/2025) Mortgage-backed securities (MBS) experienced a modest downturn today, with prices reflecting a slight decrease in demand, influenced primarily by rising yields in the 10-year Treasury [...]
Subscribe

Send me some brain food

Go to Top