**WTMS Blog Today = What’s up in Mortgage Today (AM) – 09/18/2026**
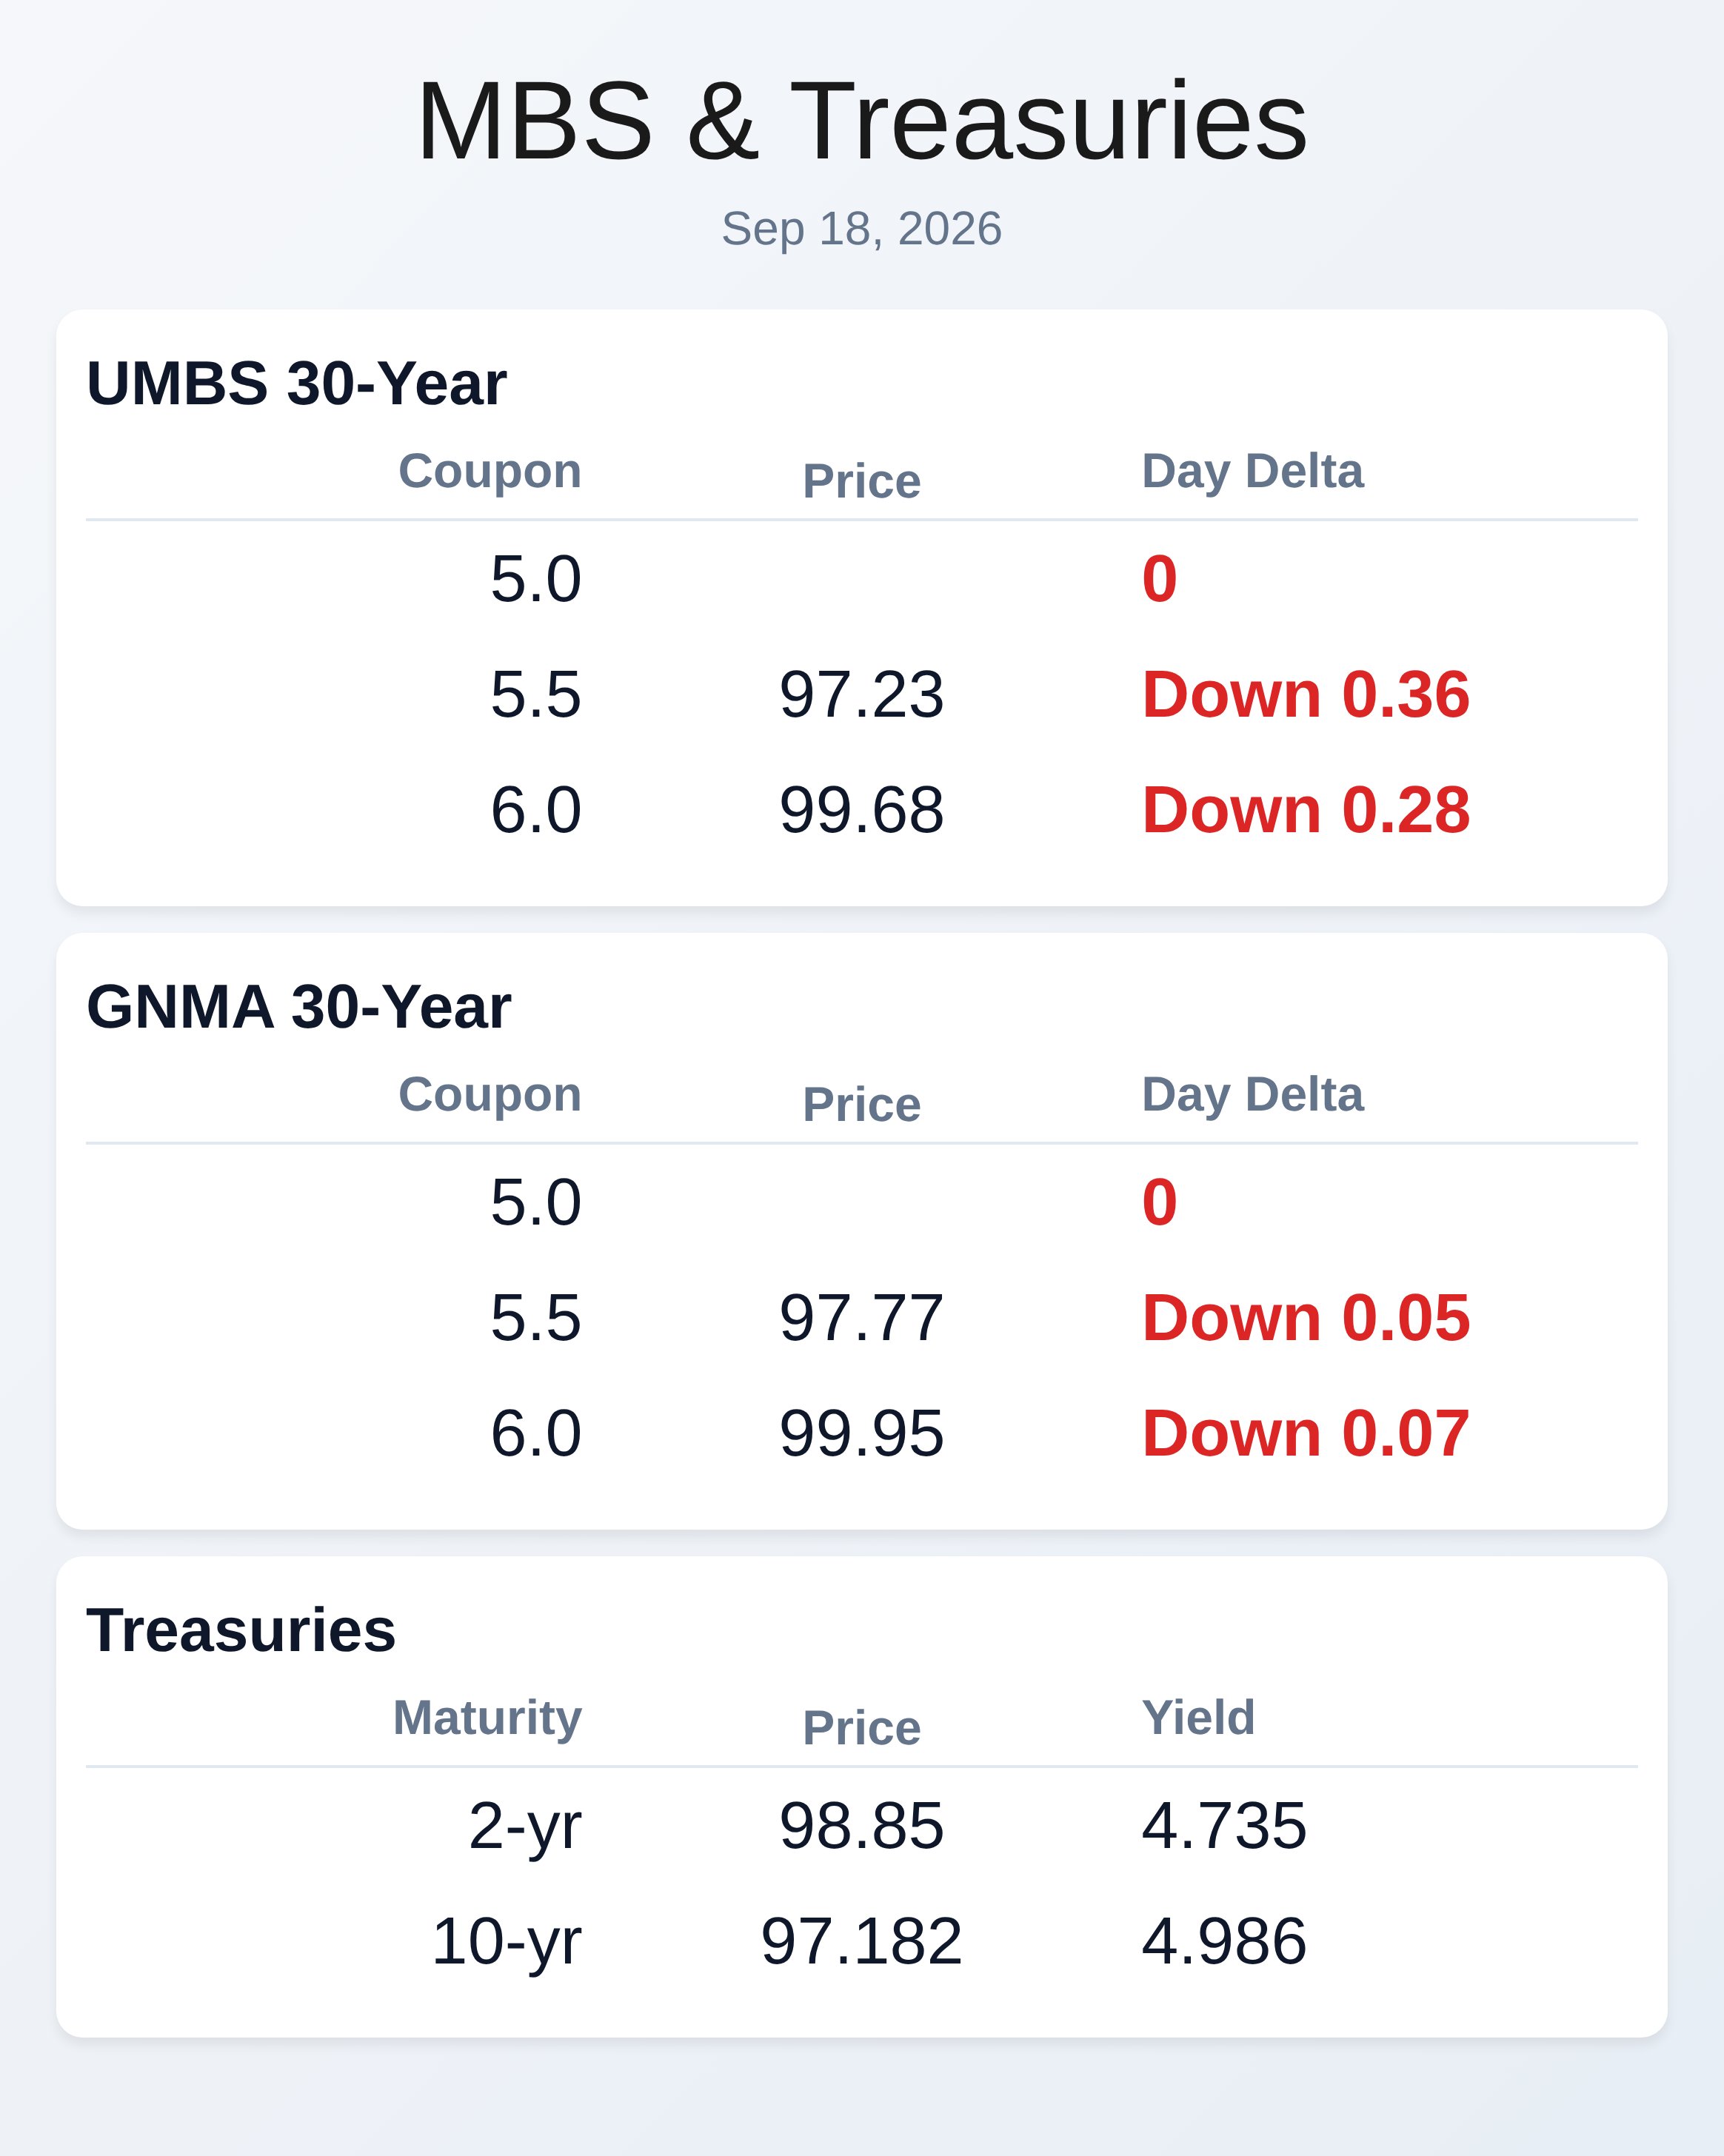
Bonds are selling off sharply this morning as the 10-year Treasury yield climbs to 4.986%, up 5.3 basis points, signaling renewed investor caution despite Thursday’s modest rally. UMBS 30-year coupons are down across the board—5.5s off 0.36, 6.0s down 0.28, and 6.5s sliding 0.20—while GNMA securities show more modest declines. The market is wrestling with competing narratives: the Fed’s hawkish 25-basis-point hike on Wednesday reasserted inflation-fighting credibility, but today’s weakness suggests investors are already pricing in multiple additional rate increases through 2027.
Oil prices remain under pressure, which typically supports bonds but has not reversed this morning’s slide. The key technical level to watch is 4.94% on the 10-year; a sustained move below that threshold would signal genuine momentum toward lower rates. Yesterday’s economic data painted a decidedly mixed picture that explains the current volatility.
Housing starts came in at 1.275 million versus 1.31 million forecast, while building permits printed at 1.394 million against expectations of 1.41 million, both suggesting residential construction is losing steam. Jobless claims crushed estimates at 196,000 versus 208,000 forecast, indicating the labor market remains unusually resilient despite high borrowing costs. The Philadelphia Fed Index held strong at 37.8, but prices paid jumped to 48.60, signaling that inflation pressures are re-emerging even as housing activity cools.
This disconnect—weak housing alongside tight labor and price growth—leaves the Fed with limited comfort on rate cuts, making the current yield environment sticky. The mortgage market faces structural headwinds from negative convexity as roughly 98% of 30-year borrowers now lack refinancing incentive. When rates rise, homeowners stay put, forcing MBS investors to hold longer-duration assets just as prices fall—the opposite problem they face during rallies.
This convexity drag is particularly acute in higher-coupon 5.5% mortgages, which are experiencing positive convexity as refinancing options vanish entirely. Originators should recognize that MBS are increasingly range-bound rather than trending in either direction, reducing the urgency for extreme positioning either way. The current market environment rewards lender discipline over aggressive directional calls.
The conventional conforming market continues to tighten eligibility standards and adjust loan pricing. FHFA Director Bill Pulte directed Fannie Mae to align servicing policies with Freddie Mac, allowing proactive borrower outreach for mortgage insurance cancellation based on current home values—a modest borrower relief measure. Fannie Mae expanded VantageScore 4.0 credit scoring from limited rollout to broad availability, giving approved lenders another underwriting option as the industry modernizes credit frameworks.
Fiscal concerns pose a headwind to longer-duration bonds, making a sustained move below 5% in the 30-year difficult without meaningful economic deterioration. With much of 2027’s expected tightening already priced in, bond yields may drift lower as investors reassess realistic rate-hike limits, though geopolitical energy pressures and AI-driven demand complicate inflation forecasts. Originators should prepare for range-bound rates and avoid over-extending capacity on the assumption of meaningful rate relief.
**Locking vs Floating**
Recent economic data shows housing construction losing momentum—starts and permits both missed estimates—while labor markets remain tight and price pressures are re-emerging. This mixed backdrop argues against aggressive floating positions, as the Fed retains hawkish optionality despite softer housing. Borrowers stretched on affordability have less margin for error, making lock discipline especially important to avoid future repurchase risk.
**Today’s Events**
August Building Permits: 1.394M (forecast 1.41M, previous 1.433M)
August Housing Starts: 1.275M (forecast 1.31M, previous 1.239M)
September 5 Continued Claims: 1.730M (forecast 1.78M, previous 1.774M)
September 12 Jobless Claims: 196K (forecast 208K, previous 206K)
September Philadelphia Fed Business Index: 37.8 (forecast 30.5, previous 47.4)
September Philadelphia Fed Prices Paid: 48.60 (previous 40.90)
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
| 5.5 | 97.23 | -0.36 |
| 6.0 | 99.68 | -0.28 |
| 5.5 | 97.77 | -0.05 |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |