**WTMS Blog Today = What’s up in Mortgage Today (PM) – 09/17/2026**
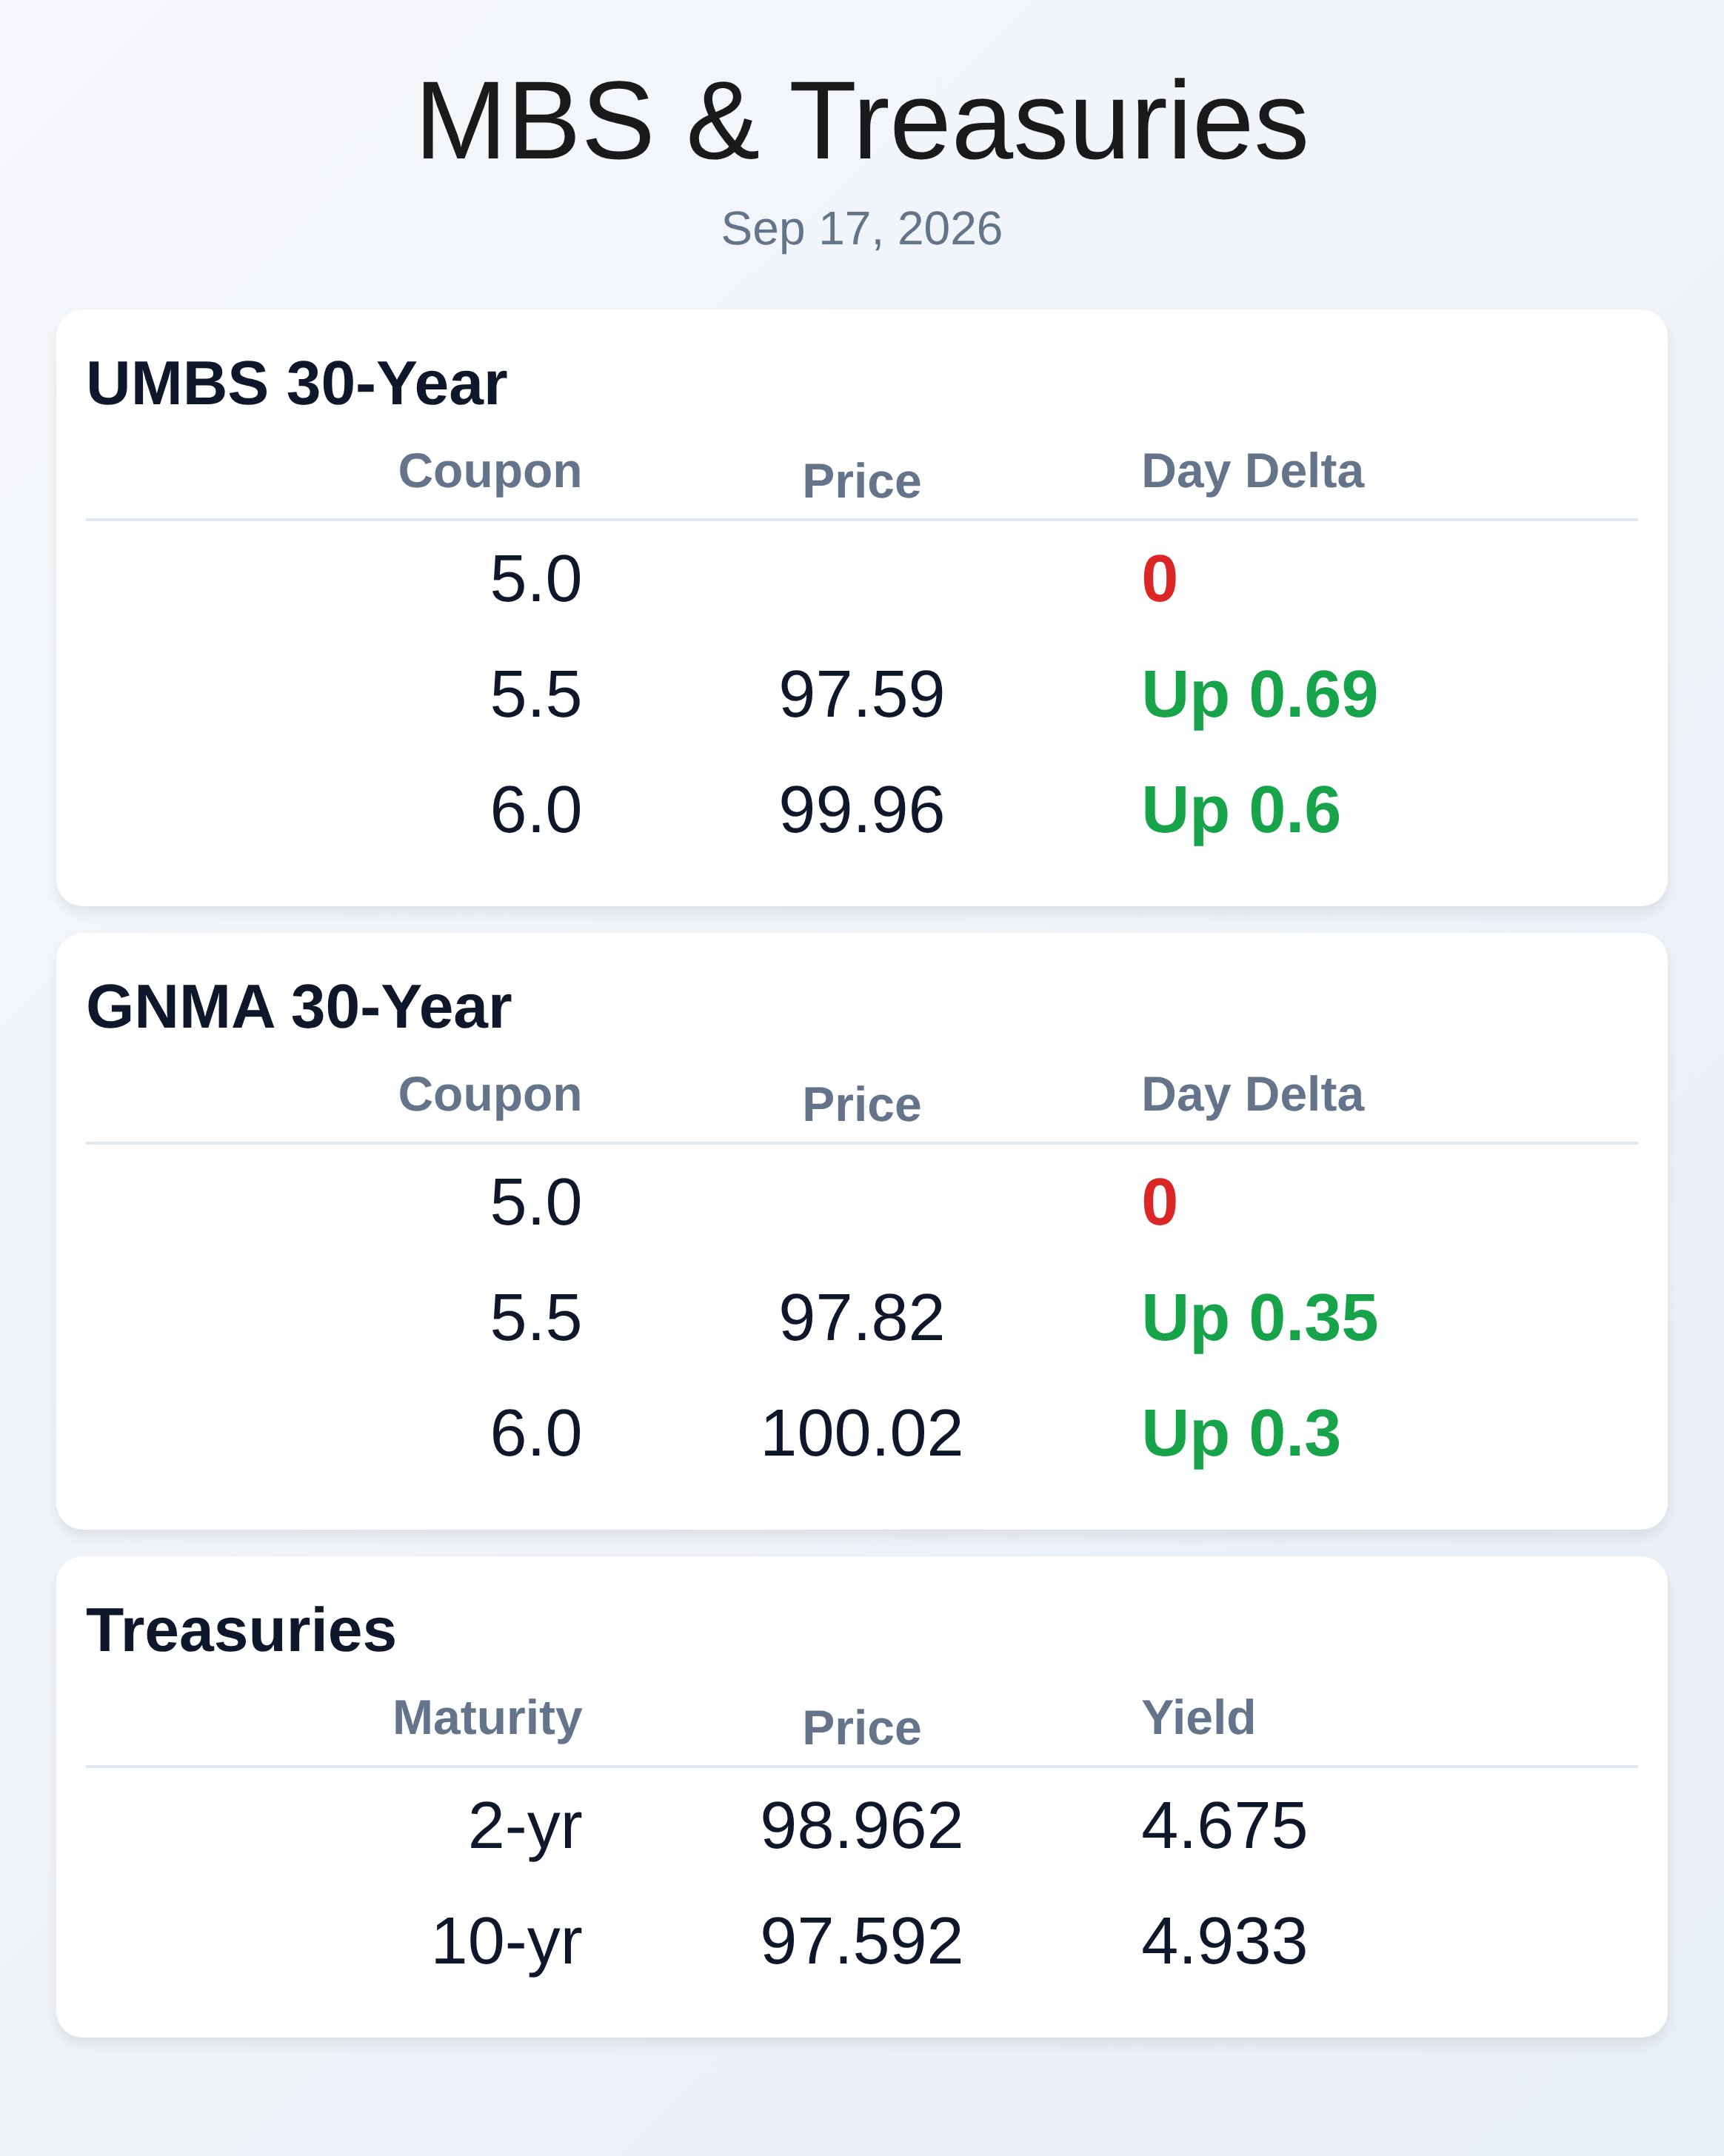
Mortgage rates caught a reprieve today as Treasury yields retreated following the Federal Reserve’s widely anticipated rate hike, with the 10-year yield sliding 8.5 basis points to settle near 4.93%. UMBS securities gained significant ground throughout the session, with the 5.5 coupon jumping 69 basis points to 97.59 and the 6.0 coupon rising 60 ticks to 99.96. The bond market’s positive reception suggests investors believe the Fed’s tightening cycle may be nearing its end, though officials signaled additional rate increases could still be on the table if inflation persists.
Economic data painted a mixed picture, with jobless claims coming in better than expected at 196K versus 208K forecast, while building permits and housing starts both lagged forecasts. The market’s challenge now revolves around whether this modest rally represents a true shift in momentum or merely profit-taking before the Fed’s next move. The disconnect between Fed policy and mortgage rates remains a critical lesson for originators to communicate.
While the Fed’s rate hike will push HELOC costs higher immediately—since those products typically track the prime rate—mortgage rates hardly budged because they forward-price Treasury expectations and long-term inflation outlooks. This fundamental difference allows loan officers to educate borrowers that a Fed hike does not automatically translate into higher mortgage rates, especially when Treasury yields are moving lower simultaneously. Homebuyers fixated on Fed announcements often miss the more relevant driver: 10-year Treasury yields.
Understanding this relationship helps originators cut through market noise and position themselves as credible advisors during volatile rate environments. The Philly Fed Business Index surged to 37.8 from the prior 47.4 reading, falling short of the 30.5 forecast and signaling cooling manufacturing activity. Continued jobless claims dropped to 1.73 million from 1.774 million previously, suggesting labor market resilience despite tightening monetary policy.
Building permits slipped to 1.394 million versus a 1.41 million forecast, while housing starts fell to 1.275 million compared to expectations of 1.31 million. Prices paid in the Philly region jumped to 48.6, marking persistent inflationary pressures even as economic growth moderates. These crosscurrents reinforce the volatility mortgage originators face: softening activity paired with sticky inflation creates an uncertain outlook for rate direction and borrower demand.
The critical technical level to watch remains the 4.94% threshold on 10-year yields, which serves as both a floor for optimistic traders and a ceiling for risk-averse investors. Breaking below this level cleanly would signal a meaningful shift toward lower rates, though energy prices remain a wildcard that could undermine sustained improvement. By day’s end, UMBS 6.5 coupons notched a 54-basis-point gain to 102.08, providing some relief for lenders holding in-the-money servicing portfolios.
GNMA securities lagged slightly, with the 6.5 coupon up just 4 basis points to 101.77, likely reflecting different prepayment assumptions. Treasury curve steepening—particularly the 2-year to 10-year spread—adds complexity for hedging strategies and lock management. Originators should recognize that today’s rally occurred on tighter credit spreads and improving risk sentiment, not on weakness in economic fundamentals.
The fact that mortgage rates held firm near 7% despite the Fed’s hike demonstrates the secondary market’s confidence in a pause cycle, but that conviction could evaporate if inflation data surprises to the upside. Lock strategies should remain disciplined; borrowers closing within 30 to 45 days face genuine rate risk if Treasury yields retest higher levels. Float positions benefit from the current softness, but the risk-reward profile deteriorates quickly once we move past September’s data calendar.
Loan officers must balance optimism about today’s moves with realistic hedging around next week’s economic releases. Subscribe free to WTMS Blog Today at WellThatMakesSense.com to stay ahead of mortgage market shifts and origination insights.
**Locking vs Floating**
The market’s narrative shifted today: the Fed’s rate hike did not automatically derail mortgage rates because those products are driven by Treasury yields and inflation expectations, not Fed policy directly.
Jobless claims beating forecasts reinforced the view that one more rate hike may already be priced in, removing some urgency around aggressive Fed tightening. The 4.94% ceiling on 10-year yields represents a psychological and technical pivot point—breaking below it cleanly would favor floaters and increase confidence in lower future rates. Conversely, if yields retest higher after better-than-expected data next week, locks become increasingly attractive relative to floating risk.
**Today’s Events**
Building Permits (Aug): 1.394M vs 1.41M forecast, 1.433M previous
Housing Starts (Aug): 1.275M vs 1.31M forecast, 1.239M previous
Jobless Claims (Sep/12): 196K vs 208K forecast, 206K previous
Continued Claims (Sep/05): 1.73M vs 1.78M forecast, 1.774M previous
Philly Fed Business Index (Sep): 37.8 vs 30.5 forecast, 47.4 previous
Philly Fed Prices Paid (Sep): 48.60 vs forecast not available, 40.90 previous
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
**GNMA 30yr**
| Coupon | Price | Intra-Day Change |
|—:|—:|—:|
| 5.5 | 97.82 | 0.35 |
| 6.0 | 100.02 | 0.3 |
| 6.5 | 101.77 | 0.04 |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
|—|—:|—:|—:|
| 2yr | 4.675 | 98.962 | -0.059 |
| 3yr | 4.742 | 98.984 | -0.078 |
| 5yr | 4.787 | 98.185 | -0.087 |
| 7yr | 4.858 | 97.9 | -0.088 |
| 10yr | 4.933 | 97.592 | -0.086 |
| 30yr | 5.289 | 97.548 | -0.07 |