**WTMS Blog Today = What’s up in Mortgage Today (AM) – 09/16/2026**
The Federal Reserve faces the market’s spotlight this afternoon as traders price in a 90%+ probability of the first rate hike since 2023, a move widely expected to lift borrowing costs across mortgages and refinance activity. MBA applications fell 4.1% last week as rising energy prices and Treasury yields pushed the 10-year yield toward 5%, while refinance activity plummeted 9% week-over-week and remains down 65% year-over-year. August retail sales beat expectations at 1.2% versus a 0.8% forecast, demonstrating consumer resilience despite inflation concerns that sparked this rate-hike cycle.
Import prices also surprised upward at 0.7% monthly, reinforcing inflation pressures that justify the Fed’s tightening stance. The tone of Fed Chair Kevin Warsh’s press conference will matter more than the rate decision itself, as any hawkish messaging could trigger another leg higher in yields. Agency MBS and Treasury prices found slight relief early Wednesday as crude oil dipped below $108 per barrel and traders prepared for the central bank’s announcement.
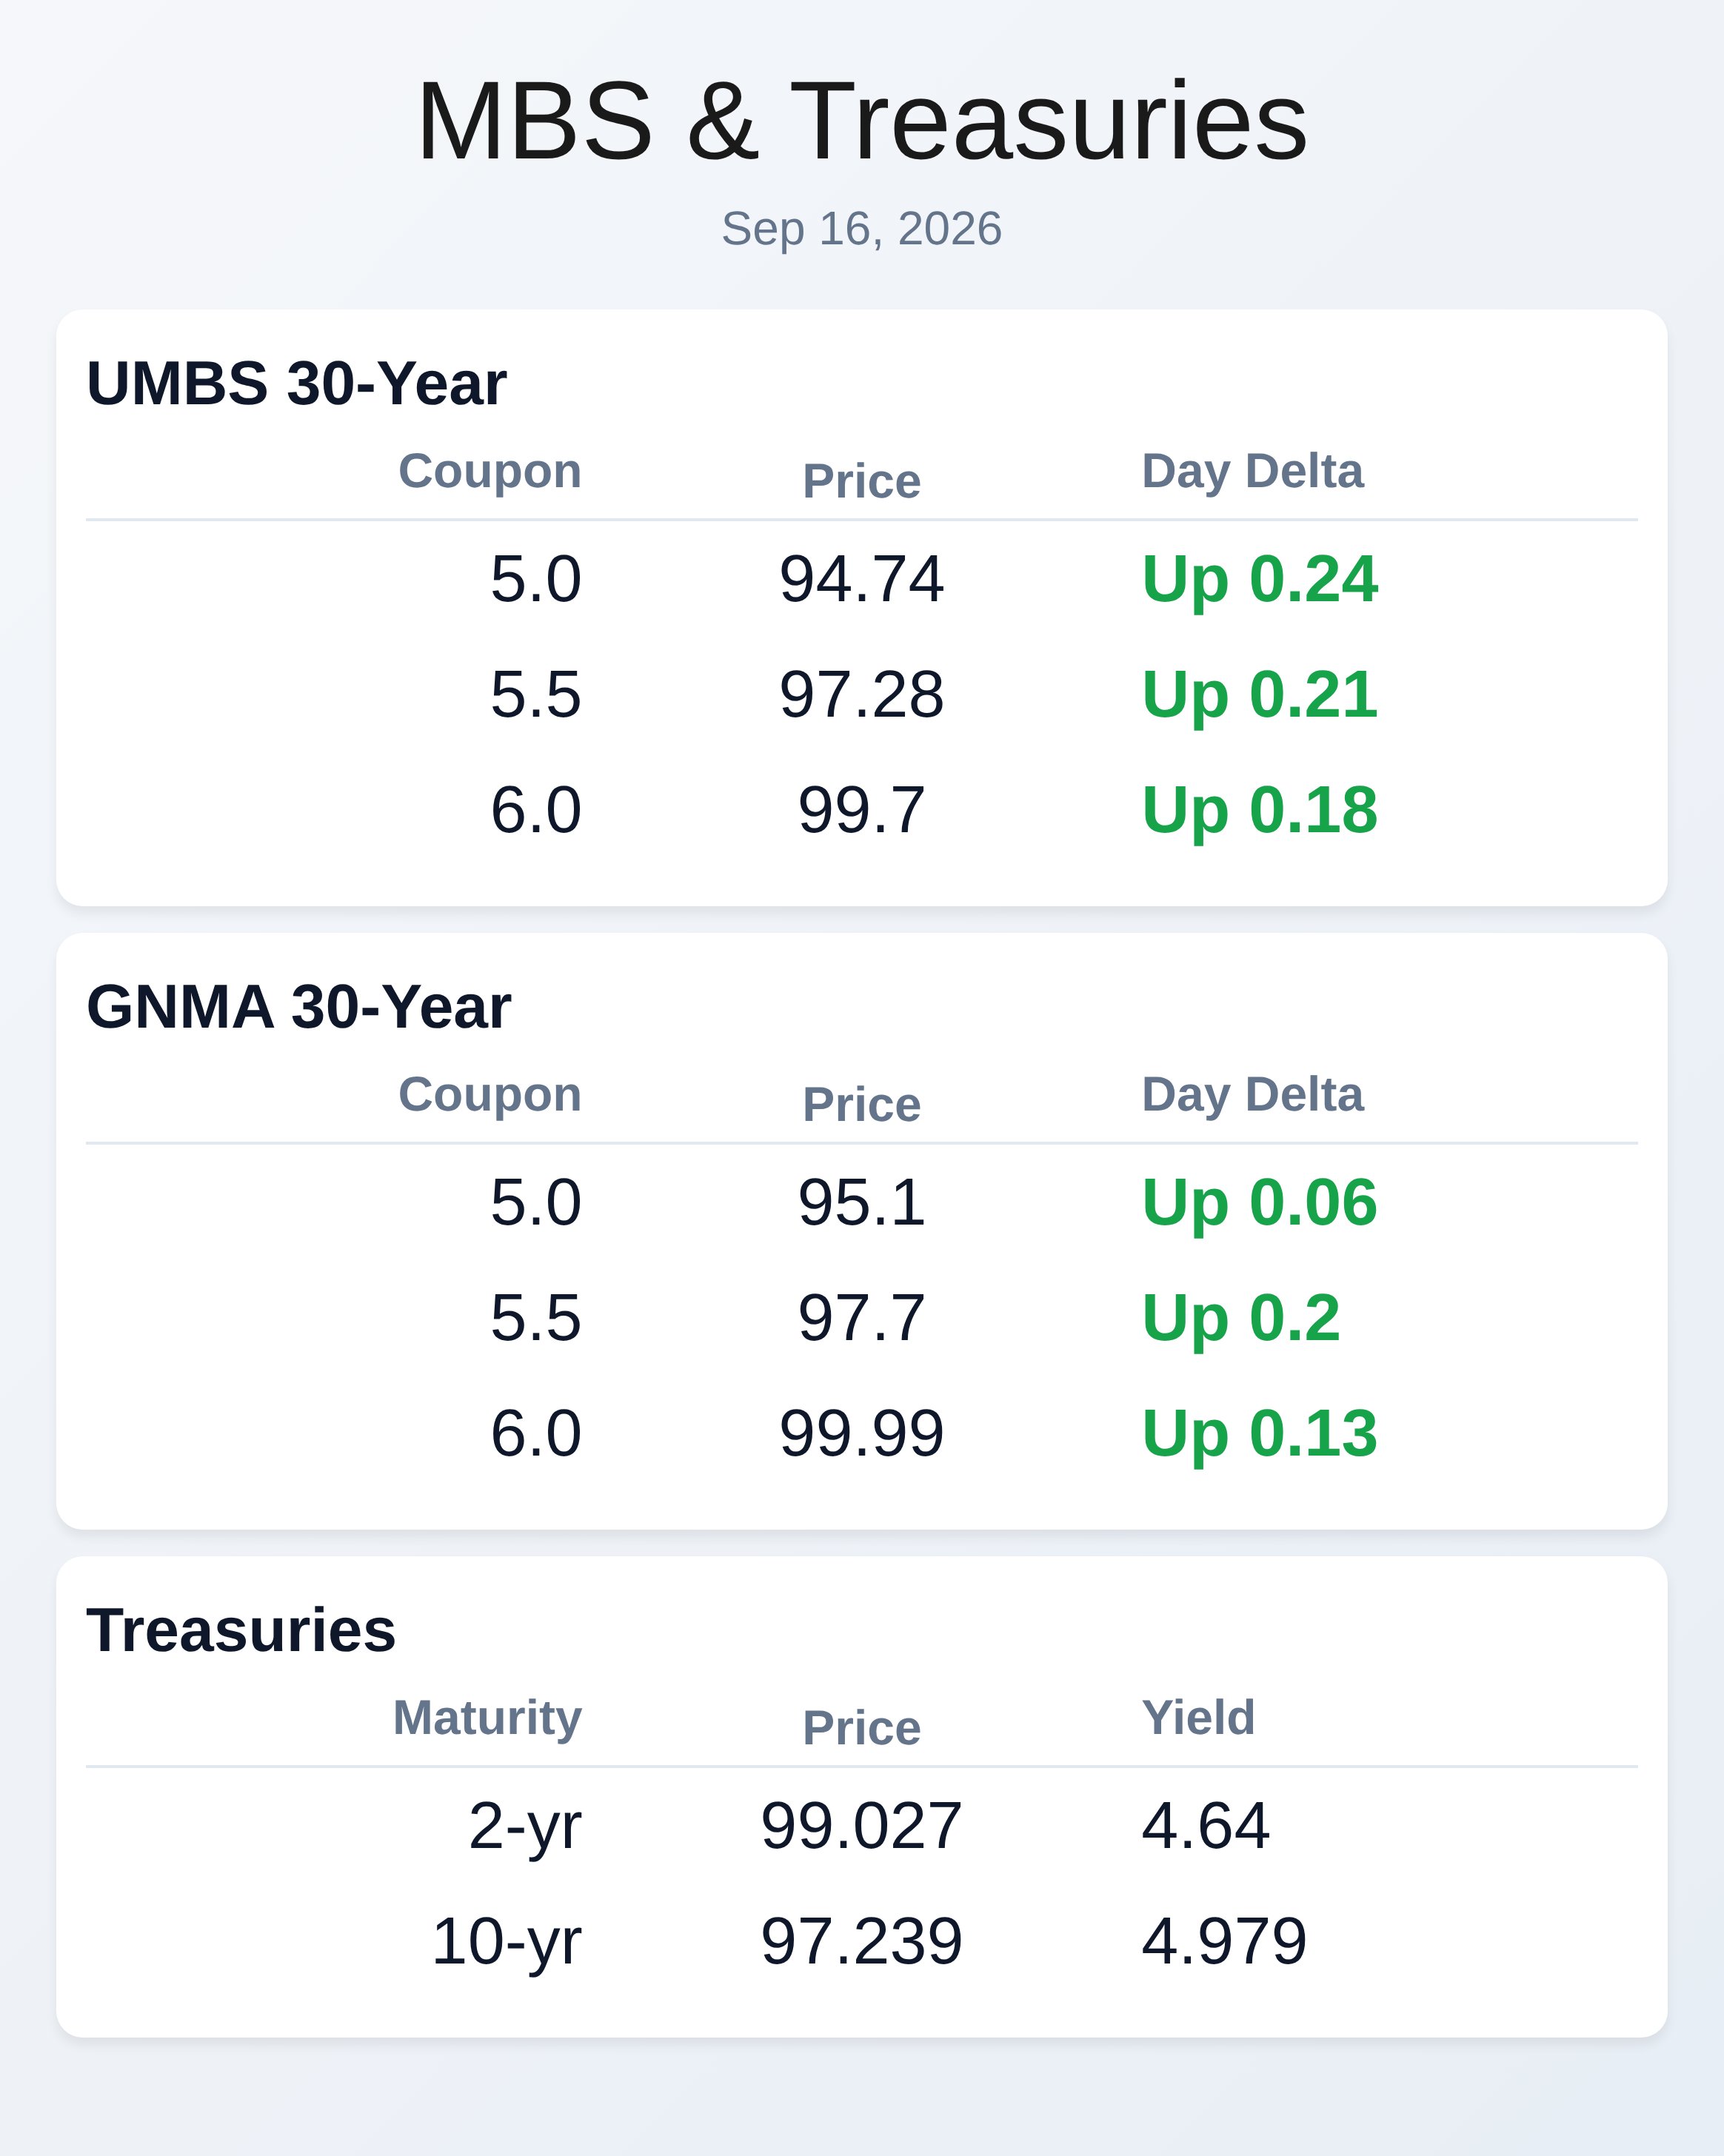
UMBS 30-year coupons improved modestly, with the 6.0 coupon closing at 99.70 (up 0.18), while the 10-year Treasury yield moved to 4.97% from 4.98% overnight. Foreign demand for longer-duration Treasuries remains soft, evidenced by the weak 20-year Treasury reopening that required a 5.42% yield to clear, nearly 60 basis points higher than the prior auction. The dollar pared losses and equities positioned for a morning rally, though sentiment remains fragile.
Warsh’s communications strategy—whether he signals further tightening beyond today or commits to a data-dependent path—will determine bond market direction heading into year-end. Purchase mortgage applications declined 1% seasonally adjusted and sit 19% below last year’s levels, underscoring persistent headwinds from higher rates and compressed affordability that shows no sign of easing. Refinance volume dropped even more sharply, signaling that borrowers with existing mortgages have largely locked in rates and view opportunities for refi as limited.
Applications data released this morning revealed the human cost of Fed policy: stretched borrowers with thinner margins for error in their loan files. Each rate move ripples through origination pipelines as would-be homebuyers delay purchase decisions. Disaster declarations from FEMA (Indiana tornadoes and Hawaii earthquakes) add additional operational complexity for lenders and servicers in affected regions.
The economic calendar this afternoon piles on the Fed’s evidence: July Business Inventories, September NAHB Housing Market Index, and crude oil inventory levels all arrive before the 2 p.m. rate decision. These data points collectively paint a picture of an economy still firing on cylinders—strong consumption, robust job markets, and pricing power in the supply chain.
Treasury yields have already climbed to multiyear highs on inflation concerns, leaving the bond market little room to rally if Warsh disappoints hawks. The combination of above-target inflation, surging energy costs, healthy employment, and solid GDP growth leaves policymakers with minimal political cover to hold steady. Mortgage originators now face the reality that rate lock periods could face pressure if Fed communication signals further tightening down the road.
Private equity continues reshaping industry peripherals beyond just mortgage lending and servicers. Genstar Capital and Aksia announced a strategic growth investment in Richey May, a top 50 U.S. accounting and advisory firm, signaling continued M&A appetite among financial sponsors.
The capital will fund Richey May’s organic growth and acquisition strategy as it builds a national platform, though founder ownership remains materially intact. Tech transitions dominate vendor conversations as credit unions and lenders evaluate platform upgrades ahead of the November 2 Uniform Appraisal Dataset (UAD) 3.6 deadline. Floify emphasized the need for vendors to shoulder implementation heavy lifting and maintain post-go-live support, a lesson learned from prior mortgage system conversions.
Jumbo lending tools like Symmetry’s piggyback HELOC structure gain traction as borrowers navigate affordability challenges with bridge alternatives. Subscribe free at **WellThatMakesSense.com** for daily mortgage market updates and origination insights.
**Locking vs Floating**
Markets face elevated uncertainty heading into the Fed announcement, with oil prices and inflation data creating volatility in both directions.
Technical support emerged in bond markets today, yet momentum remains contested and could shift dramatically on Warsh’s guidance. Originators should prepare for continued rate volatility through the weekend as traders digest the policy decision and guidance on future tightening. Any signal of additional hikes beyond today will pressure purchase and refi demand further.
Lock recommendations depend on pipeline composition, but defensive positioning seems warranted until a clearer reversal in bond yields takes hold.
**Today’s Events**
Import prices (August): 0.7% vs. 0.4% forecast, -0.4% prior
Retail sales (August): 1.2% vs.
0.8% forecast, -0.6% prior
Retail sales control group (August): 1.4% vs. 0.4% forecast, -0.4% prior
Headline CPI (August): 3.4% vs. 3.4% forecast, 3.4% prior
MBA mortgage applications: Down 4.1% week-over-week; refinance down 9% w/w, -65% year-over-year; purchase applications down 1% seasonally adjusted, -19% year-over-year
July business inventories (afternoon)
September NAHB Housing Market Index (afternoon)
Weekly crude oil inventories (afternoon)
September FOMC decision and press conference (2 p.m.
EDT)
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
| 2yr | 4.64 | 99.027 | -0.023 |
| 3yr | 4.736 | 99.001 | -0.028 |
| 5yr | 4.804 | 98.114 | -0.024 |
| 7yr | 4.889 | 97.72 | -0.020 |
| 10yr | 4.979 | 97.239 | -0.023 |
| 30yr | 5.351 | 96.641 | -0.017 |