**WTMS Blog Today = What’s up in Mortgage Today (AM) – 11/19/2026**
Movement Mortgage’s $1.2 million arbitration win signals lenders are cracking down hard on loan officers who break early commitments. The company will enforce a ruling requiring two former LOs to repay signing bonuses after they departed roughly a year into three-year employment agreements, with accumulated interest now pushing the total obligation higher. This outcome carries major implications: lenders nationwide are increasingly treating signing bonuses as conditional advances on wages rather than one-time gifts, and they are prepared to litigate to recover every dollar when LOs leave before their contracts end.
For mortgage sellers and staffing brokers, this sets a precedent that employment protections are strengthening in lenders’ favor. Homebuilder sentiment has collapsed to its worst level since April 2012, falling four points to an index reading of 25 as affordability pressures and buyer hesitation grind through the market. Nearly half of builders cut prices this month—the highest share since the COVID-19 pandemic—while 68 percent offered sales incentives to move inventory.
Buyer traffic plummeted to just 16 on the index, its lowest outside the pandemic onset, underscoring how completely elevated mortgage rates above 7 percent have demolished demand. For mortgage originators, this means purchase lending volume will remain under pressure heading into the final six weeks of 2026 as builders themselves retreat from new starts. Mortgage applications fell 2.3 percent for the week as the 30-year fixed rate climbed back to 7.35 percent, its highest in three weeks, following hot inflation data and renewed Fed hawkish commentary.
Purchase applications dropped 3 percent week-over-week and sit 18 percent below year-ago levels, while refinance apps slid 2 percent and trail last year by 54 percent. FHA refis bucked the trend, rising nearly 7 percent, as the FHA rate sat about 30 basis points lower than conforming rates and lured borrowers seeking relief. For lenders watching pipeline capacity shrink, this week’s rate spike erased most of October’s hard-won gains.
Fed Governor Christopher Waller pushed for consideration of a 50-basis point rate hike in December, arguing that last three months of inflation data running near 3.5 percent annually warrants more aggressive action than the market consensus of quarter-point increases. His stance conflicts with New York Fed President John Williams, who dismissed the need for outsized hikes and characterized the situation as requiring measured policy, not drama. October’s FOMC minutes released this week show nearly all committee members favor further tightening, though debate persists over the pace.
For mortgage sellers, the December Fed meeting now carries binary risk: even a 25-basis point hike combined with persistent inflation signals an extended period of elevated rates. Independent mortgage banks reported devastating third-quarter results, posting an average pre-tax net production loss of $30 per loan versus a $973 profit in the second quarter, marking the lowest third-quarter performance since 2023. Per-loan production revenues fell to $11,585 while costs surged to $11,615, squeezing margins to virtually nothing, and only 44 percent of IMBs would have remained profitable without servicing income carrying the day.
MBA noted that staff reductions and cost-cutting initiatives will likely accelerate through the remainder of 2026 and into the first quarter of 2027. This profitability free-fall reflects how the summer rate spike reduced volume and magnified fixed production expenses across the entire industry. VantageScore 4.0 adoption continues to lag despite over 170 lenders now pulling the score on Agency loans, as only about 8 percent of conventional loans actually used it for pricing decisions in October.
Rocket and United Wholesale Mortgage accounted for 95 percent of loans priced with VantageScore 4.0, leaving the remaining 168 lenders still anchored to legacy FICO scores despite the technical ability to switch. VantageScore 4.0 scores average roughly 43 points higher than FICO on the same borrowers, yet the operational complexity of repricing engines and investor guidelines keeps most lenders locked in legacy systems. For technology-focused mortgage sellers, this reveals how difficult true score migration remains even when credit bureaus make the data available.
**Locking vs Floating**
No lock-versus-float-specific recommendations emerged in this week’s source materials.
**Today’s Events**
Weekly Initial Claims: 203k (released Thursday 7:30 AM EST; forecast range 190k–205k; prior week revised to 202k)
Continuing Claims: 1.763 million (released Thursday 7:30 AM EST; prior week)
October Housing Starts: 1,309k annualized (released Thursday 8:30 AM EST; forecast 1,250k; prior month 1,191k)
October Building Permits: 1,295k annualized (released Thursday 8:30 AM EST; forecast 1,375k; prior month 1,398k)
November NAHB Housing Market Index: 25 (released Wednesday; prior month 29)
October Retail Sales: +0.2% month-over-month (released Tuesday; forecast +0.1%; prior month +0.8%)
October Industrial Production and Capacity Utilization (released Tuesday; market pending)
September Business Inventories (released Tuesday; market pending)
FOMC Minutes from October meeting (released Wednesday 2:00 PM EST)
October Pending Home Sales (released Wednesday; market pending)
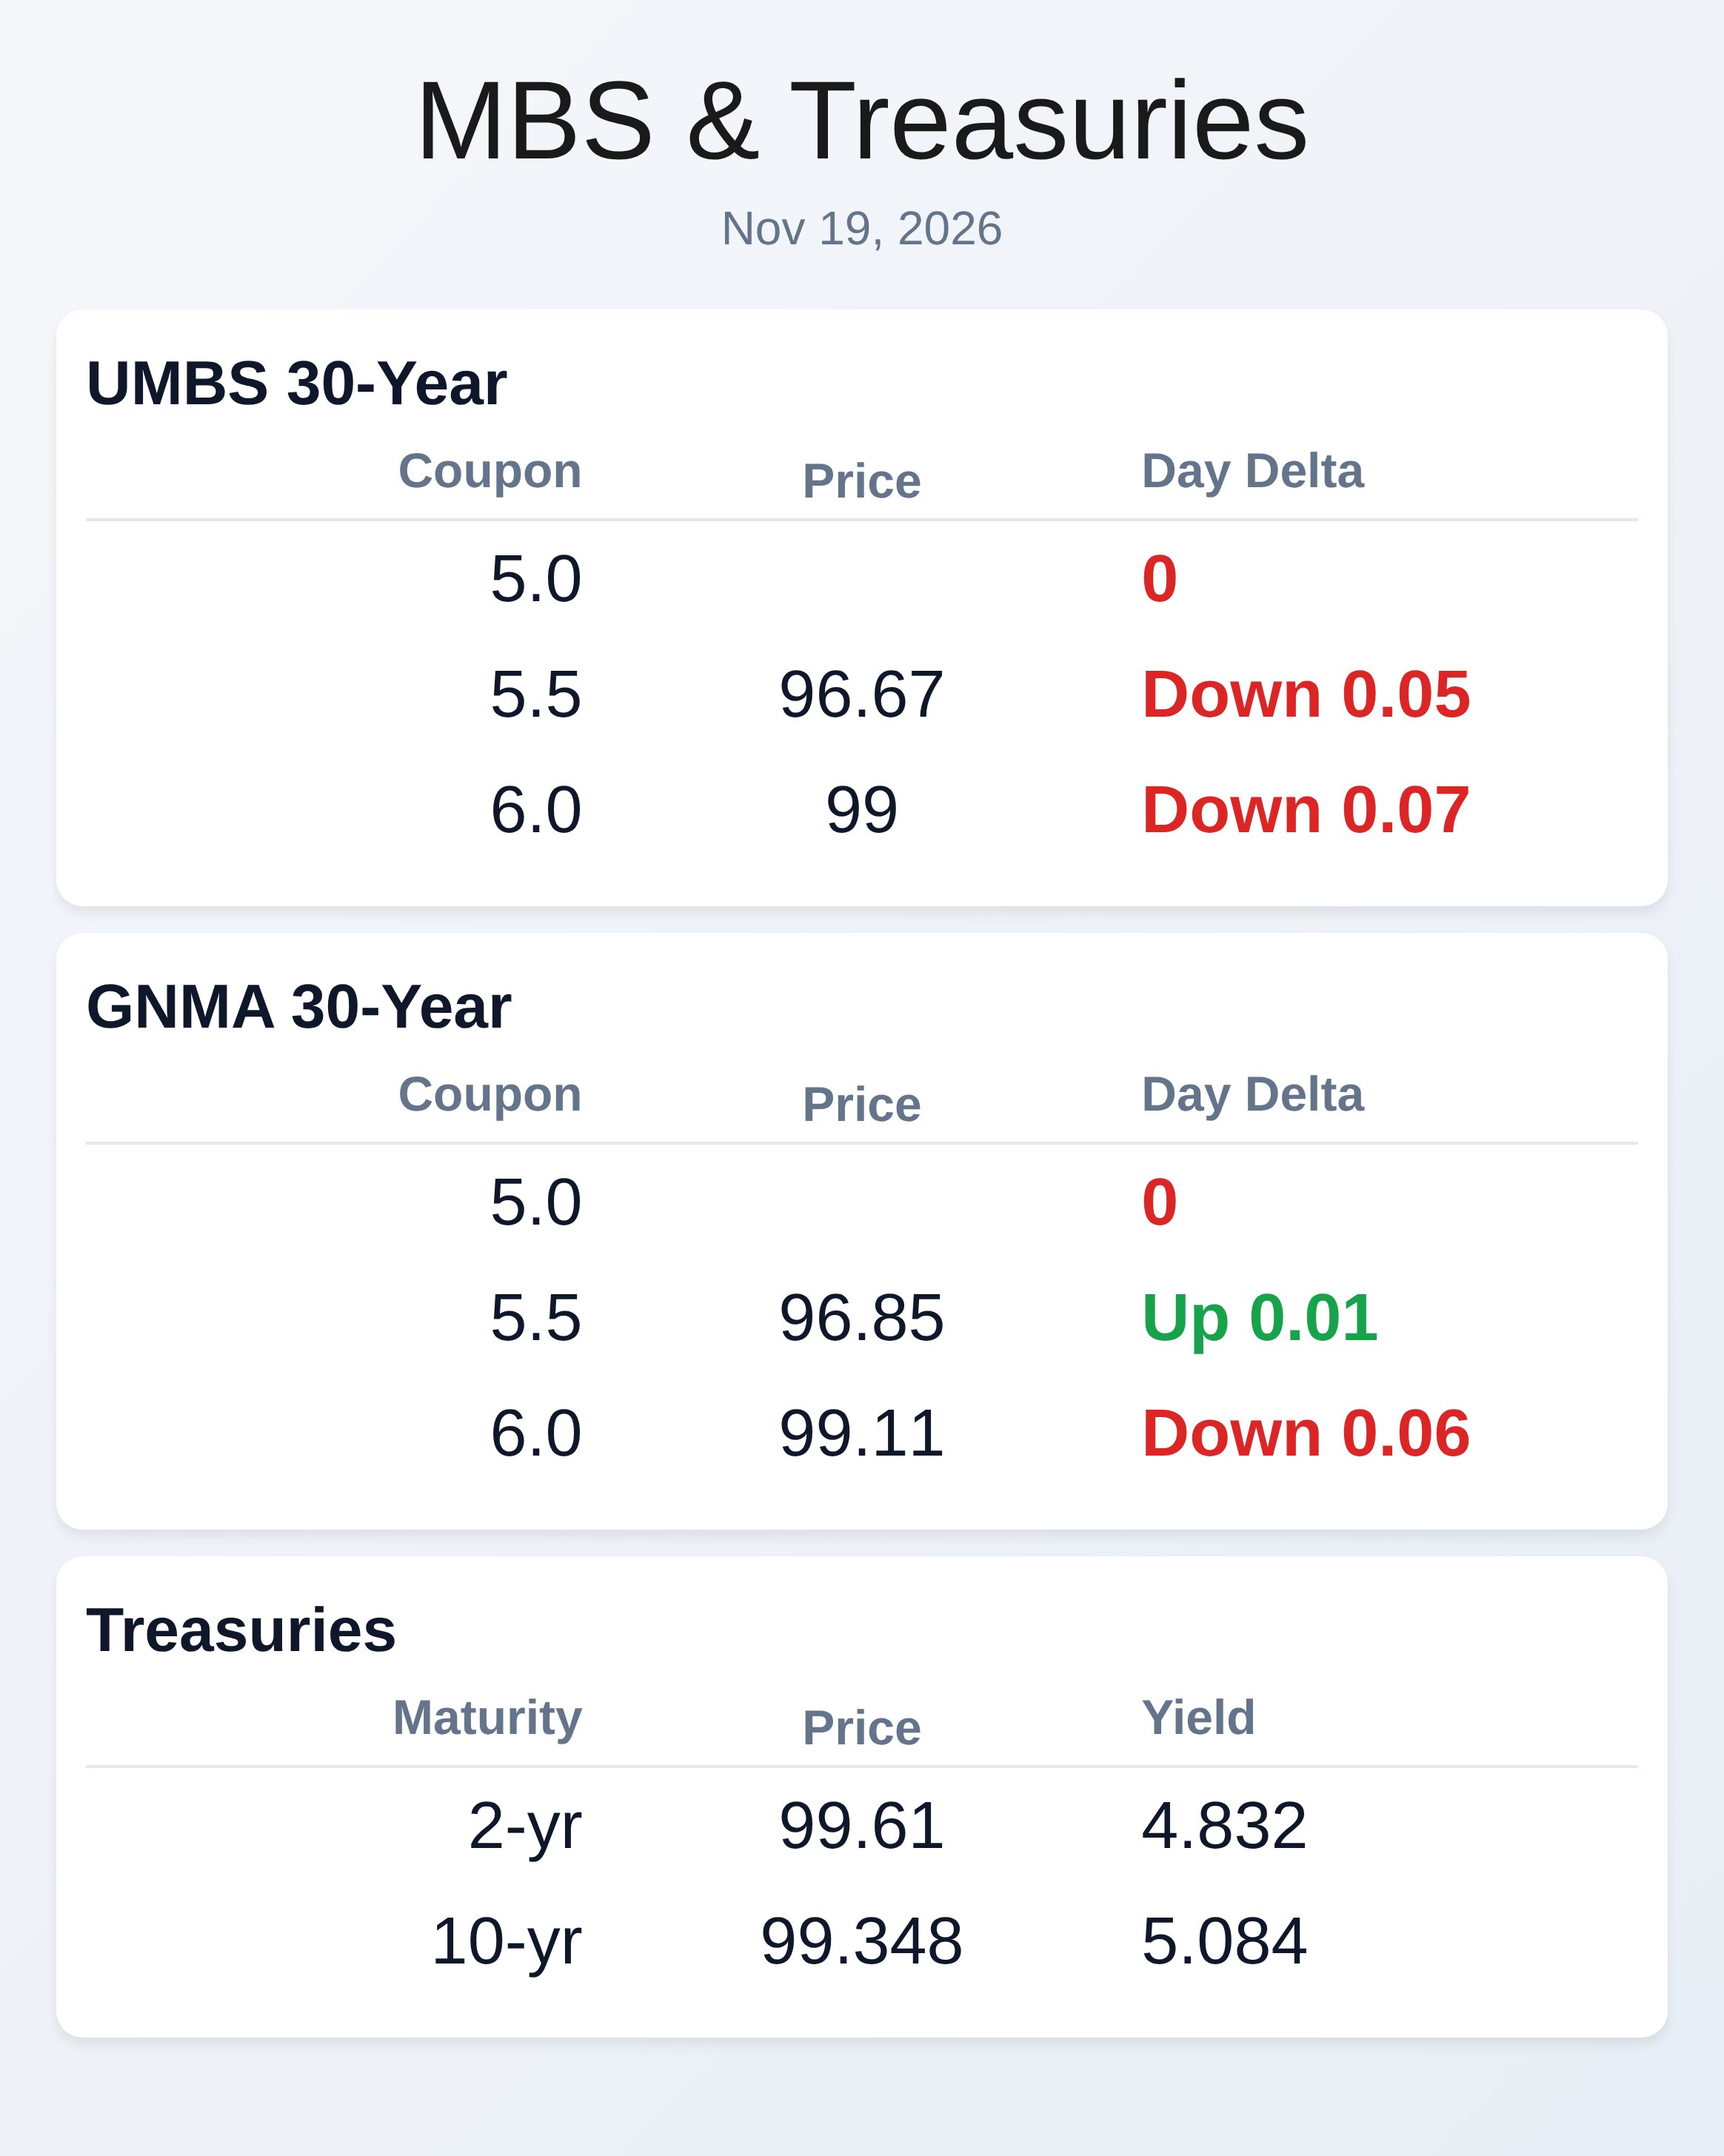
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |