**WTMS Blog Today = What’s up in Mortgage Today (AM) – 09/21/2026**
The Federal Reserve’s hawkish quarter-point rate hike to 3.75–4.00% last week sent shockwaves through Treasury markets, pushing the 10-year yield to nearly 5% multiple times as inflation fears resurface. The benchmark 10-year closed Friday at 5.00% and opened today at 4.95%, with traders caught between two competing forces: renewed confidence in Fed credibility versus persistent fiscal concerns demanding higher real yields. Agency MBS prices responded positively in pre-market trading, up 0.125–0.250 from Friday’s close, though mortgage spreads remain tactically cheap on a spread basis.
Buyers remain hesitant to add risk until Treasury yields establish a stable trading range. The choppy environment also complicated mortgage hedging, with the deeply special FNCL 6.5 roll straining extension and financing costs for pipeline hedgers. Economic data this morning delivered mixed signals for mortgage market momentum.
Jobless claims came in better than expected at 196K versus 208K forecast, while continued claims fell to 1.730M from 1.774M previously. However, housing starts declined to 1.275M in August versus 1.31M expected, and building permits fell short at 1.394M versus 1.41M forecast. The Philly Fed Business Index surprised to the upside at 37.8 versus 30.5 expected, but Philly Fed Prices Paid accelerated to 48.60, signaling persistent pricing pressure in manufacturing.
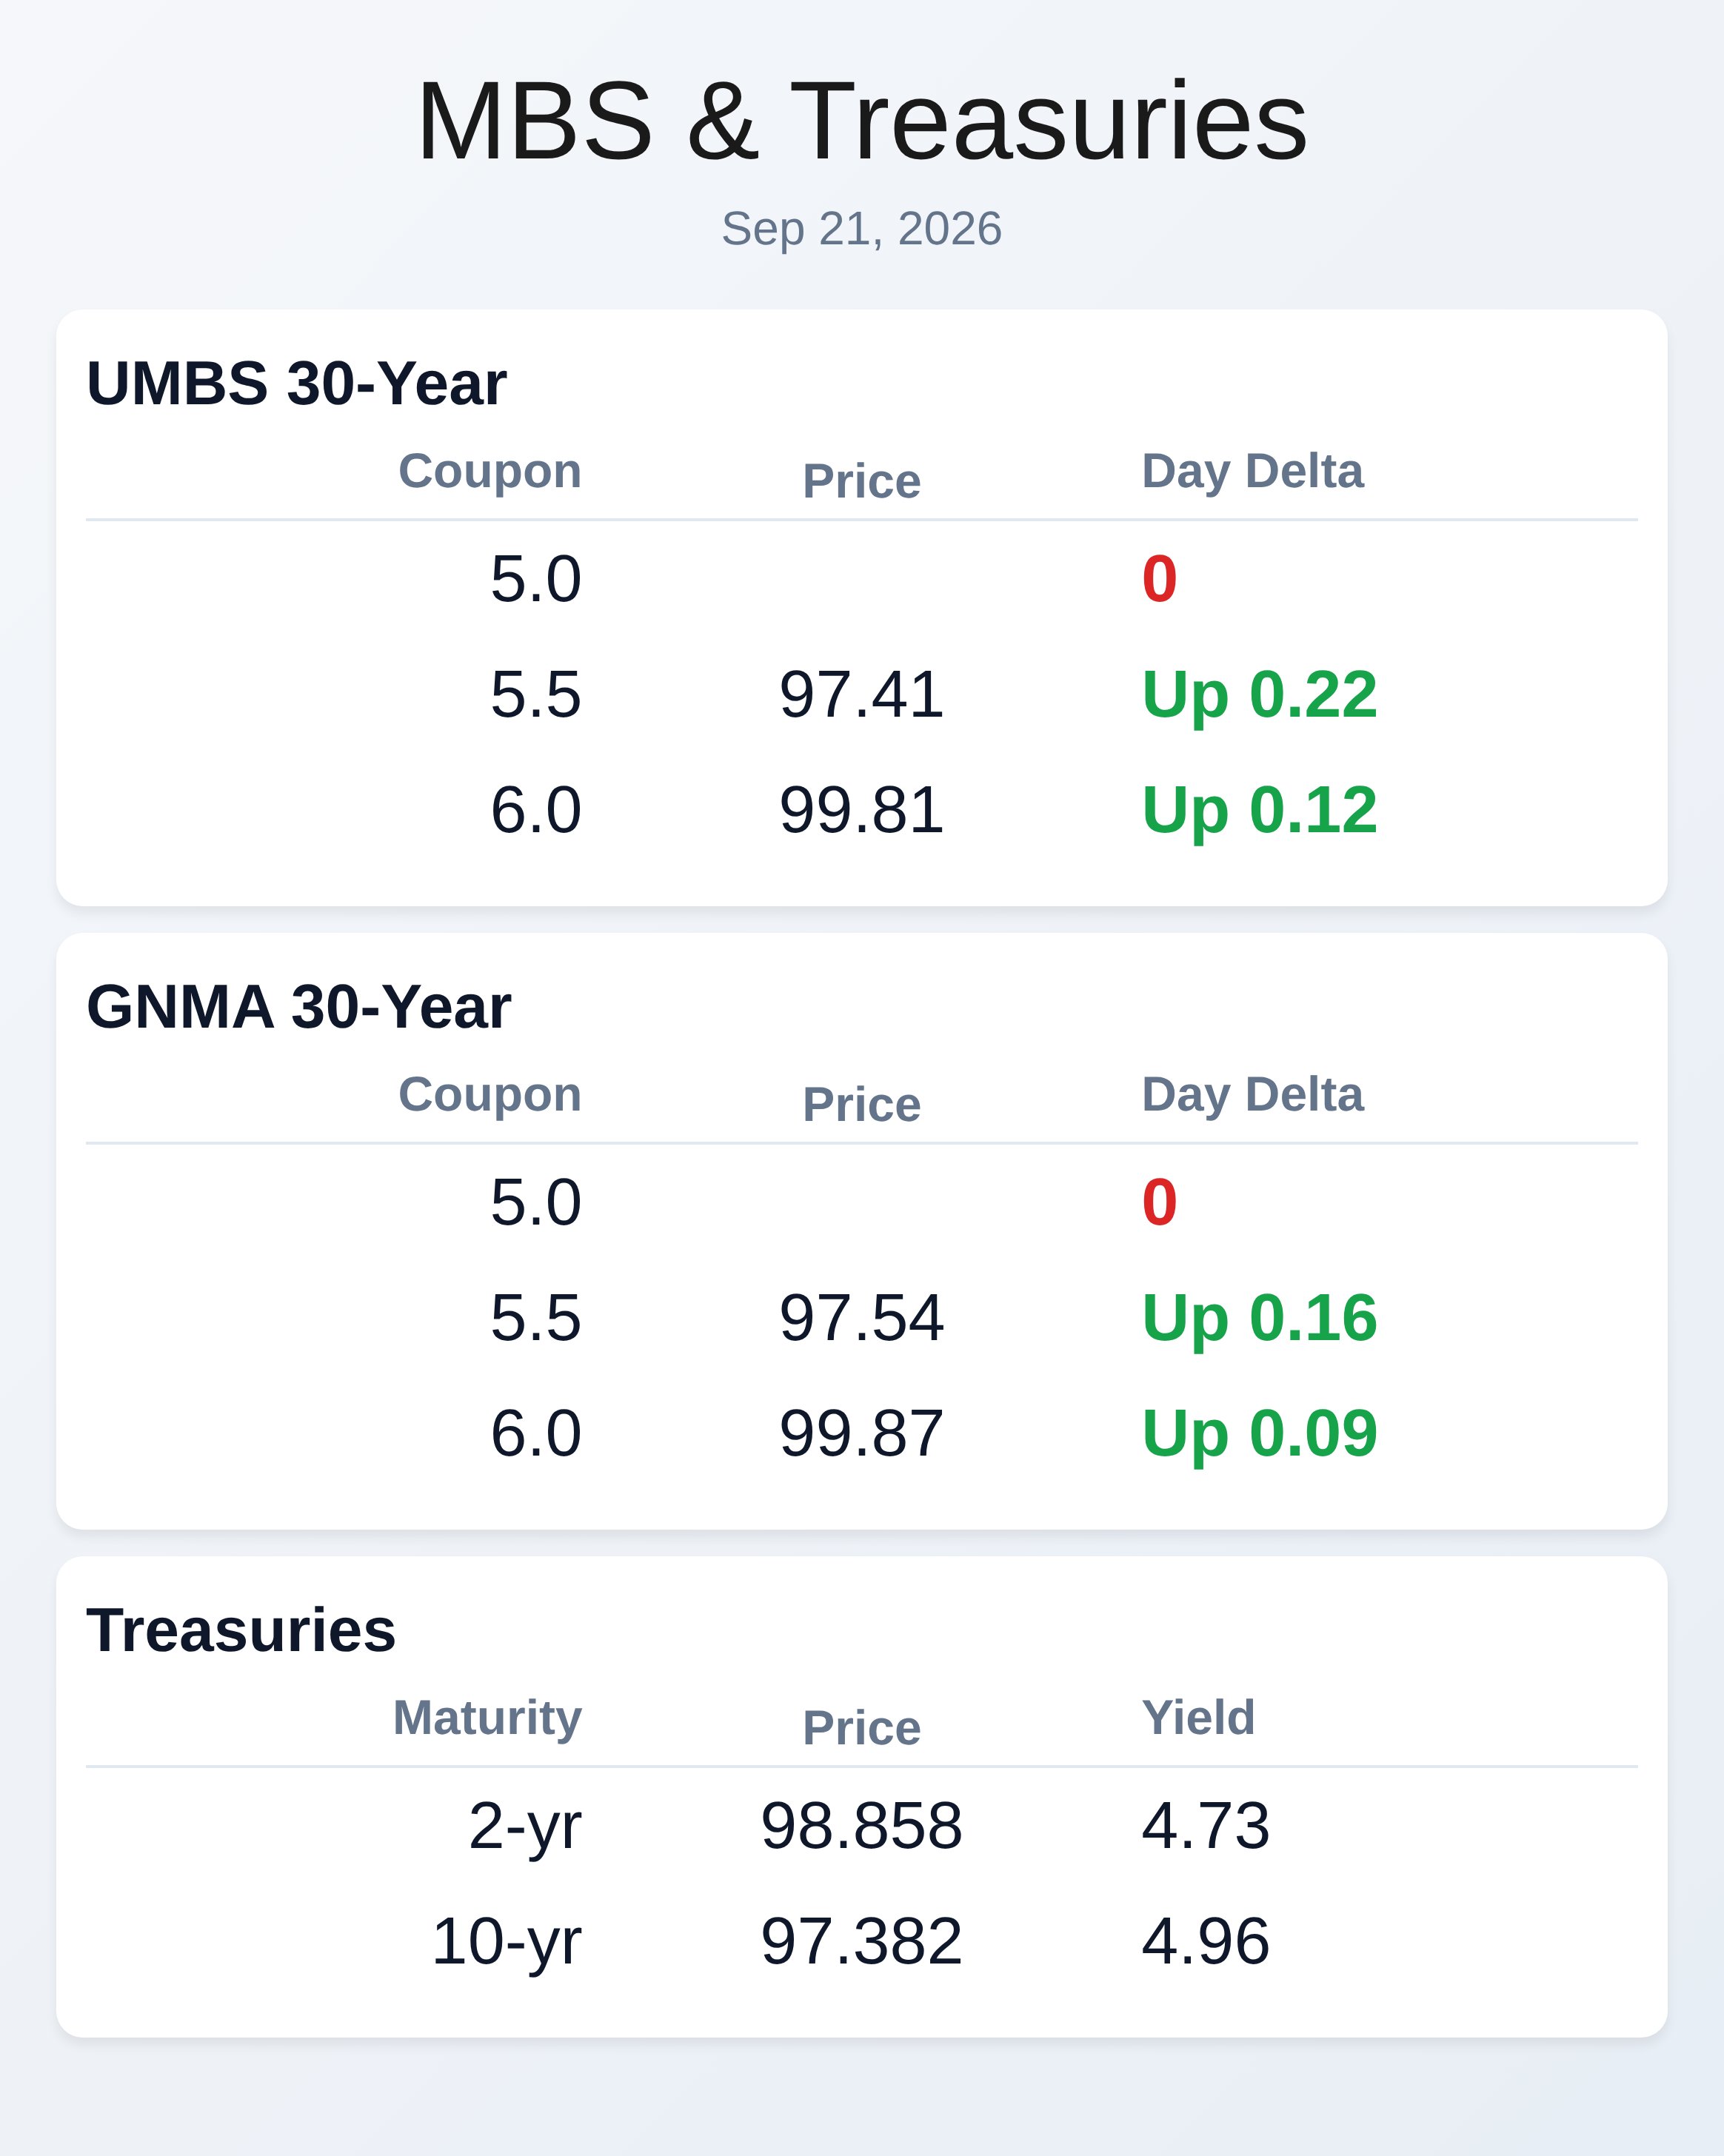
These data points reinforce that growth remains resilient even as inflation concerns persist, keeping the Fed’s rate-hiking bias intact. UMBS 30-year coupon prices showed modest intra-day gains this morning across the curve. The 5.5 coupon gained 0.22 points to 97.41, the 6.0 coupon rose 0.12 to 99.81, and the 6.5 coupon added 0.11 to 102.05.
GNMA 30-year coupons performed similarly, with the 5.5 coupon at 97.54 (up 0.16), the 6.0 at 99.87 (up 0.09), and the 6.5 at 101.76 (up 0.16). The modest gains suggest buyers are testing the market after Friday’s heavy selling, but conviction remains limited until yield stability improves. These modest moves reflect the cautious tone across Agency MBS as traders await clearer Treasury direction.
Multiple conforming loan limit increases effective immediately or this week signal lender confidence despite rate volatility. Pennymac raised its conforming limit to $850,000, the highest announced increase, ahead of FHFA’s official 2027 announcement expected in December. UWM, Newrez, Loan Stream, and AmeriHome all announced increases, with limits ranging from $845,000 to $850,000 for mainland properties.
These expansions allow lenders to compete more aggressively for higher-balance loans that would otherwise fall into non-Agency territory. The coordinated moves suggest lenders are preparing inventory strategies for a tighter conventional landscape. Industry consolidation is reshaping borrower relationships and recapture strategy as lenders compete on technology innovation and servicing capabilities.
This week’s ACUMA conference in Las Vegas attracts 800 registrants, with AI and automation as central themes across vendor booths and lender meetings. Spring EQ, mLoop, Balerion, and other platforms are emphasizing speed (top performers closing home equity loans in under 10 days) and seamless borrower experience through white-labeling and automated verification. The competitive pressure to reduce friction and improve processing speeds is accelerating technology adoption across the mortgage ecosystem.
Pipeline hedging and mortgage volatility remain key headwinds as the market awaits clearer direction on inflation and Fed policy. The deeply special FNCL 6.5 roll created financing strain for hedgers last week, illustrating how extended duration and low prepayment sensitivity magnify costs in volatile markets. With 16 of 18 Fed officials now expecting at least one more rate hike this year, the risk of higher volatility persists until energy prices stabilize and September inflation data prove benign.
For now, the default posture remains conservative on lock/float decisions until a definitive Treasury rally emerges to justify a shift in borrower positioning.
**Locking vs Floating**
Technical resistance at 4.94% and 5.00% in 10-year yields has created important inflection points for lock/float decisions. One-off distortions in the bond market today suggest waiting for next week to better assess post-Fed momentum.
The consensus view remains conservative: maintain neutral positioning until a definitive shift or rally emerges that justifies moving away from cautious borrower guidance.
**Today’s Events**
Building Permits (Aug): 1.394M vs 1.41M forecast, 1.433M prior
Continued Claims (Sep/05): 1.730M vs 1.780K forecast, 1.774K prior
Housing Starts (Aug): 1.275M vs 1.31M forecast, 1.239M prior
Jobless Claims (Sep/12): 196K vs 208K forecast, 206K prior
Philly Fed Business Index (Sep): 37.8 vs 30.5 forecast, 47.4 prior
Philly Fed Prices Paid (Sep): 48.60 vs forecast unavailable, 40.90 prior
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
**UMBS 30-Year**
| Coupon | Price | Intra-Day Change |
|—|—|—|
| 5.5 | 97.41 | 0.22 |
| 6.0 | 99.81 | 0.12 |
| 6.5 | 102.05 | 0.11 |
**GNMA 30-Year**
| Coupon | Price | Intra-Day Change |
|—|—|—|
| 5.5 | 97.54 | 0.16 |
| 6.0 | 99.87 | 0.09 |
| 6.5 | 101.76 | 0.16 |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
|—|—|—|—|
| 2-Year | 4.73 | 98.858 | -0.025 |
| 3-Year | 4.803 | 98.818 | -0.026 |
| 5-Year | 4.823 | 98.031 | -0.032 |
| 7-Year | 4.89 | 97.713 | -0.039 |
| 10-Year | 4.96 | 97.382 | -0.04 |
| 30-Year | 5.294 | 97.471 | -0.033 |
Subscribe free to stay ahead of daily mortgage market moves at WellThatMakesSense.com