**WTMS Blog Today = What’s up in Mortgage Today (PM) – 10/12/2026**
The mortgage industry converges on Chicago this week as 2,539 attendees gather for MBA Annual amid a landscape of rising rates, declining origination volumes, and mounting economic uncertainty. Fannie Mae speeds fell to 6.7 CPR in September—the slowest pace since April 2025—while Ginnie Mae slowed to 7.6 CPR, leaving only 0.5% of mortgages economically attractive to refinance. The Mortgage Bankers Association expects total single-family origination volume to decline 5% to just under $2 trillion in 2027, with purchase originations forecast to grow only 0.8% while refinance originations plummet 17% to $571 billion.
Mortgage rates climbed to 7.40% last week as the primary-secondary spread widened to 92 basis points, reflecting intensifying pressure on gain-on-sale margins. Credit trends show sub-700 FICO loans at 11.4% of 2026 UMBS issuance, the highest share since 2023, signaling potential expansion of borrower access through alternative scoring models like VantageScore 4.0. VantageScore 4.0’s gradual adoption across Agency channels raises critical questions about credit discipline and pool performance as lenders navigate the shift from tri-merge to alternative scoring standards.
Consumer Data Industry Association research shows the tri-merge credit report costs homebuyers roughly $151, or about 1% of average closing costs, yet the potential savings from moving away from the standard could be marginal compared to long-term impacts on underwriting rigor. MBS and Treasury markets staged a modest recovery at week’s end after sustained selling pushed yields to fresh 2026 highs, with strong demand at longer-dated Treasury auctions suggesting some stabilization in investor appetite. However, persistent inflation concerns, geopolitical uncertainty, and elevated fiscal pressure continue to weigh on bond valuations, and any rally appears opportunistic rather than a confirmed trend reversal.
Inflation data and Treasury supply remain critical drivers this week, with CPI and PPI releases potentially determining whether yields consolidate or resume their upward trajectory. The MBA ratcheted down 2027 origination projections as higher rates and volume pressures squeeze lender profitability and force cost-structure realignment across the independent mortgage banking space. Wire fraud risks remain acute, with FundingShield’s Q3 2026 report showing 45.9% of transactions across a $108.7 billion monitored portfolio carried material wire and title-related risks, averaging 2.2 issues per problematic transaction.
Technology spend continues to accelerate at MBA Annual, with AI automation, appraisal platform modernization for UAD 3.6, and fulfillment tools dominating exhibit-floor conversations as lenders prioritize operational efficiency. Conference attendance reveals meaningful churn in industry delegation size, with ICE shrinking from 129 attendees in 2024 to 65 this year, while JPMorgan Chase expanded to 69 from 43, reflecting consolidation and shifting vendor strategies. Registration data shows 1,064 first-time attendees at Chicago versus 809 individuals appearing on all three recent MBA Annual lists, signaling substantial turnover in industry leadership and decision-making authority.
**Locking vs Floating**
The Friday before a three-day weekend typically sees lighter volume and tactical profit-taking from traders who held long positions during the mid-week bond recovery. While Friday’s modest rally near session highs provides some encouragement, the move lacks conviction and depends heavily on next week’s inflation data to determine whether the recovery continues or selling resumes.
**Today’s Events**
University of Michigan Consumer Sentiment (preliminary) expected at 10:00 AM ET on Friday, October 9; Boston Federal Reserve President Collins delivers remarks.
**Bond Pricing**
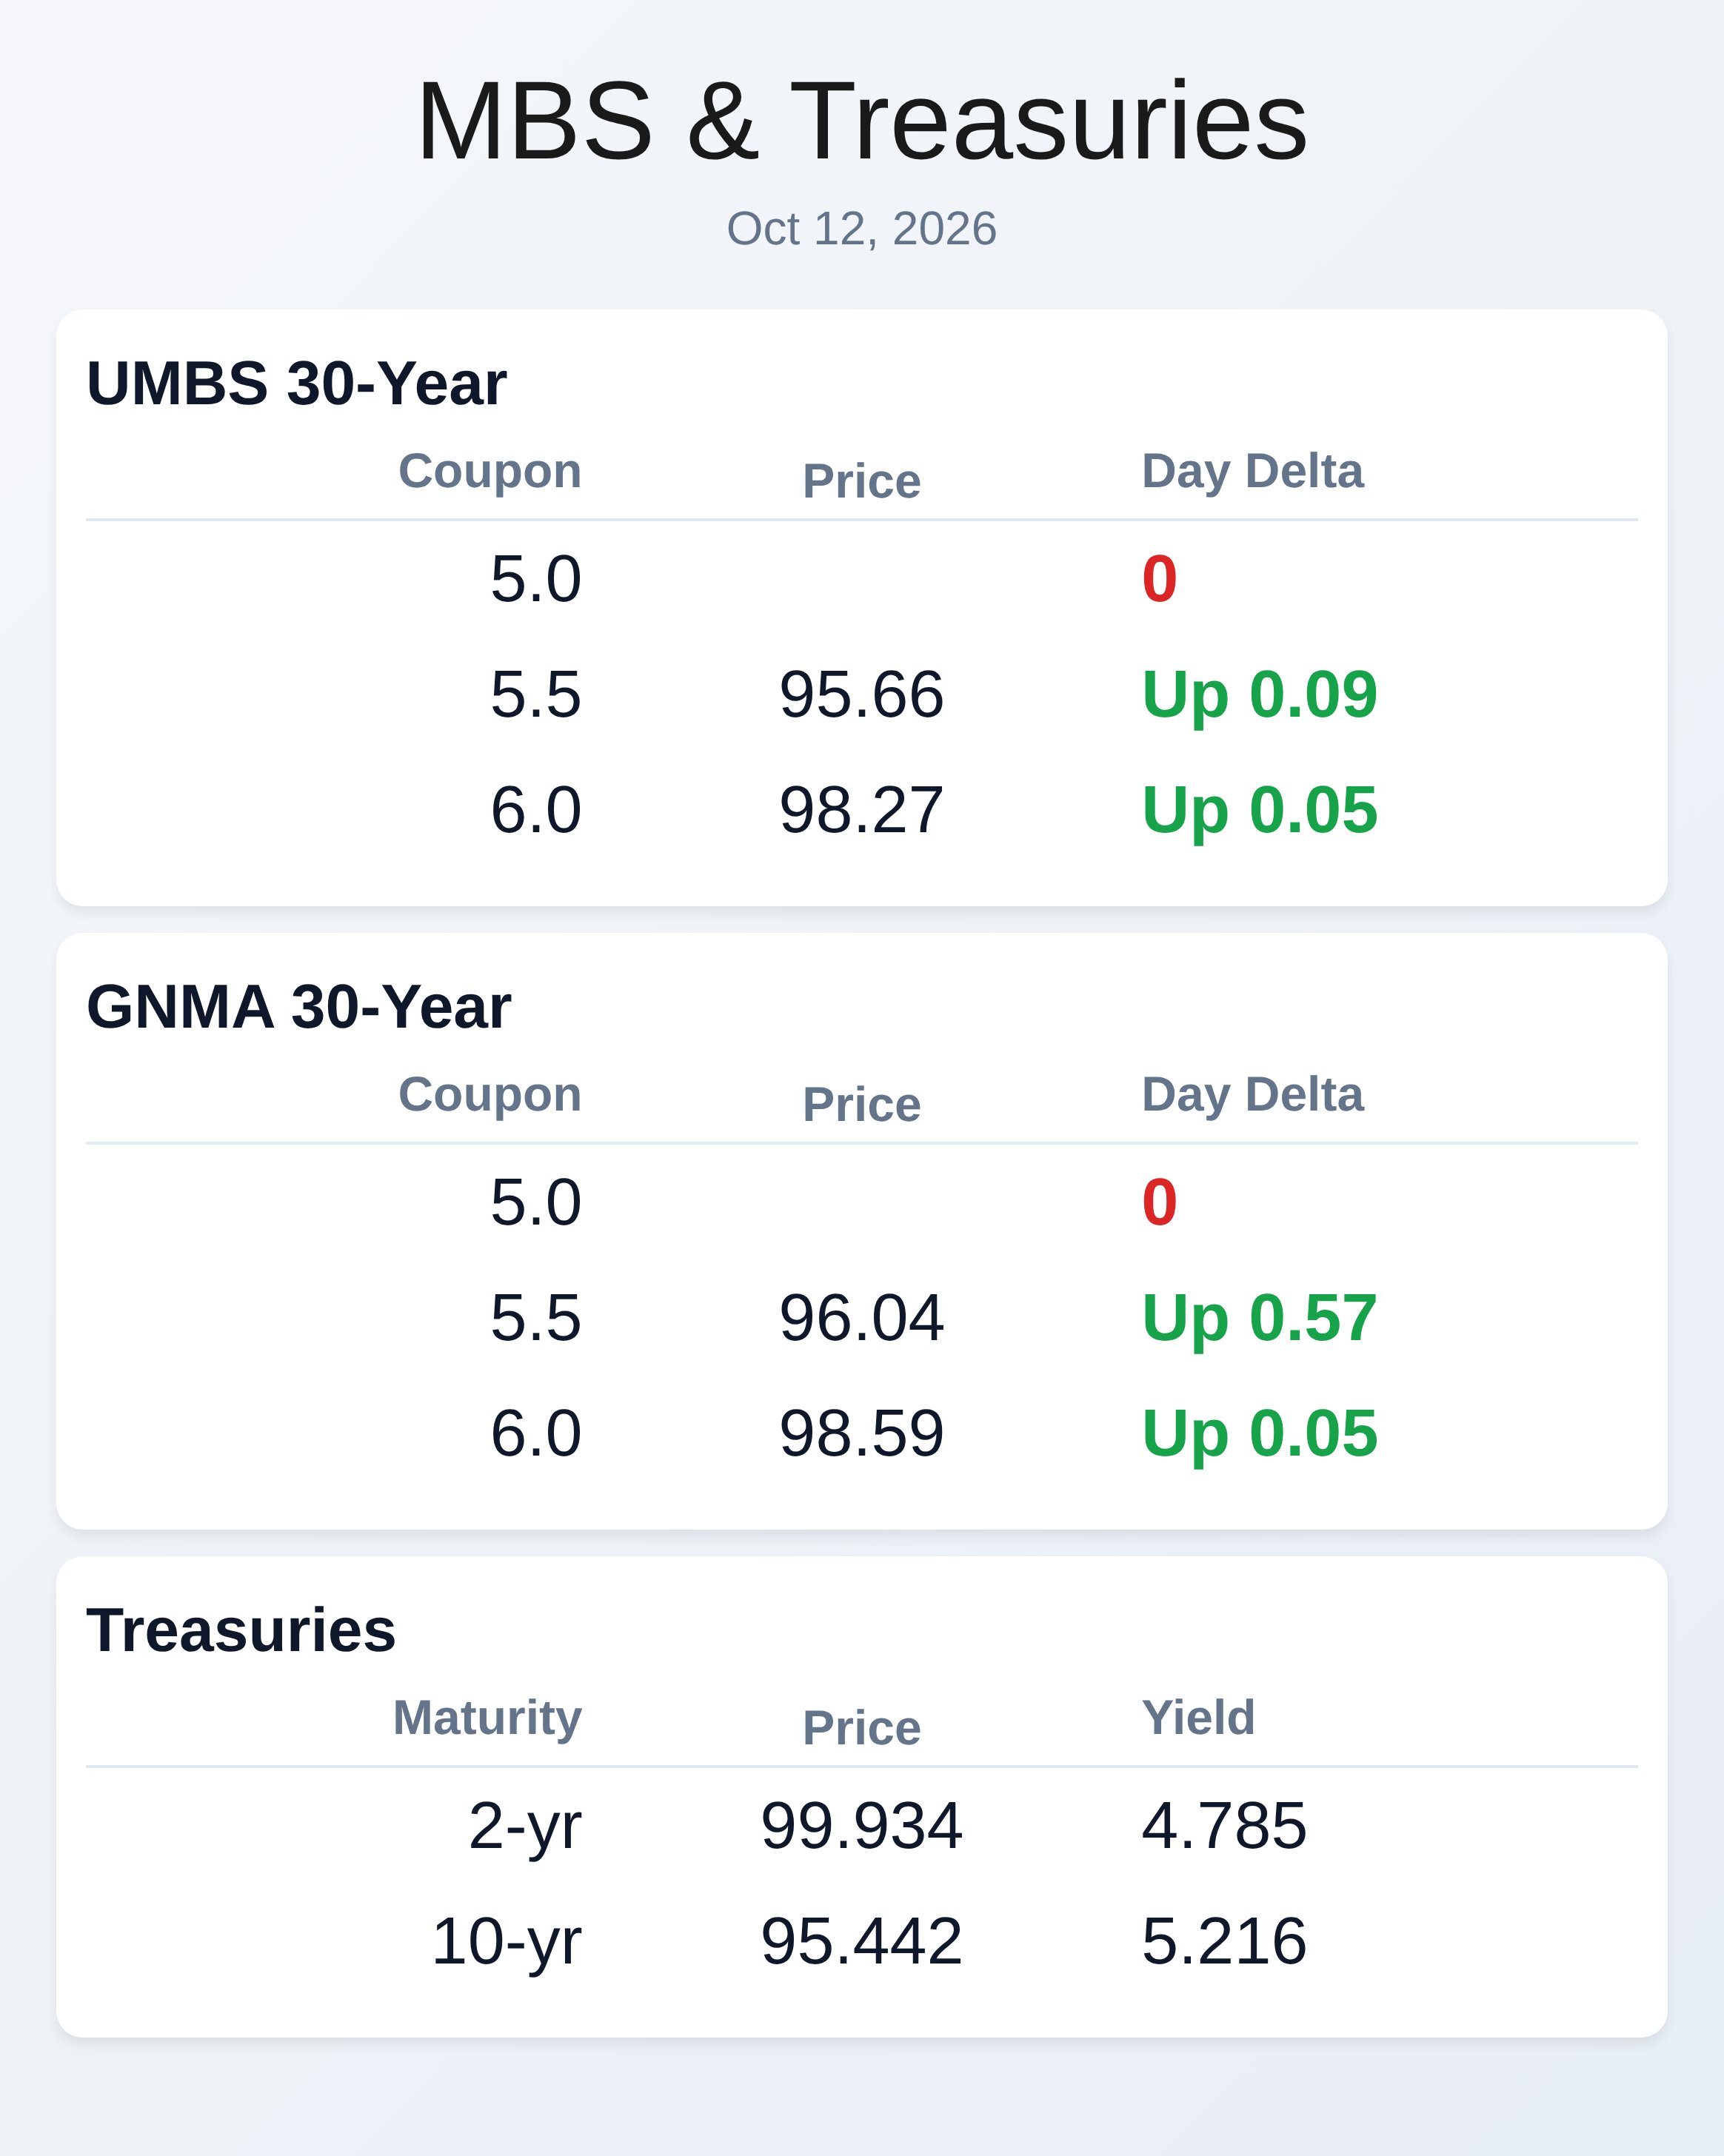
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |