**WTMS Blog Today = What’s up in Mortgage Today (AM) – 10/30/2026**
Mortgage rates stumbled lower this week as Treasury yields declined and the Federal Reserve held rates steady, with 10-year Treasuries ending near 4.92 percent by Friday morning. The Fed voted 10-2 to maintain its benchmark rate at 3.75–4.00 percent, signaling patience while acknowledging persistently elevated inflation and resilient economic activity. Chair Kevin Warsh’s cautious messaging and announcement that the Fed will conduct only six policy meetings annually instead of eight tamped down near-term rate-hike expectations.
Core PCE inflation cooled to 2.5 percent on an annualized basis, offering some relief to fixed-income markets, though headline inflation remains elevated at 3.6 percent year-over-year. Despite three consecutive weeks of rate declines, purchase applications remain 18 percent below year-ago levels and refinancing is down 61 percent, signaling the housing market remains frozen by affordability constraints. Loan officers across the country report that buyers are sitting on the fence longer than in years, using higher ARMs and seeking seller concessions to make deals work.
Non-QM production continues to grow, with lenders offering full non-QM suites including bank statements, 1099 income, and DSCR products to capture borrowers outside traditional guidelines. Fannie Mae reported third-quarter net income of $4.2 billion with net worth near $120 billion, while Freddie Mac posted $3.2 billion in earnings, both signaling the GSEs remain well-capitalized despite market headwinds. Optimal Blue’s September data showed non-QM volume climbing 8 percent month-over-month and ARM usage reaching 14 percent of locks—the highest since 2019.
The mortgage industry continues consolidating, with several mergers announced as lenders pursue scale to offset margin compression and volume decline.
**Locking vs Floating**
Ground-holding continues as lenders and borrowers assess whether recent rate declines signal a sustainable trend or a temporary reprieve. Technical analysis suggests 10-year yields could test 4.83 percent on the downside, but oil prices above $101 per barrel and persistent geopolitical tensions support an inflation case for higher rates.
Lock activity has picked up modestly on the week’s rate improvement, but borrower behavior remains hesitant—many are waiting for further evidence that affordability conditions are genuinely improving before committing.
**Today’s Events**
October Chicago PMI and remarks from San Francisco Fed President Daly are scheduled for later today. Q3 Employment Cost Index data released this morning showed +0.8 percent growth, consistent with a resilient labor market despite higher borrowing costs.
**Bond Pricing**
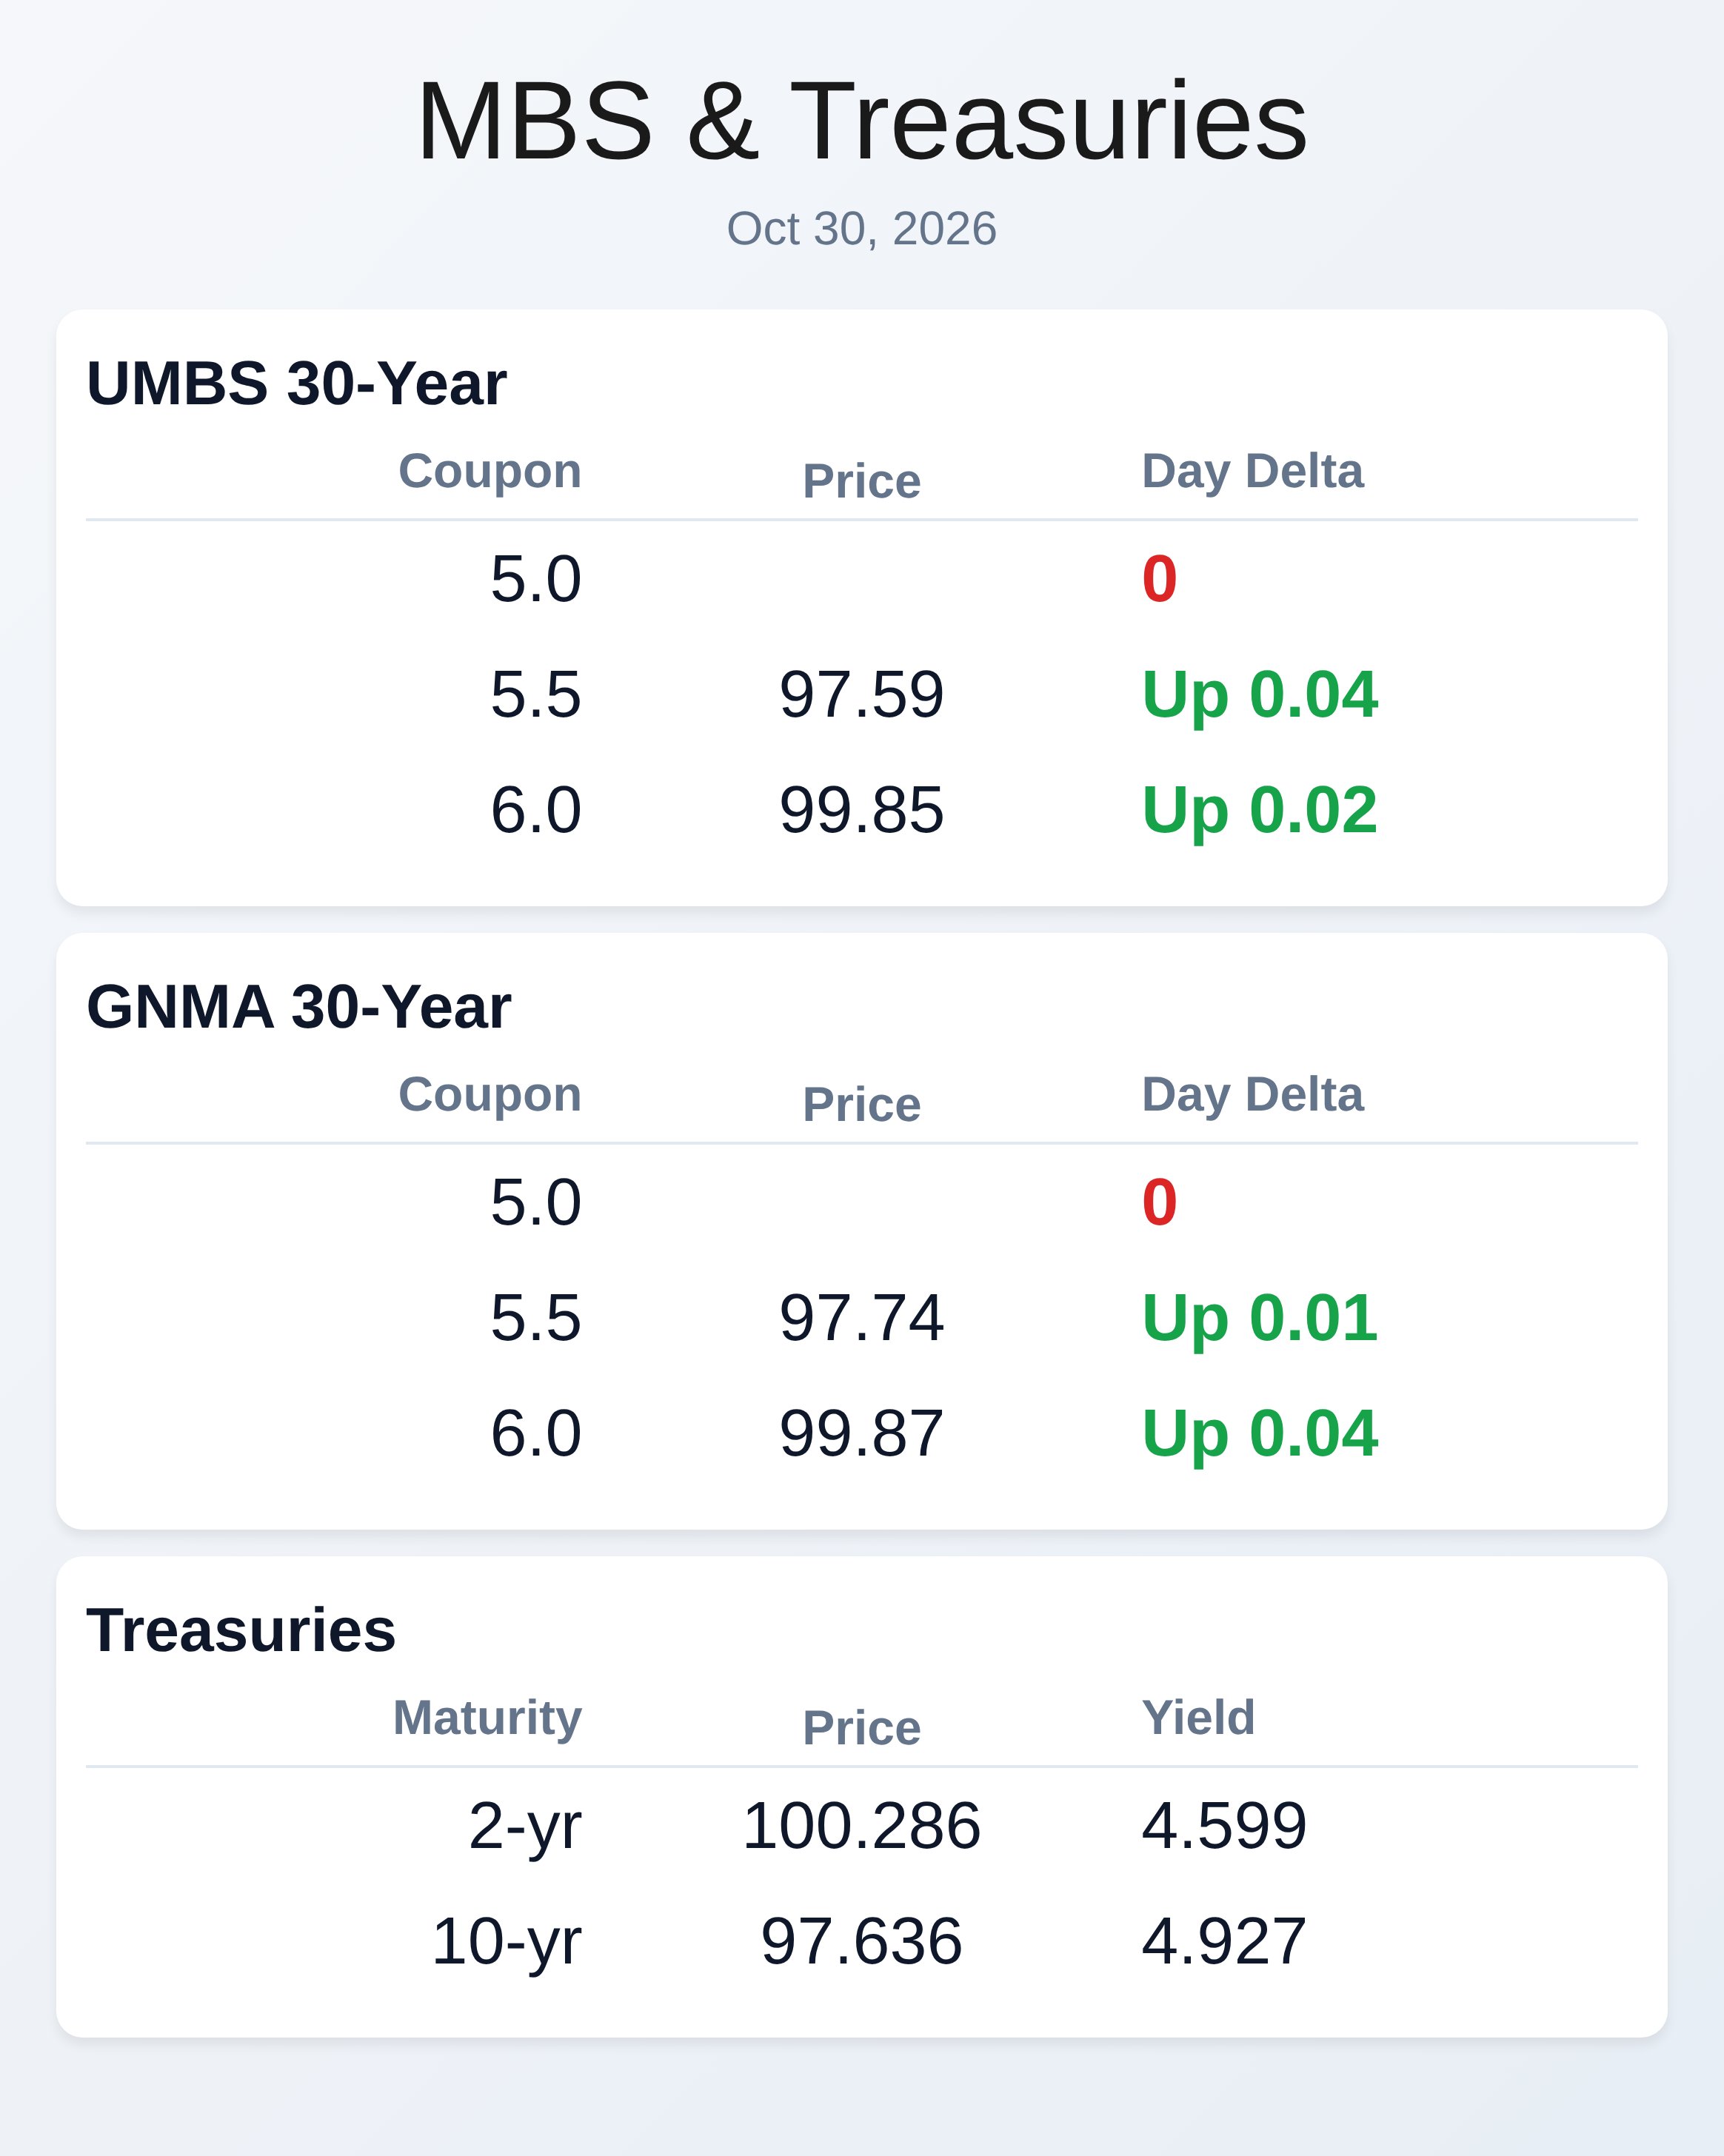
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |