**WTMS Blog Today = What’s up in Mortgage Today (PM) – 10/30/2026**
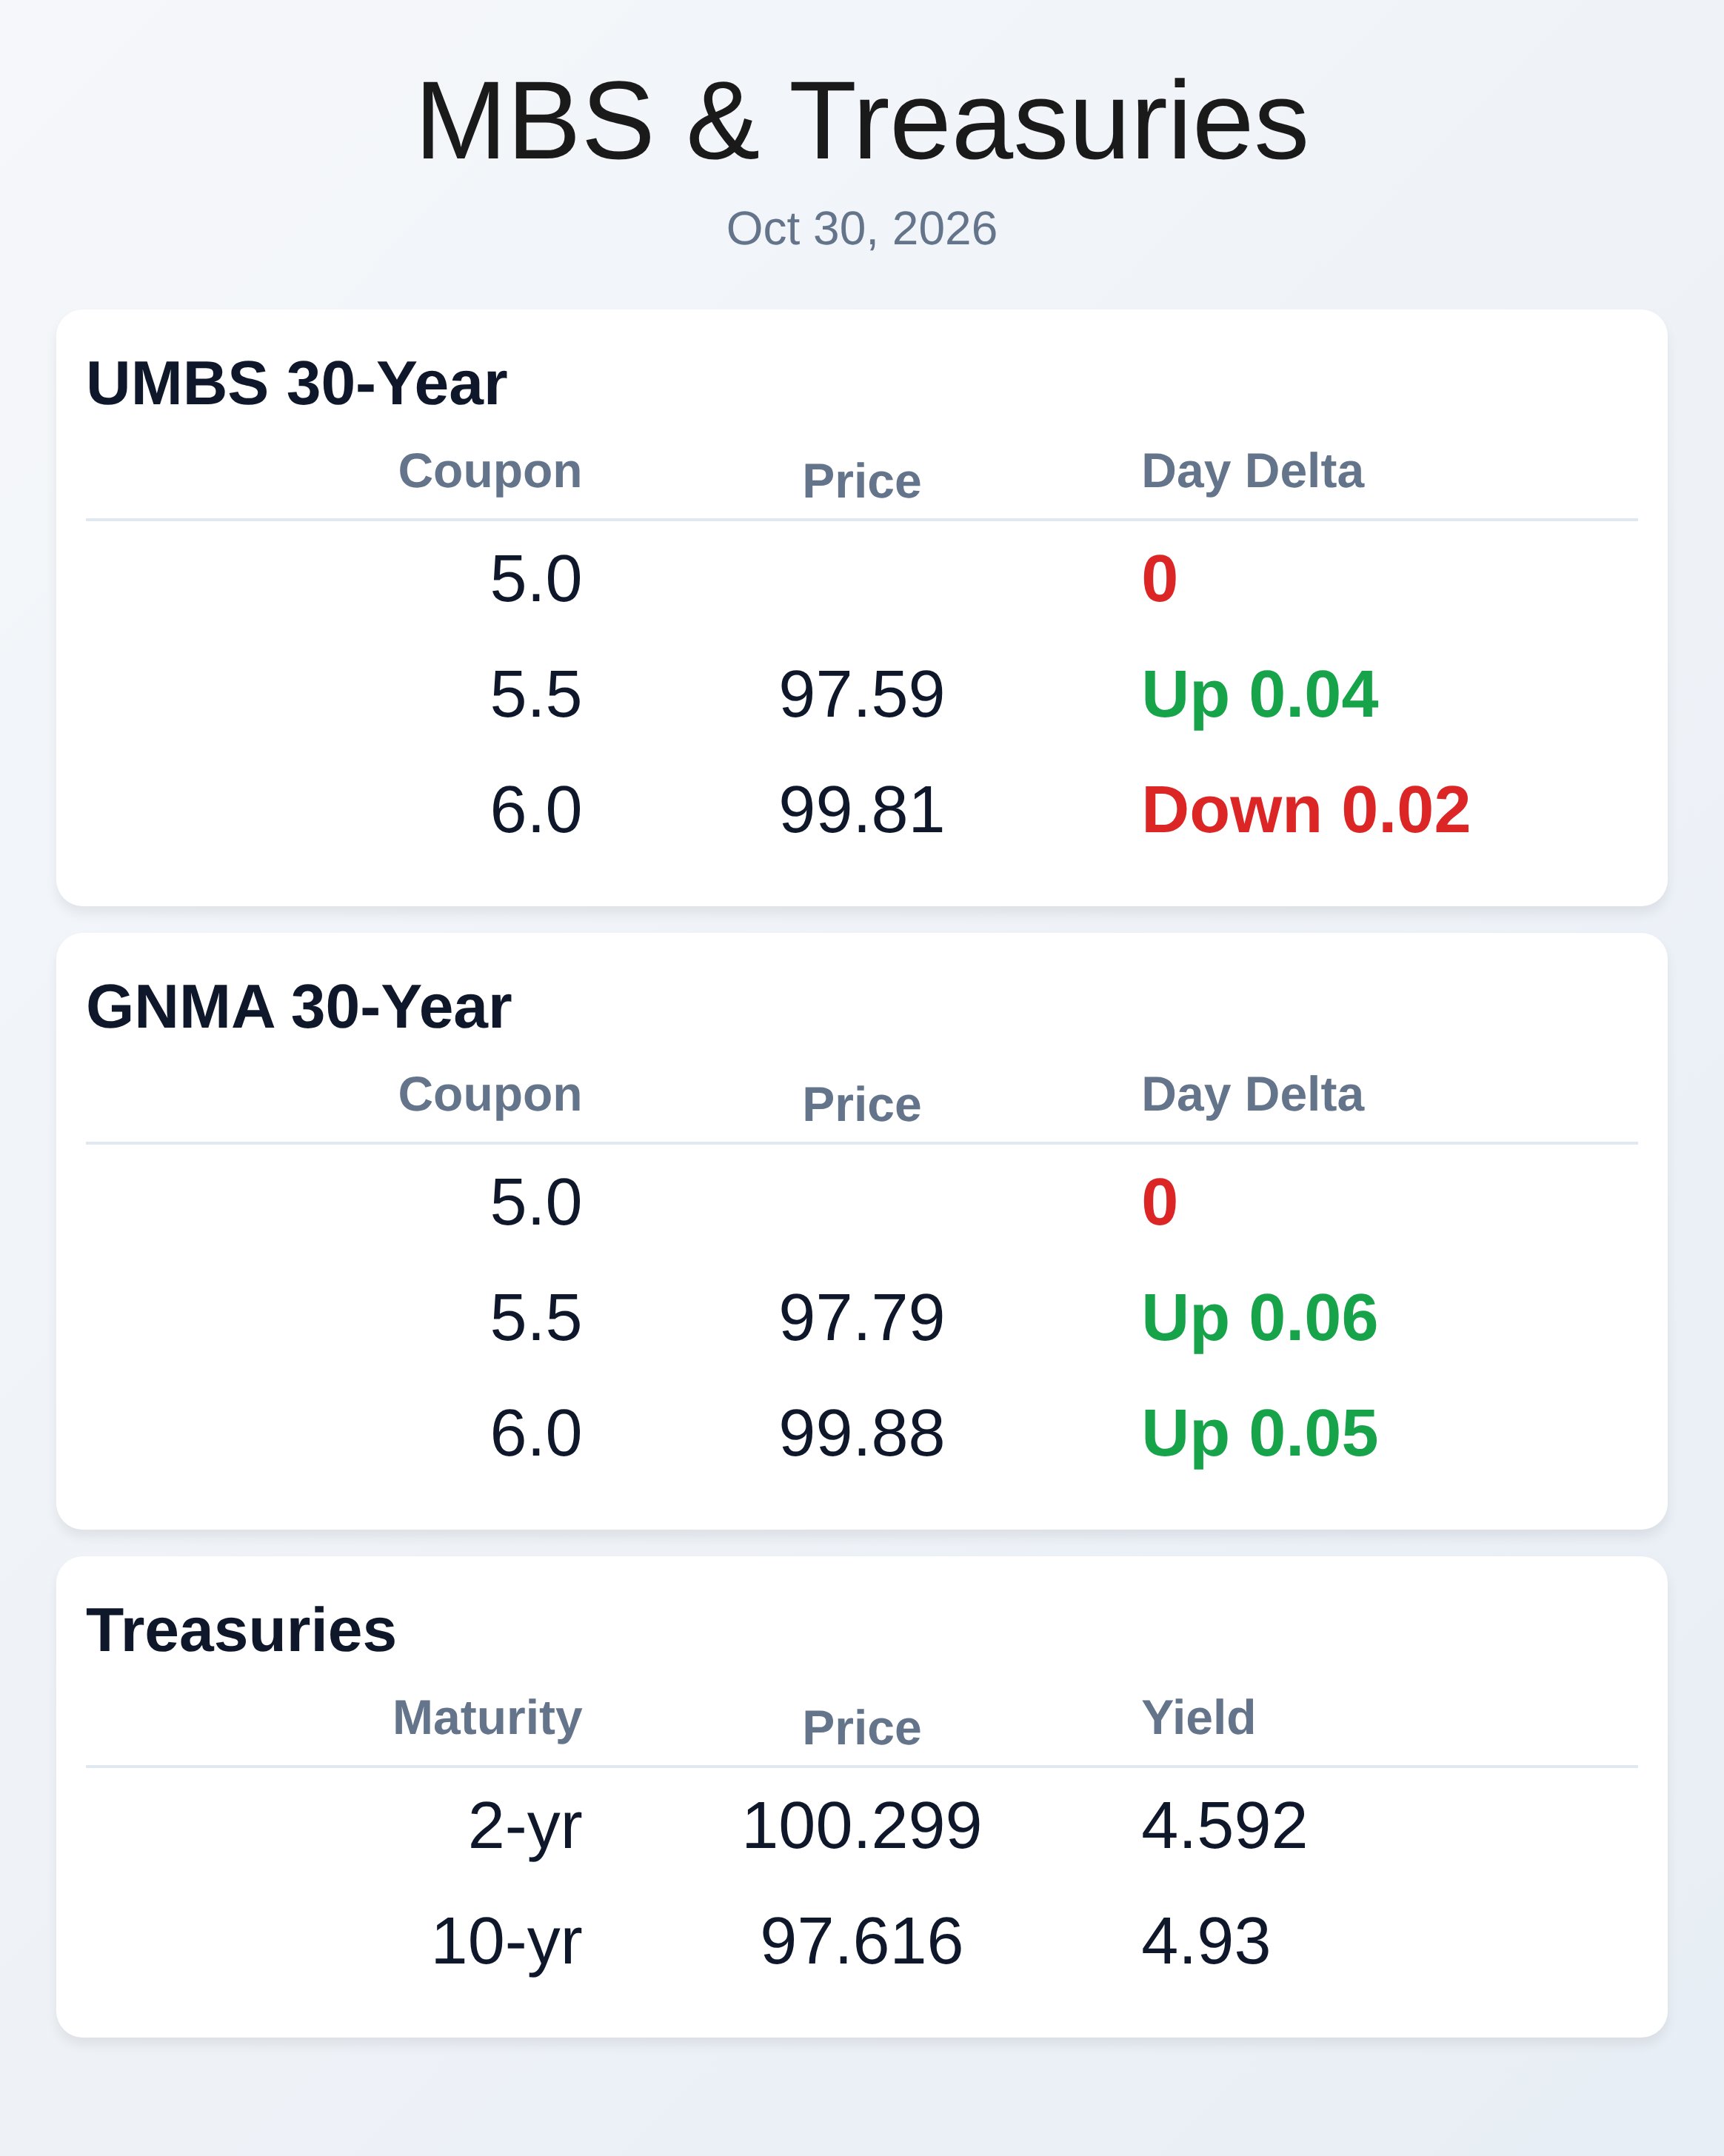
UMBS rallied into the close Thursday and held steady Friday as tech-stock jitters kept safe‑haven bids alive. The 30‑year UMBS 6.0 traded around 99.8 late Thursday, up roughly 5/8ths on the day, while the 10‑year Treasury yield dipped back below 5%. Price action has been driven less by data and more by risk-off flows tied to AI/data‑center credit headlines.
Even so, the rally has paused at familiar levels near 5.00% in the 10‑year. Intraday volatility remains elevated. Ginnie Mae coupons participated in the move.
GNMA 6.0s finished Thursday near 99.8, up roughly 0.3, with FHA/VA rate sheets improving modestly. Conventional stacks outperformed earlier in the week, but GNMA caught up as buyers leaned into liquidity. Spreads versus Treasuries remain wider than normal, keeping primary/secondary spreads sticky.
Pipeline hedgers should mind coupon selection as carry and liquidity diverge. Macro inputs were mixed. The Fed held rates unchanged and signaled a wait‑and‑see stance, and September core PCE printed 0.3% m/m and 3.1% y/y alongside a 3.4% Q3 GDP pace.
The front end of the curve rallied on the Fed tone while long rates treaded water, reinforcing a flatter bias. Net‑net, the data didn’t derail the MBS bid, but it didn’t confirm a bigger downshift in inflation either. Translation: momentum is still headline‑ and tech‑driven.
On the desk, earnings underscore the split between production and servicing. Rocket posted sharply higher profits and market‑share gains on a $43.6B quarter, aided by a large MSR platform and strong recapture, while Pennymac leaned on servicing income, announced $29B of MSR sales to reduce debt, and outlined cost cuts as production margins compressed. UWM gave brokers price relief by waiving FHA/VA credit‑score hits through year‑end.
CrossCountry said VantageScore 4.0 lifted borrower pricing by about 62 bps in LLPA on average for eligible loans. Competitive execution is increasingly about which scorecard and fee stack you can use for a given borrower. At the policy level, the Administration’s new order pushes cheaper refis via permanent title‑acceptance pilots, potential LLPA relief on qualifying rate‑reduction refis, and borrower‑visible savings.
The mortgage‑insurance piece moved to a pilot that applies prospectively, with proactive PMI cancellation based on current values limited to new originations. Net effect: potential refi friction falls if agencies follow through, but operational and documentation standards will decide how fast savings reach consumers. Lenders should prepare disclosures and workflows that pass through any fee reductions cleanly.
Watch FHFA guidance for scope and timing. Housing demand remains fragile even as rates eased this week. MBA applications ticked up, ARMs gained share, and multiple metros are now skirting buyer’s‑market territory, yet affordability still binds and buyers are choosier.
Programs that lower cash‑to‑close, including DPA and seller concessions, are doing more heavy lifting than price cuts. Use the dip to refresh pre‑approvals, price permanent buydowns versus ARM alternatives, and re‑quote edge files that stalled at last week’s highs. Speed matters when intraday reprices are in play.
**Locking vs Floating**
The near‑term rate path is being set by “tech jitters” more than data, so rallies can extend or reverse quickly on headlines. With 10‑year yields stalling near 5.00% and resistance below at ~4.93%, close‑in pipelines should favor locking on morning strength to avoid negative reprices. Files with time and tolerance for volatility can float tactically, but only with firm triggers and fast lock execution.
Next week’s jobs data can reset momentum; until then, expect choppy, headline‑driven sessions. Coupon selection and hedge discipline matter more than usual.
**Today’s Events**
Core PCE (m/m) Sep: 0.3%; Core PCE (y/y) Sep: 3.1%.
GDP Q3: 3.4% annualized. Initial Jobless Claims (week of Oct 24): 194,000. Subscribe free for daily clarity at WellThatMakesSense.com.