**WTMS Blog Today = What’s up in Mortgage Today (PM) – 11/03/2026**
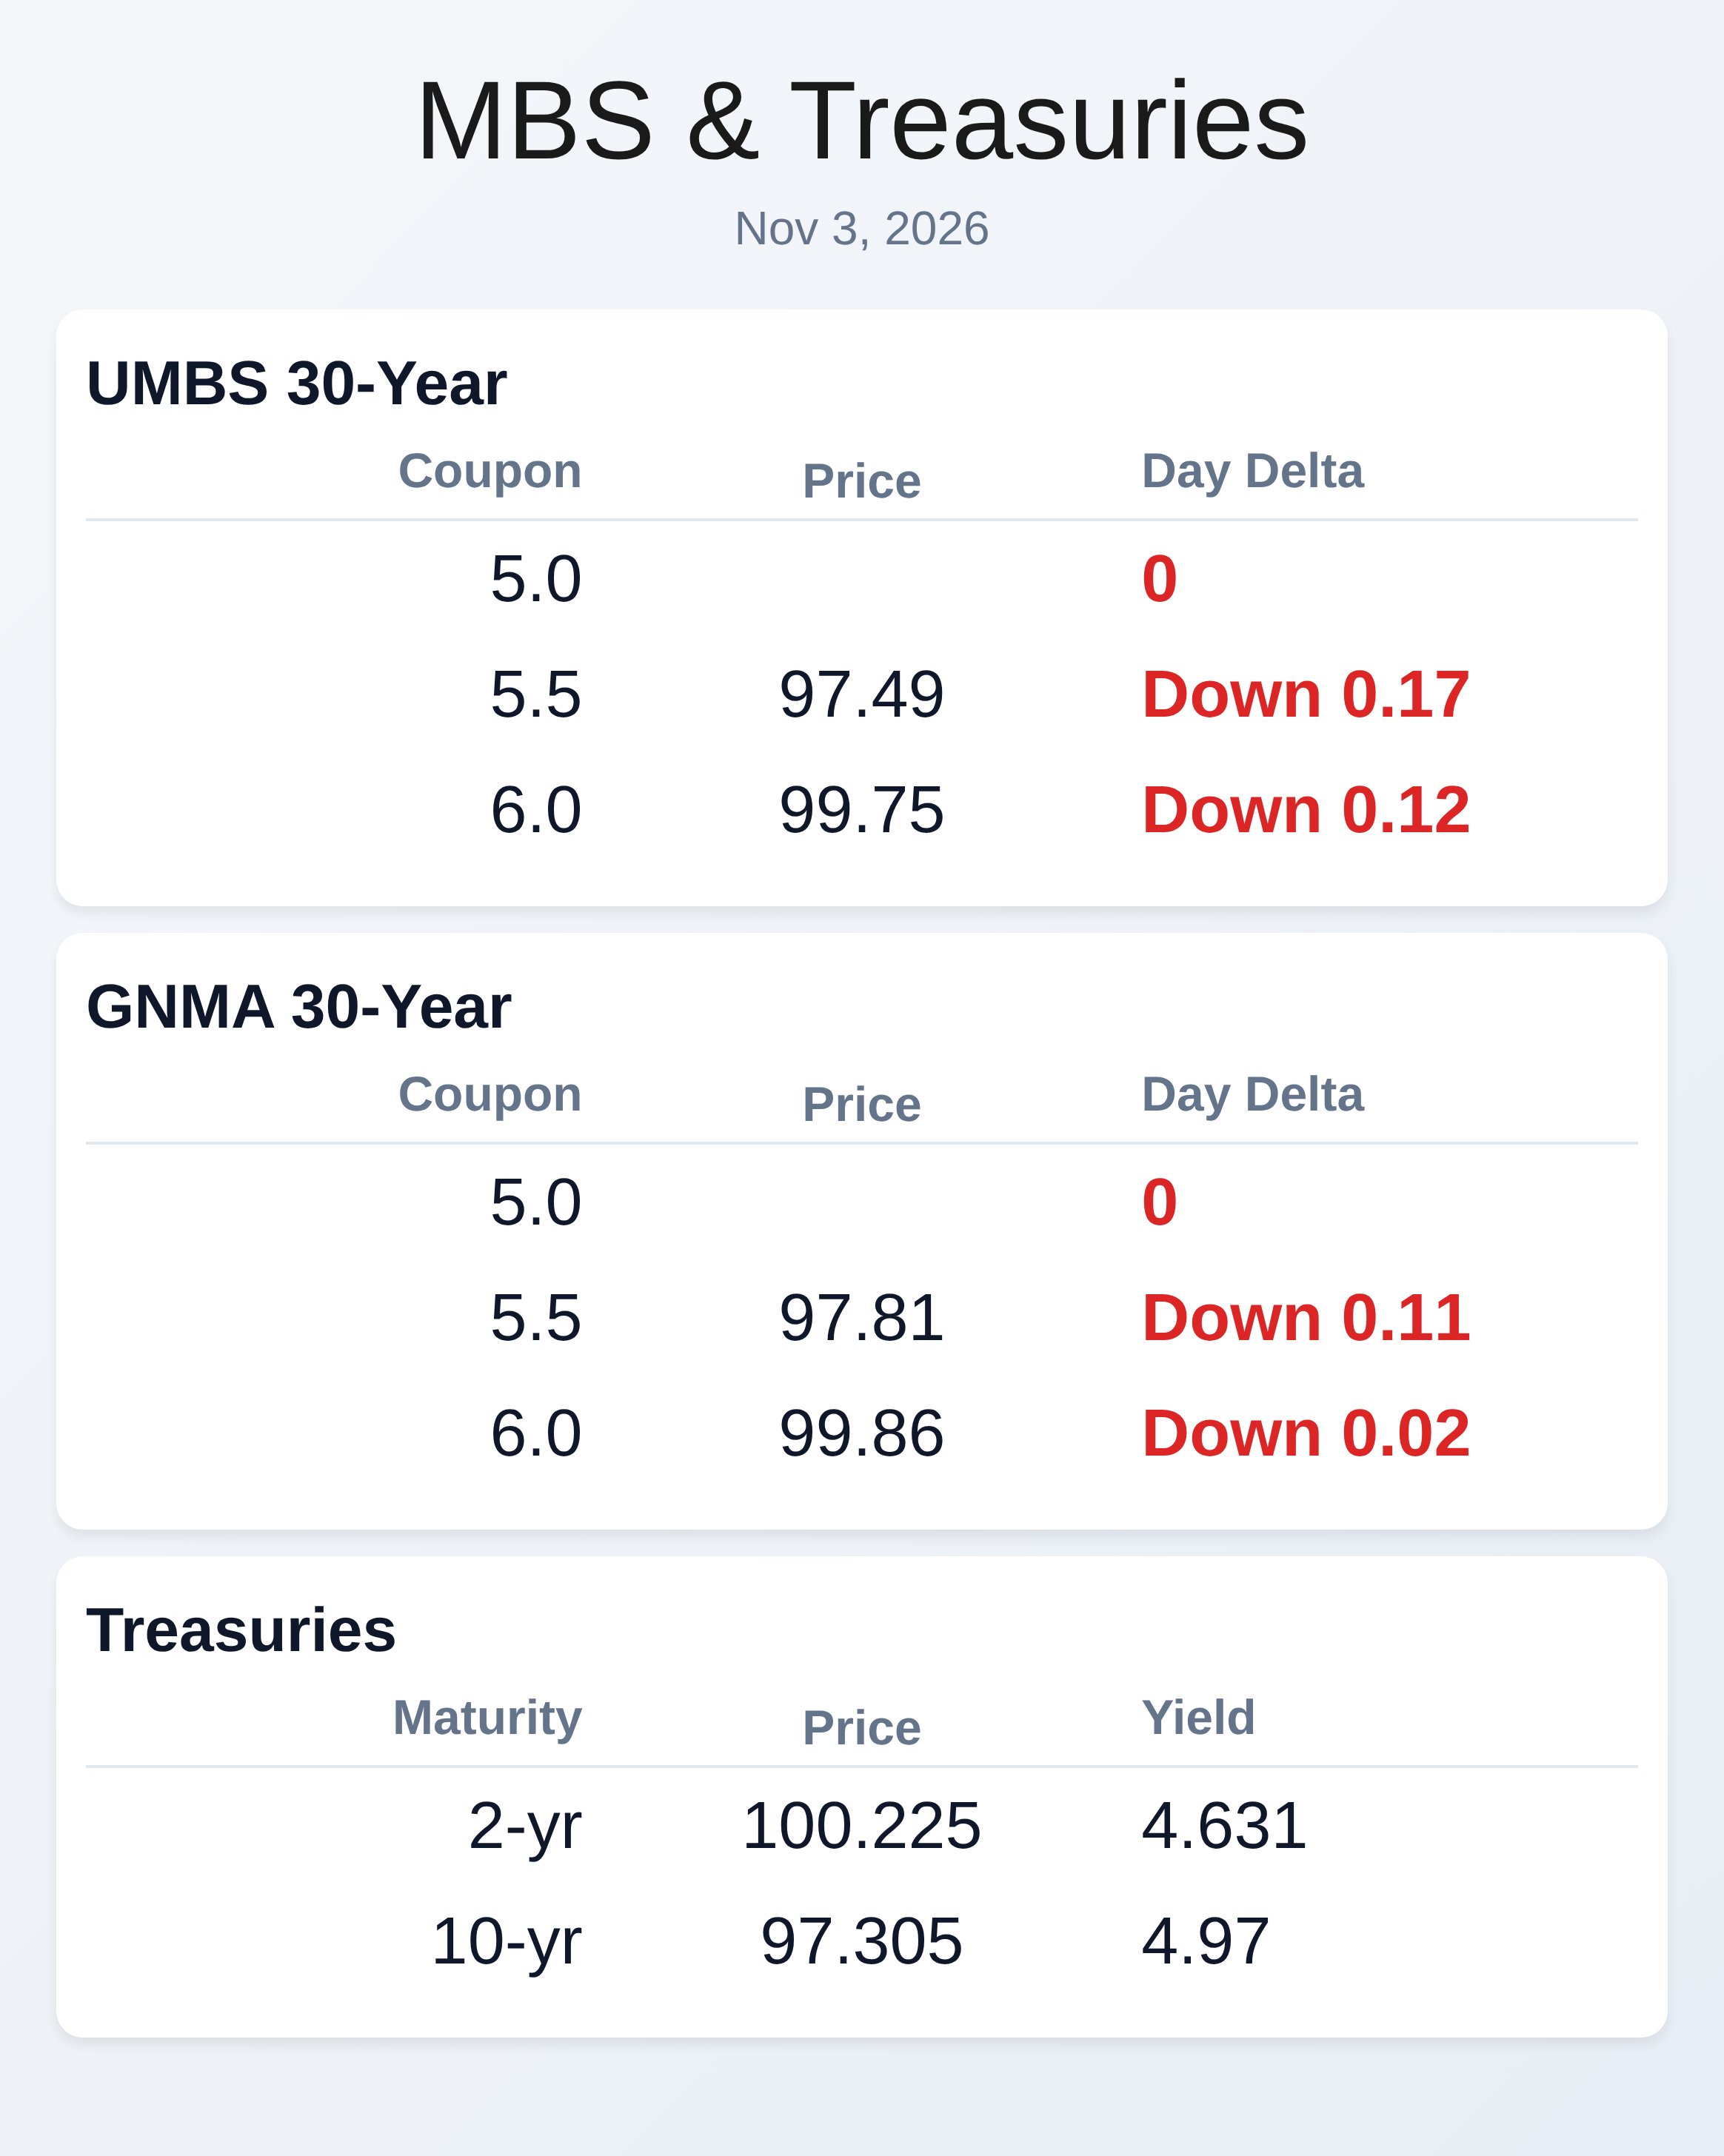
Bonds backpedaled as stronger-than-expected JOLTS job openings and firm equities undercut early gains. UMBS 6.0 closed near 99.81 (-0.05), while the 10-year Treasury yield climbed to roughly 4.97% (+5–6 bps). Earlier relief from a sharp oil drop faded, reinforcing the reduced correlation between energy and rates.
After last week’s tech-driven rally, bonds appear to need a fresh macro catalyst to revisit the recent lows. Rate sheets reflected modest afternoon negative pressure for jumpier lenders. The Fed’s hold delivered minimal market impact, with the curve pivoting—front-end a touch friendlier, long-end stickier—before returning to this week’s data narrative.
Traders had already priced a “wait and see” stance, keeping attention on labor tightness and inflation breadth. The recent “tech jitters” bid into Treasuries has leveled off, and bonds haven’t chased stock selloffs as aggressively in the past two sessions. Bottom line: it’s a consolidation with a defensive tilt until data break the stalemate.
GNMA and conventional coupons were little changed net, but intraday swings kept pipeline management busy. GNMA 6.0 hovered near 99.85 (-0.03), and price action suggested value buyers are cautious without a clean macro trigger. MBS still face wide spread headwinds from rate volatility and uncertain demand, despite last week’s brief outperformance during risk-off.
Expect coupon selection and buydown strategies to remain pivotal for execution. Credit-score competition is increasingly shaping eligibility and pricing. UWM extended VantageScore 4.0 into non-agency, potentially rescuing near-miss borrowers shut out by Classic FICO overlays.
CrossCountry reported average LLPA reductions of 62 bps (about $2,500 per loan) for borrowers with better VantageScore outcomes and removed its 80% LTV cap on qualifying conventional use. For secondary teams, this means testing both models’ execution, investor appetite, and QC controls to avoid adverse selection. For originators, it’s a new reason to re-run scenarios across models before declaring a “no.”
Earnings underline the market’s split personality: servicing cushions while production margins compress.
Pennymac posted $29 million in profit with a production loss offset by servicing income, while Rocket touted share gains even as wholesale volume slipped. Tools like Rocket Pro’s real-time counter feature aim to defend refis by tightening the “speed-to-match” gap when a borrower presents a rival LE. The strategic theme is clear: protect recapture, move faster at the point of sale, and let MSR value stabilize the P&L.
On the ground, rate stability is elusive, keeping borrowers cautious and LOs focused on precision. With headline mortgage rates hovering in the low- to mid-7s and ARMs gaining share, tactics center on targeted buydowns, exact pricing comparisons, and keeping prepaids low. Database mining and first-party engagement are outperforming spray-and-pray lead buys, particularly when paired with disciplined follow-up.
In a data-driven market, execution speed and model-savvy eligibility win files at the margin.
**Locking vs Floating**
Momentum has shifted cautious after today’s hotter labor signal and the recent stall in tech-driven bond support. Floaters should be tactical and time-sensitive, as re-tests of last week’s yield lows likely require softer data.
Lock bias makes sense for near-term closings given afternoon reprice risk and a heavier long end. If a decisive risk-off or weak jobs print emerges, reassess for incremental float opportunities. Absent that, prioritize certainty over small, timing-dependent gains.
**Today’s Events**
Job Openings and Labor Turnover Survey (JOLTS): stronger than expected
ISM Manufacturing PMI (Oct): 55.5; Prices Paid: 75.2; ISM Manufacturing Employment: 52.4
Construction Spending (Sep): -1.9% vs. 0.4% forecast
Core PCE (Sep): 0.3% m/m; 3.1% y/y; GDP Q3: 3.4%; Initial Jobless Claims: 194K
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |