**WTMS Blog Today = What’s up in Mortgage Today (PM) – 11/02/2026**
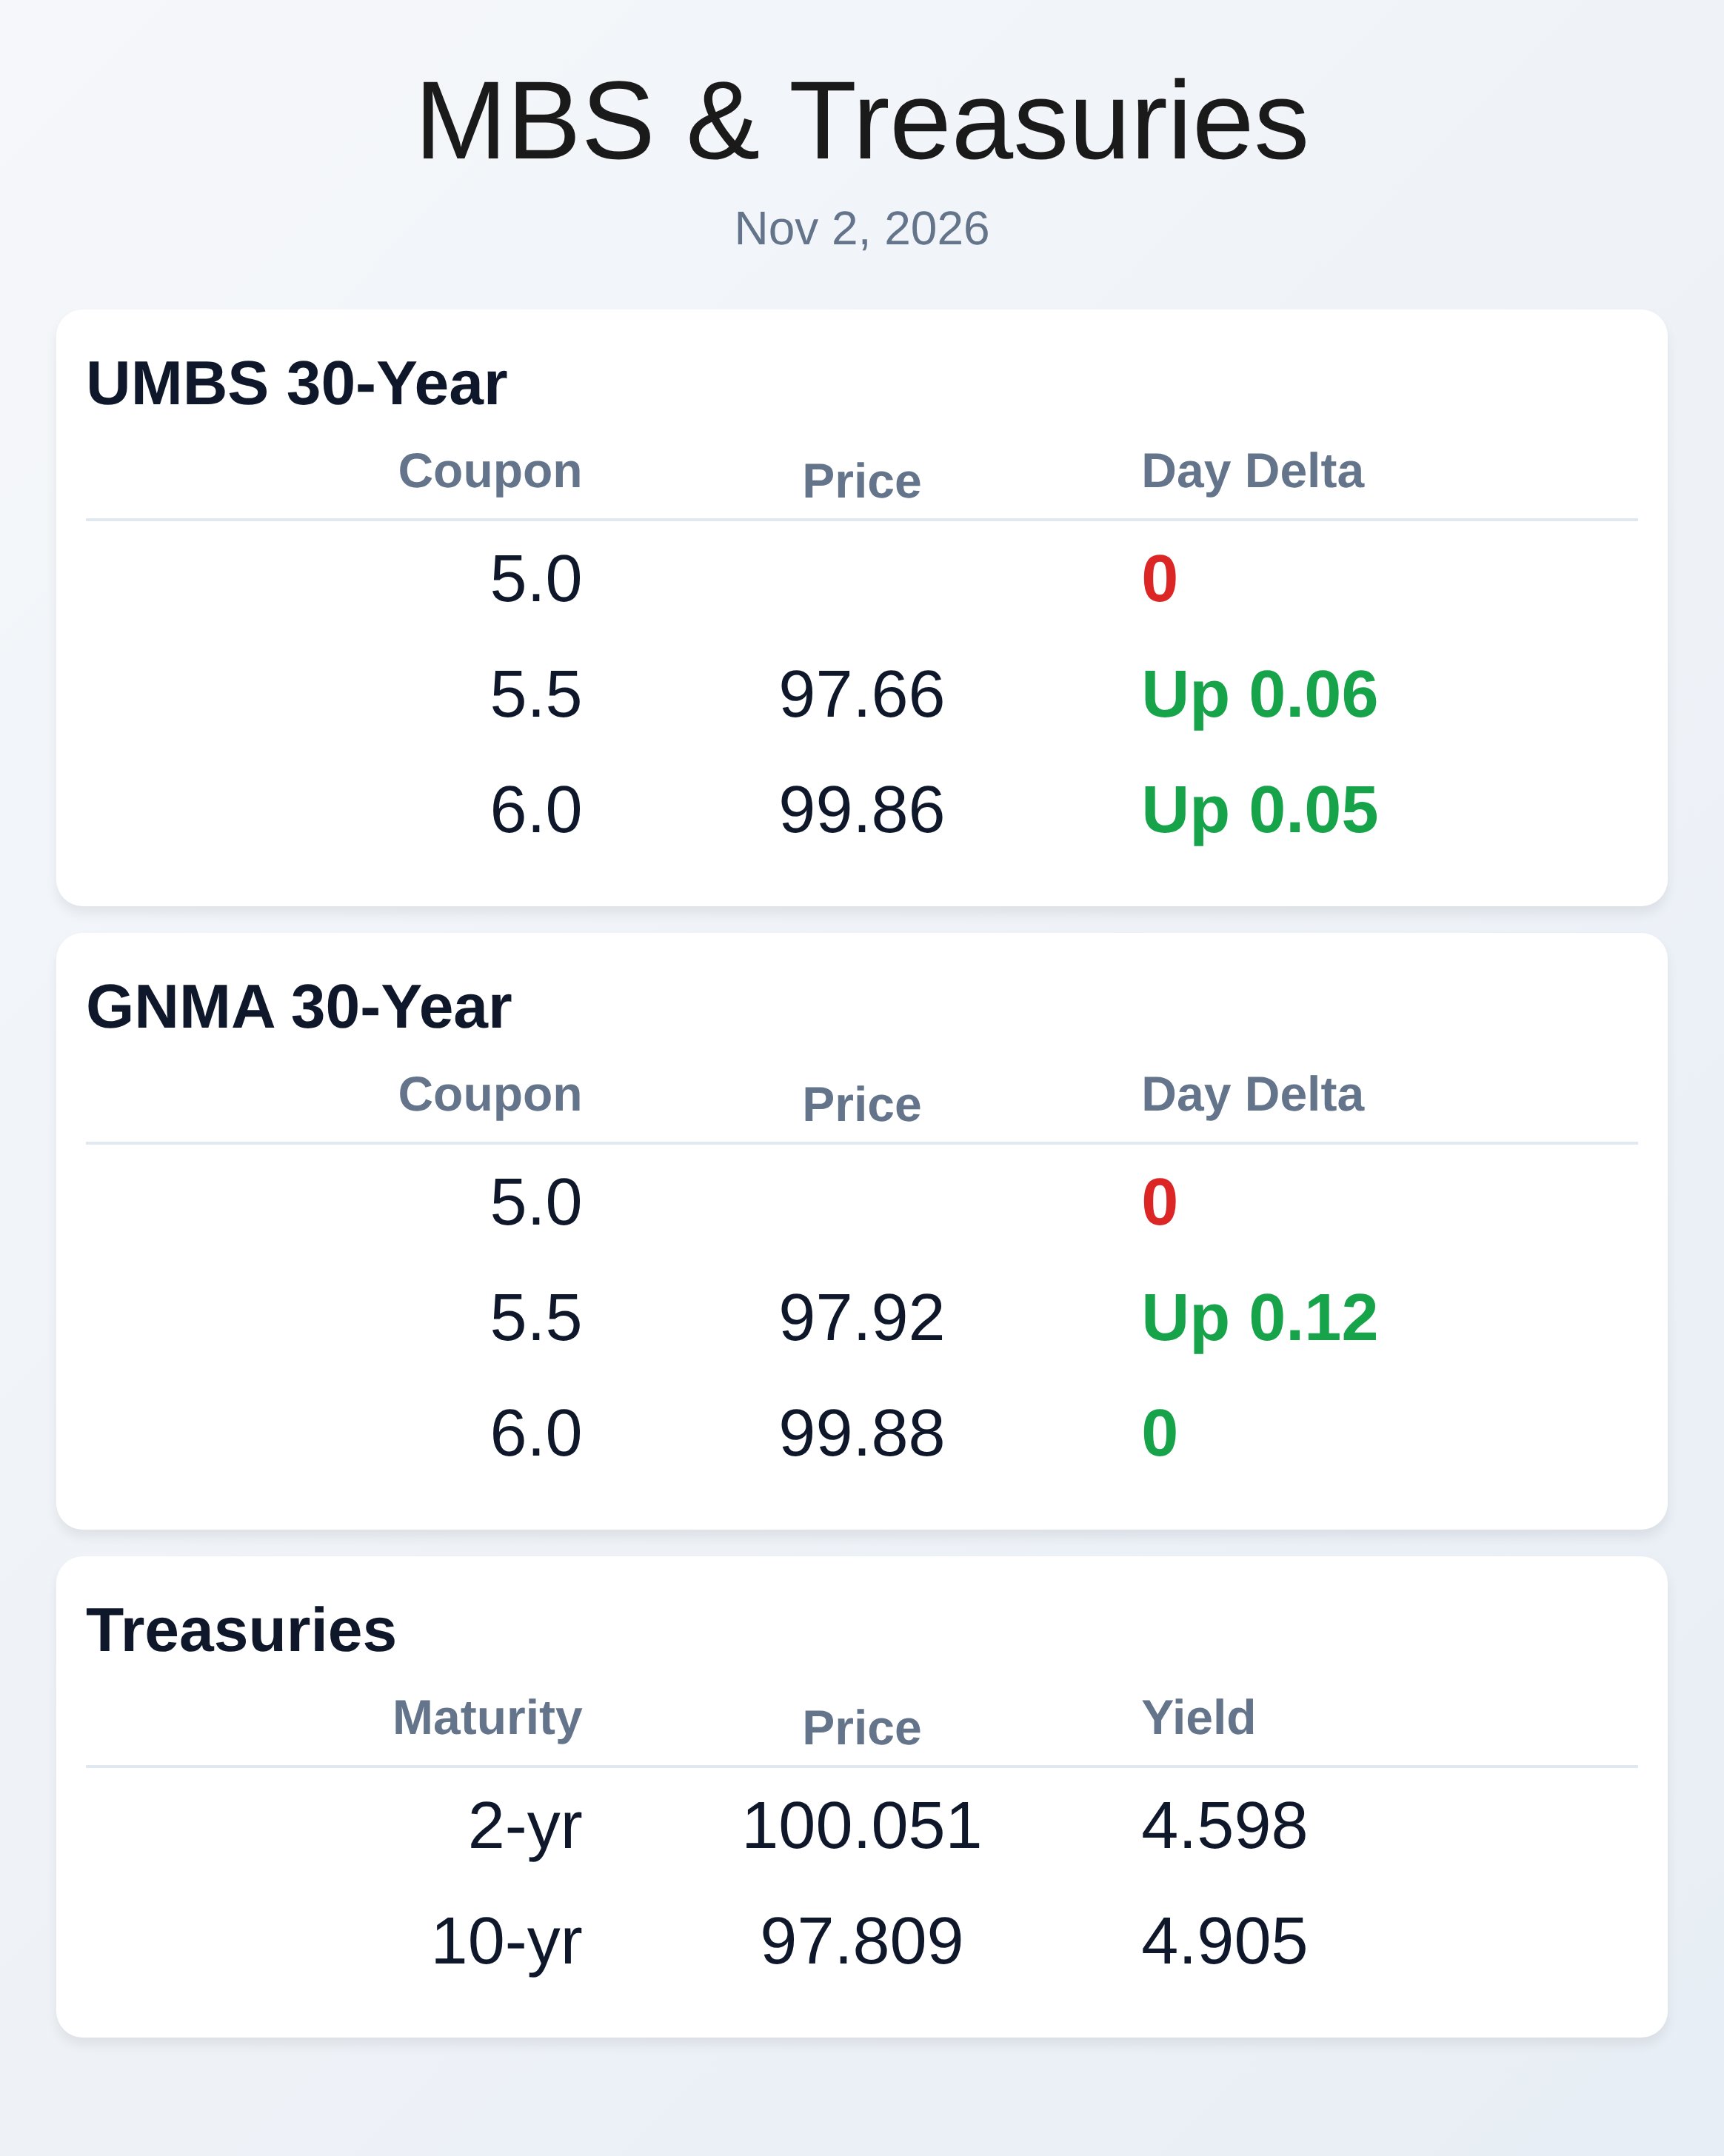
Bonds tried to extend last week’s rally but finished mixed, with UMBS little changed and the 10-year easing modestly. By the close, 30-year UMBS 6.0 sat near 99.86, up 0.05, while the 10-year yield slipped to roughly 4.91%. The usual “tech jitters” tailwind faded intraday as rates decoupled from equities.
Net: constructive, but not conclusive. Sellers should treat today as consolidation, not a breakout. The day opened with a bid on new-month flows and a firmer ISM manufacturing print that markets largely absorbed.
ISM PMI rose to 55.5, with prices paid easing a touch versus forecasts. Midday, MBS gave back an eighth from the morning’s highs, triggering a few negative reprice watches for jumpier lenders. Even so, UMBS 6.0 held green into the afternoon.
Rate sheets tracked that drift, not a trend change. The afternoon wobble came when Treasury’s quarterly borrowing preview hit, showing higher-than-expected financing needs before cash-balance adjustments. That supply signal trimmed gains and reminded traders that refunding details still matter for term premia.
Treasuries ended narrowly better on the day, but the knee-jerk safe-haven move stayed muted. Translation: value buyers remain cautious without a clear macro catalyst. Watch refunding and jobs data to confirm direction.
GNMA performance was similarly mixed, with 30-year Ginnie 6.0 at 99.87, down 0.01, and 15-year conventionals a touch firmer. Conventional 6.5s leaked slightly while 6.0s held, keeping stack tone steady. Spreads versus Treasuries were largely unchanged intraday, reflecting a market that wants proof, not hope.
Hedgers should stay disciplined on coupon selection and buydown exposure. Less conviction equals tighter risk knobs. On the credit front, score-model competition is migrating beyond agency.
One major wholesale lender is extending VantageScore into non-agency, while a large retail lender reported roughly 62 bps average LLPA benefit for borrowers who scored better under VS 4.0 and widened program eligibility. For sellers, the takeaway is execution math, not headlines: test investor appetite, rep/warrant terms, AUS interplay, and how grids pass savings through. Governance and pricing controls must evolve with model choice.
Policy risk remains a wild card. The new housing EO tasks FHFA with streamlining refi frictions (title acceptance, potential LLPA relief) and piloting proactive PMI cancellation for future originations, but borrower savings hinge on agency design and servicer operations. That helps pipelines only if implementation scales cleanly.
For now, affordability is still constrained even with last week’s modest rate relief, so focus on concessions, buydowns, and home-equity solutions.
**Locking vs Floating**
With bonds decoupling from tech today and refunding supply in focus, treat rallies as tactical. Favor locking on intra-day strength unless you have time and risk budget for event volatility.
A bigger rate leg lower likely needs a clear macro shock or softer labor data. Until then, expect two-way chop, especially around refunding details and Friday’s jobs report. Defensive posture remains prudent.
**Today’s Events**
Construction Spending (Sep): -1.9% vs 0.4% forecast, 0.9% prior
ISM Manufacturing Employment (Oct): 52.4 vs 52.7 prior
ISM Manufacturing PMI (Oct): 55.5 vs 54.6 forecast, 54.5 prior
ISM Manufacturing Prices Paid (Oct): 75.2 vs 77 forecast, 77.9 prior
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |