**WTMS Blog Today = What’s up in Mortgage Today (PM) – 11/05/2026**
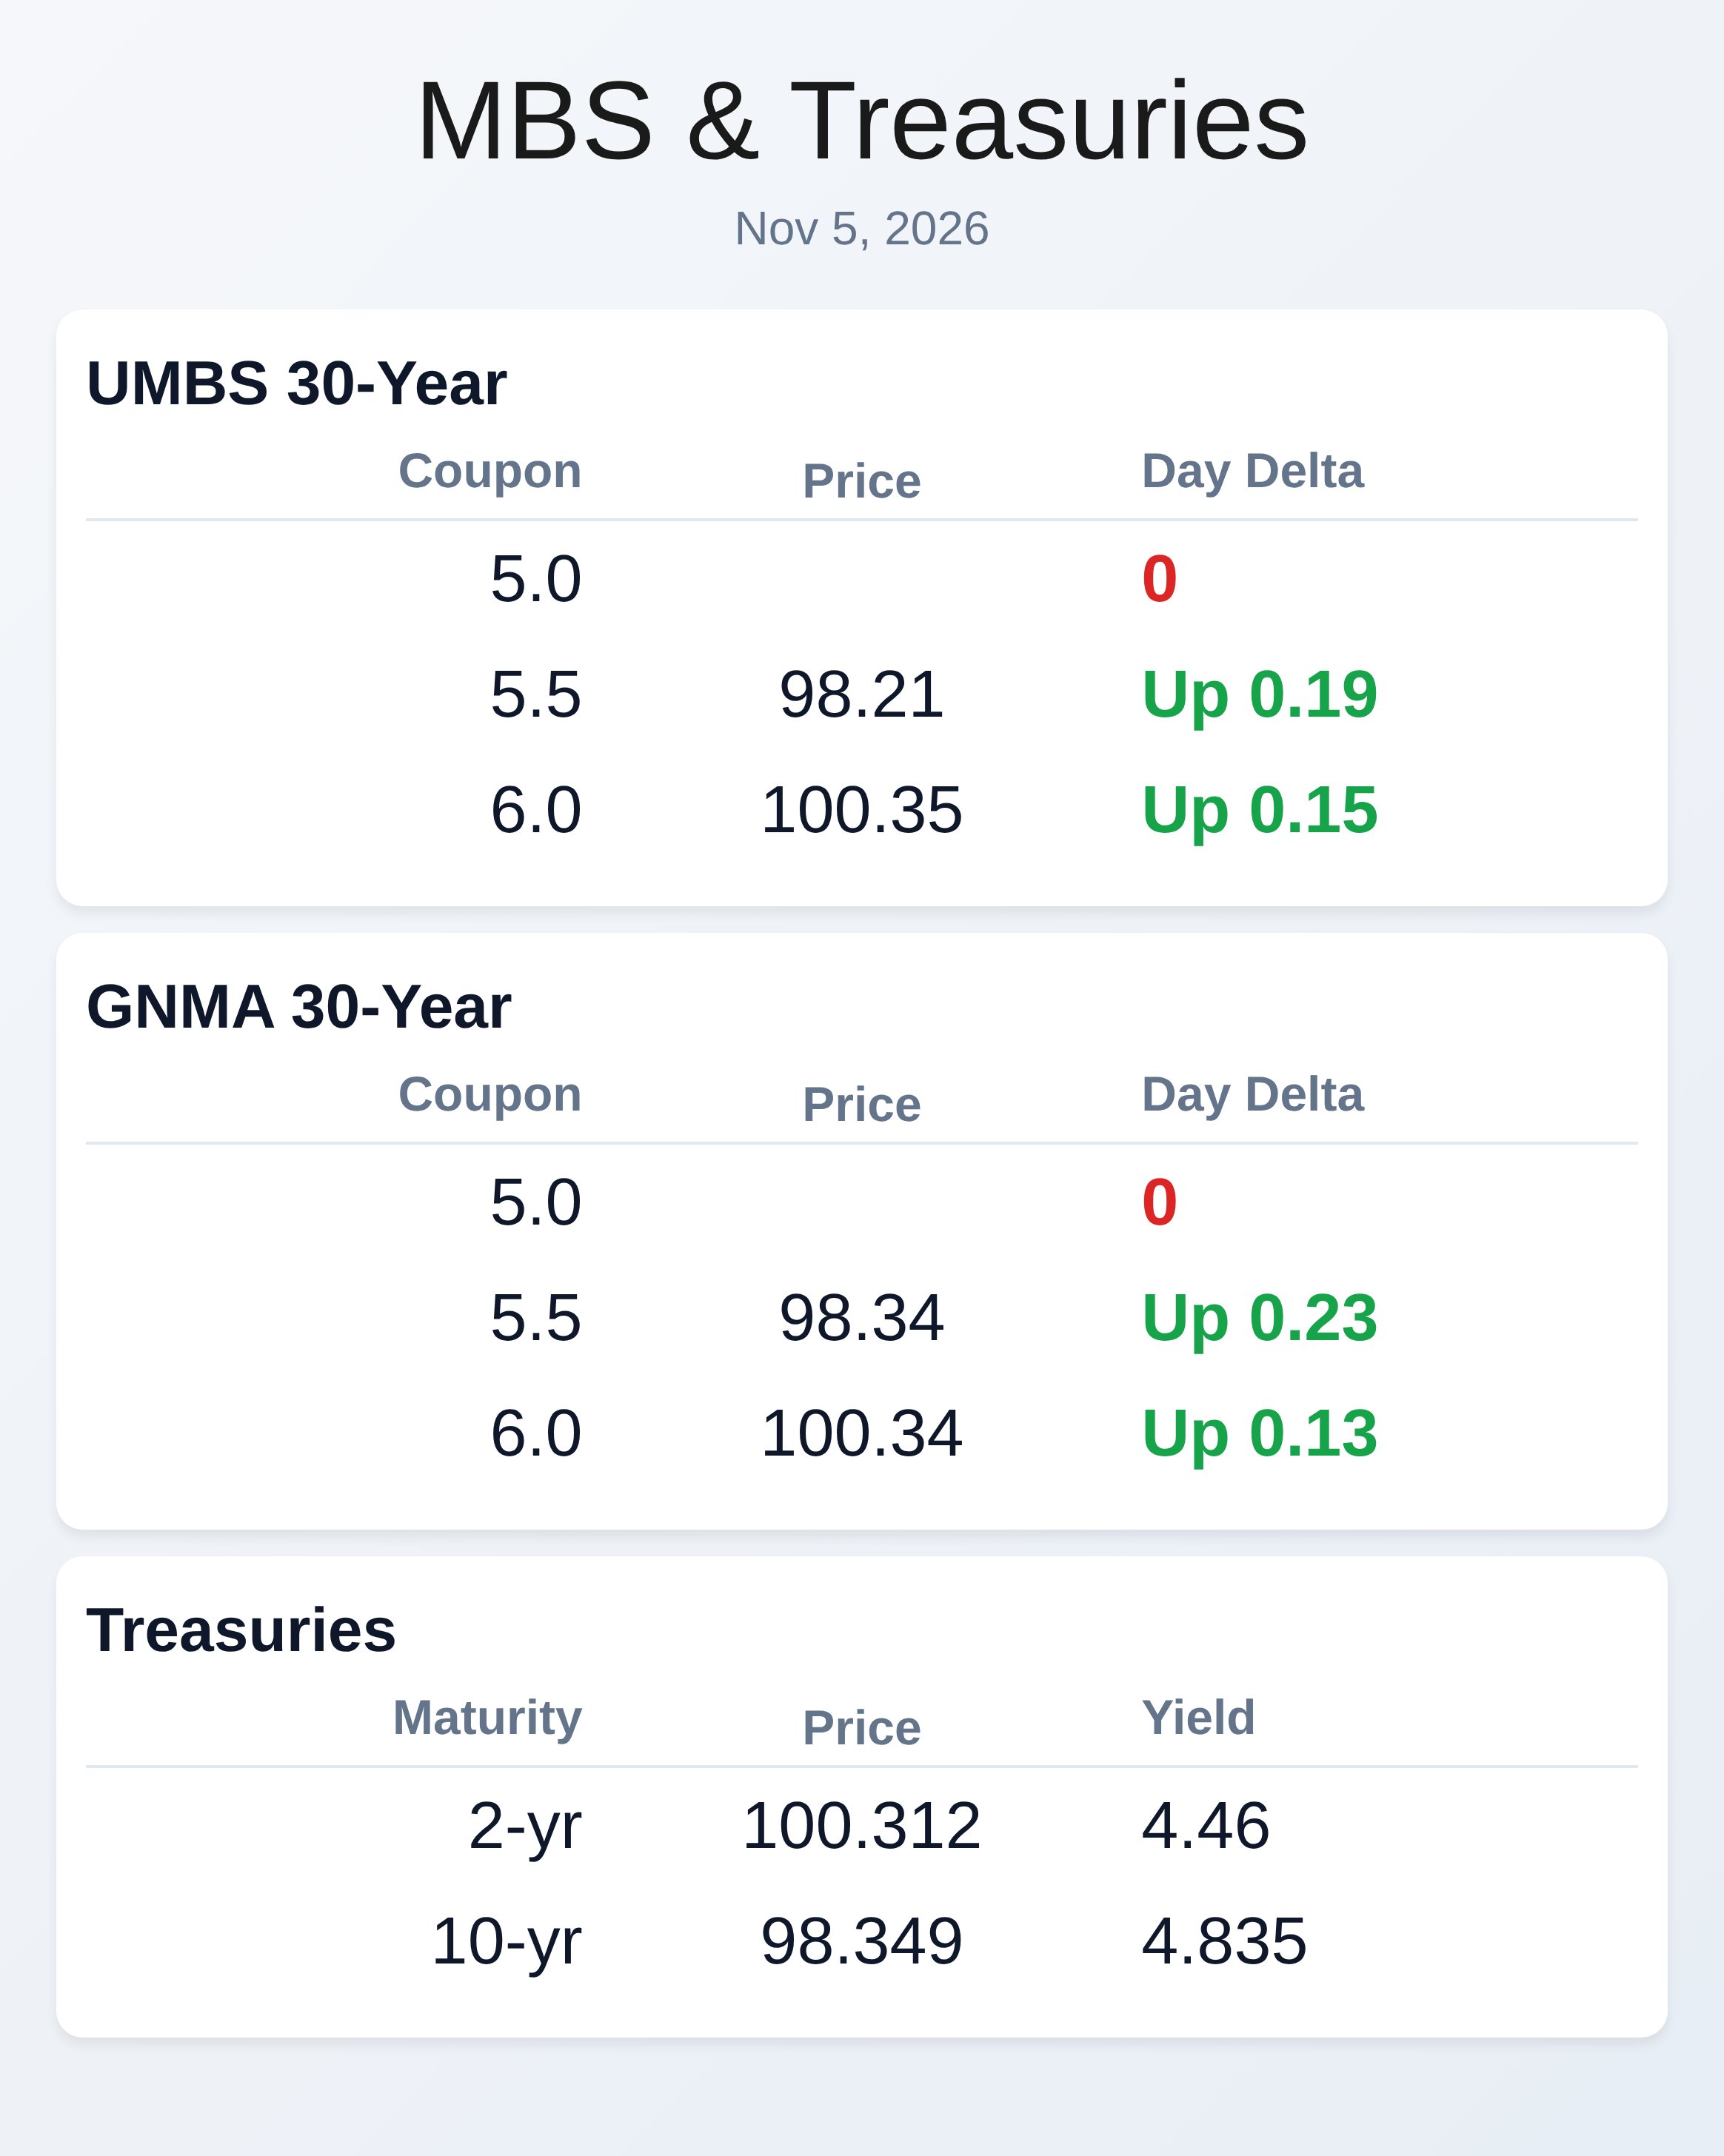
Bonds caught another bid as the AI/tech selloff deepened, pushing the 10-year Treasury yield down to roughly 4.83–4.89% over the past two sessions while UMBS 6.0 climbed to about 100.24–100.40. The move was strongest at the NYSE open, where a sharp rotation out of semiconductors fed flight-to-quality demand. Earlier in the week, bonds were little moved by headlines, but tech-led risk aversion has since dominated.
MBS gains were solid, though not as extreme as the equity rout might suggest. Net: rates improved, but with an eye on Friday’s jobs report risk. Oil’s nearly $20 slide since last Friday added a disinflationary undertone, even as bond-oil correlations remained spotty.
Traders also pared back some Fed-hike anxiety as “neocloud” funding concerns mounted. Still, bonds showed limits to sympathy rallies, at times resisting bigger plunges in stocks. The takeaway: tech jitters remain the near-term driver, but data can quickly reassert control.
Keep context tight; this is a tactical, headline-driven rally. GNMA paper participated in the strength, with GNMA 6.0 printing near 100.24 yesterday and adding modestly today. The long end outperformed the front end at times, consistent with growth-scare mechanics.
Even so, intra-day MBS reprices reminded pipelines that volatility cuts both ways. Spreads were stable-to-better with improved hedge P&L versus last week. Execution benefited more in 30-year coupons than in shorter cashflows.
In origination, UWM swung to a $213 million profit as expense cuts helped offset narrower margins and lower volume; the company also flagged sizable MSR sales to reduce debt. Pennymac posted $29 million of net income, though production swung to a small loss, leaning on servicing income and cost reductions while trimming MSR exposure. Rocket Pro launched “Quick Counter,” letting brokers live-counter competitor refi quotes inside Navigate to defend locks.
Lenders continue to refocus on recapture, cost-per-loan, and selective pricing where liquidity is deepest. Operational agility remains the differentiator while volumes stay tight. Credit-score competition is migrating from agency to specialty products.
CrossCountry reported borrowers who benefited under VantageScore 4.0 saw an average 62 bps LLPA reduction (about $2,500 in savings) and expanded eligibility; UWM is extending VantageScore into non-agency to clear some FICO cutoffs. For sellers, the question is less “which model” and more “which model yields better execution for this pool.” Expect investors to scrutinize model-driven mix shifts in pricing grids, eligibility, and advance rates. Demand remains uneven despite rate relief.
MBA apps slipped 1.2% last week as purchases fell 2% and refis were flat; ARMs rose with 5/1s near 6.29% as borrowers chase payment relief. Redfin data show sellers outnumber buyers by roughly 63%, giving buyers leverage but not necessarily lifting contracts. Pending sales remain weak even as inventory inches up, keeping pipeline pull-through fragile.
Rate volatility and affordability continue to dictate transaction timing and lock behavior.
**Locking vs Floating**
The rally is still highly dependent on tech-sector stress; any relief bounce in equities could lift yields and pressure rate sheets. Risk-tolerant borrowers can float while the 10-year holds below ~4.93–5.00%, but set clear lock triggers at those ceilings.
Near-term data risk is high (jobs Friday), and reprices can swing quickly with oil and headlines. For most closing soon, favor a defensive stance: capture gains rather than gamble on a bigger extension. If the rally extends, there’s room to add, but respect the tape.
**Today’s Events**
Jobless Claims (Oct/31): 189k vs 196k forecast, 195k prior
ADP Employment (Oct): 86k vs 69k forecast, 90k prior
Trade Balance (Sep): -$105.0B vs -$108.0B forecast
ISM Services PMI (Oct): 54.5 vs 54.8 forecast (subcomponents mixed; Prices 73.0)
S&P Global Services PMI (Oct): 56.1; Composite PMI: 55.9
Subscribe free for daily mortgage market intel at WellThatMakesSense.com.