**WTMS Blog Today = What’s up in Mortgage Today (PM) – 11/04/2026**
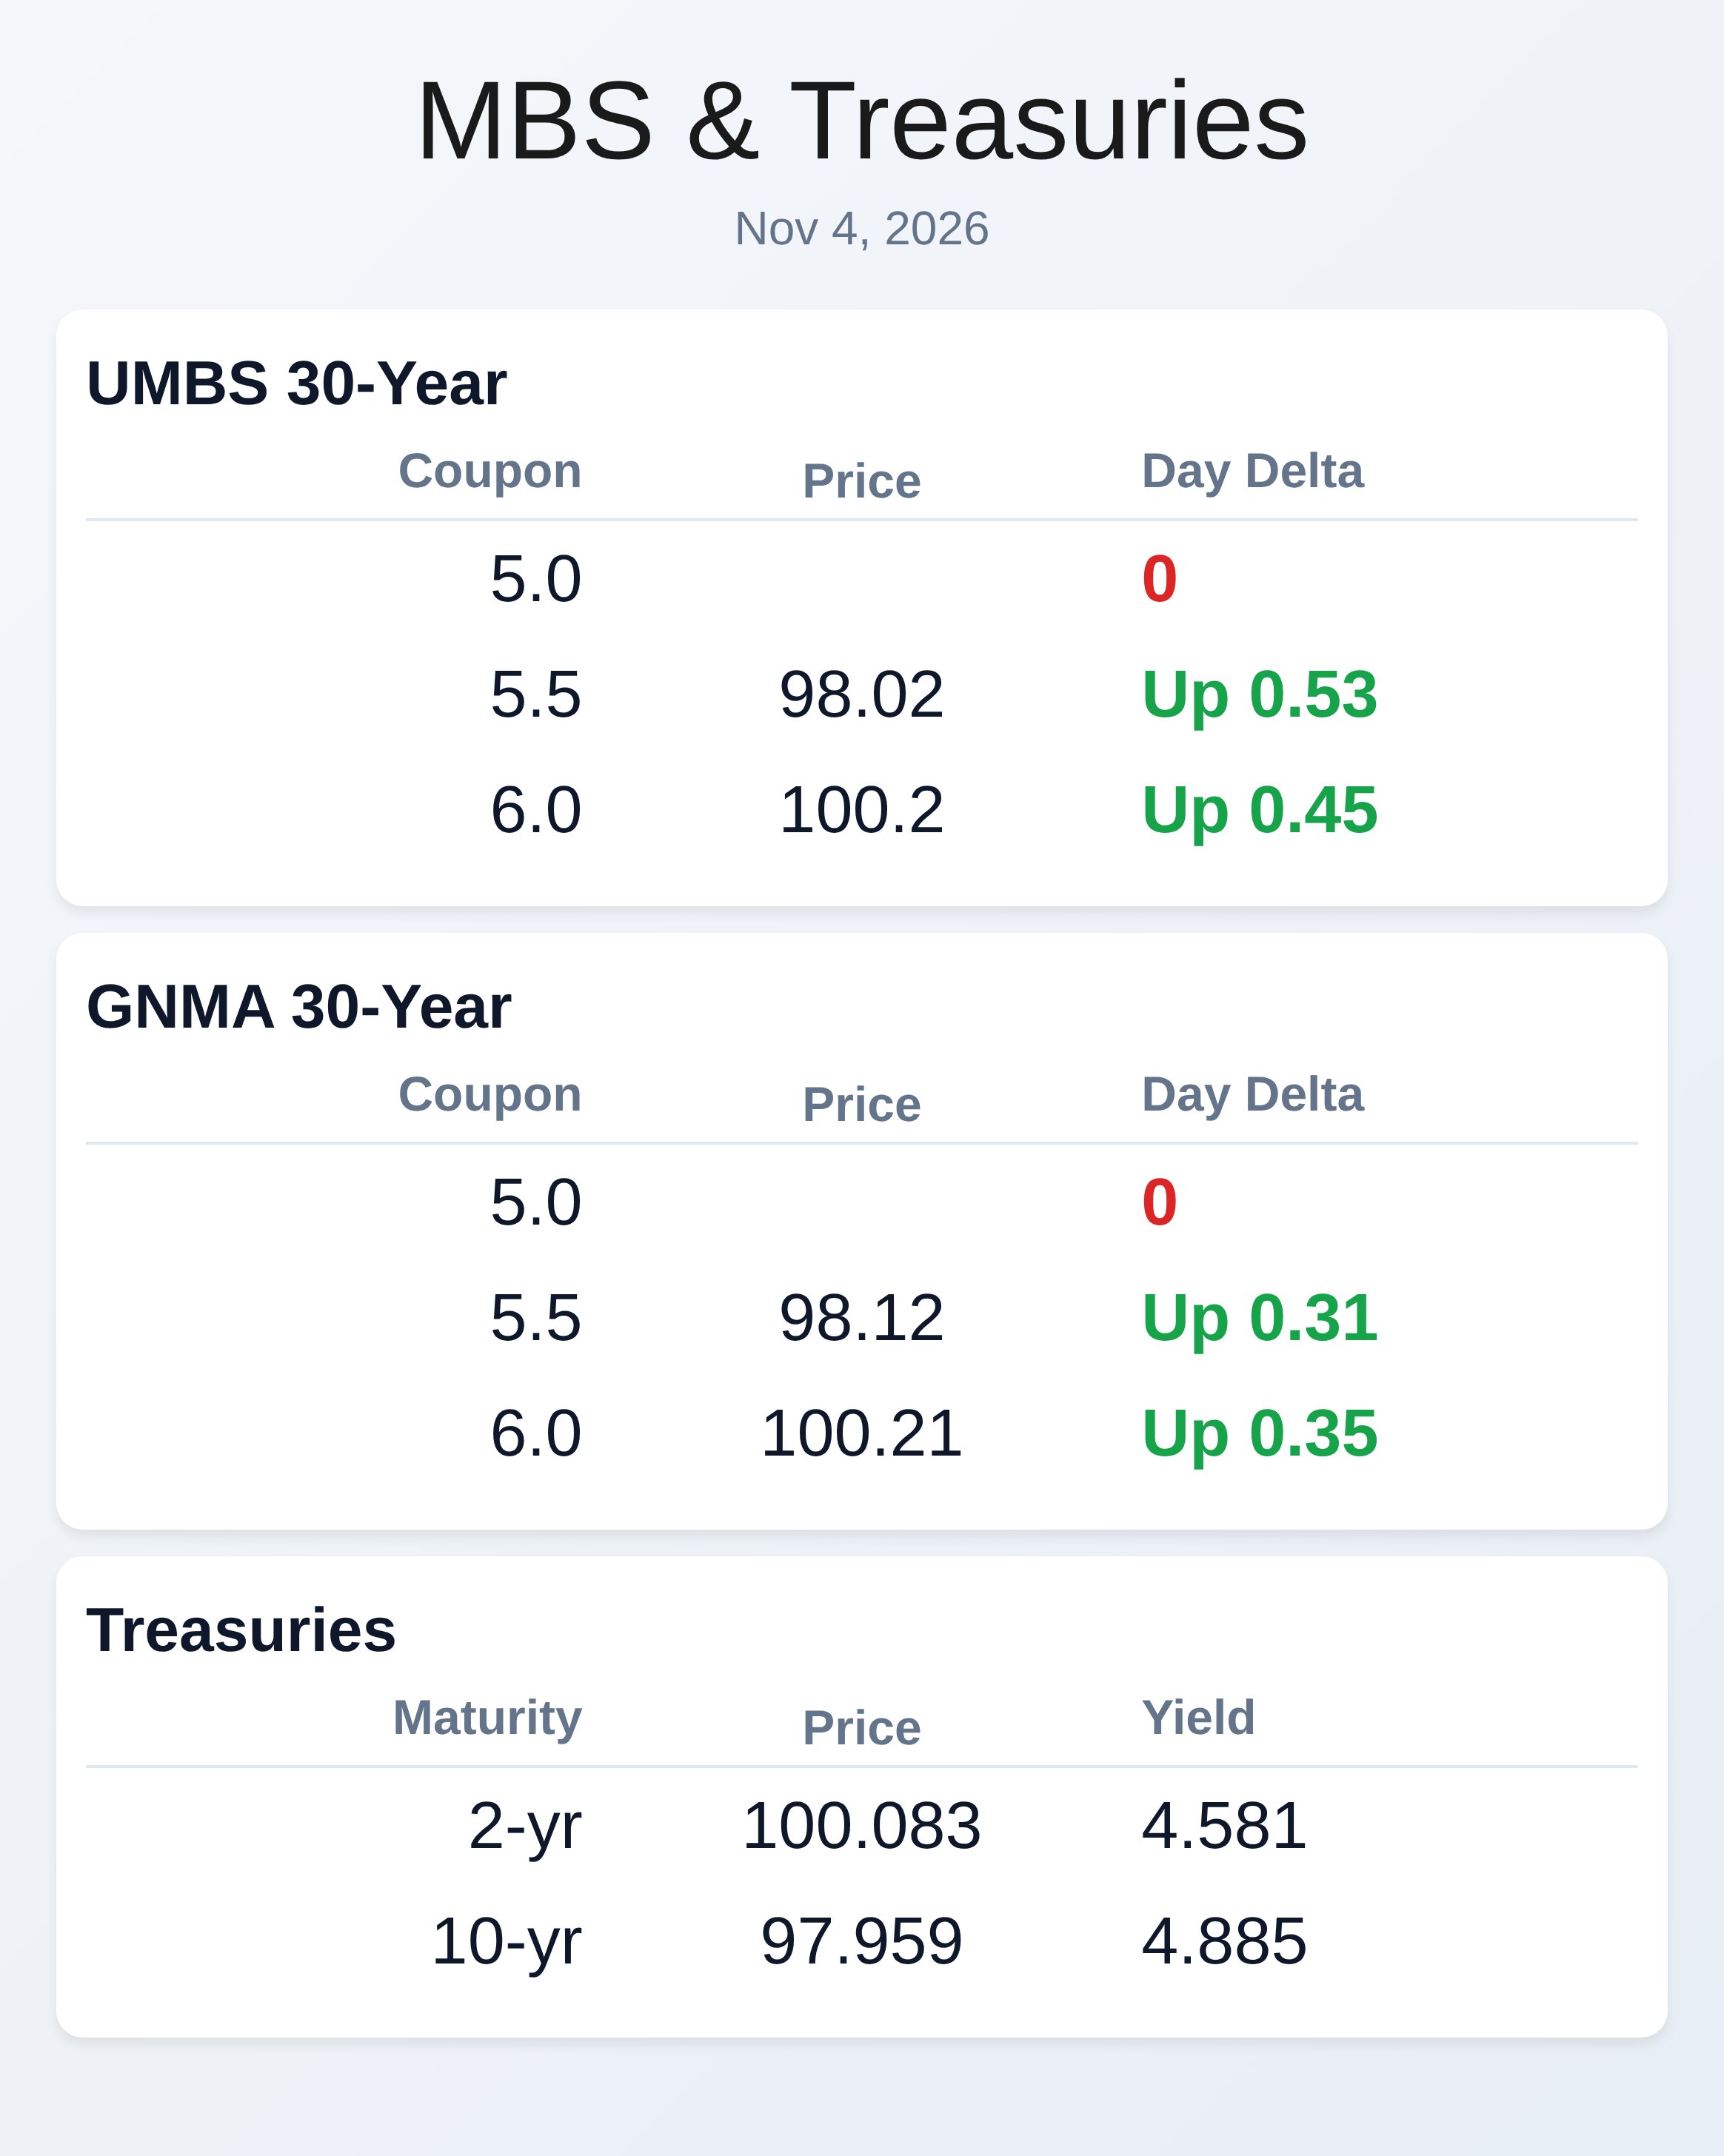
UMBS ripped higher into the close, with 30-year 6.0s up 50 ticks to 100.24 as the 10-year Treasury yield fell about 8 bps to 4.89%. The bid was driven less by the midterm headlines and more by another sharp selloff in large “neocloud/AI” names and a ~$20 slide in oil since Friday. That combo rekindled a safety bid across the curve and pushed rate sheets better in the afternoon.
For originators, it’s the cleanest improvement in several weeks, but it still looks tactically fragile. Ginnie Mae performance joined the rally, with 30-year GNMA 6.0s up 0.38 to 100.24. FHA/VA locks benefited as spreads held in and volatility cooled, helping buydown math pencil a bit better.
Pipeline takeaway: today favored rate-term scenarios and clean FHA/VA files, while cash-out remains price‑sensitive. The 10-year’s break back into the high‑4.8s is welcome, but context matters. Recent rallies have depended on tech jitters and oil softness more than a broad, durable “lower inflation” narrative.
Without confirmation from next week’s data, a quick retest of 4.95–5.00% is still in play. Treat this as an opportunistic dip, not a new trend—yet. Earnings underline the operating reality.
UWM swung to a $213M profit primarily on smaller servicing/hedging hits and expense cuts, even as volume slipped and gain-on-sale narrowed. Pennymac posted $29M overall, but production turned negative while servicing carried the quarter and MSR sales were teed up to trim debt. Translation for sellers: margins remain thin, execution discipline and coupon selection matter, and MSR is the ballast.
Demand remains tentative despite modest rate relief. MBA-reported purchase apps fell again and are roughly 19% below last year, while refi remains pinned by the massive low‑coupon cohort. ARM share continues to creep up as payment‑hungry buyers hunt for incremental savings and sellers increasingly negotiate concessions over price cuts.
Credit policy continues to evolve beneath the surface. Several lenders report early borrower savings from broader use of alternative scores in agency funnels, but investors will want more performance data before repricing credit risk en masse. Expect uneven adoption across channels, and price each loan to the best final takeout, not just the first DU/LPA pass.
**Locking vs Floating**
The rally looks more “tech jitters + oil drop” than a confirmed macro turn; it’s a tactical gift, not a green light. For near‑term closings, locking into the improved 10‑year range with triggers near 4.95%/5.00% makes sense, as a quick reversal is possible without supportive data. More risk‑tolerant pipelines can float selectively, but only with firm stop‑loss rules and attention to coupon liquidity.
In short: lock the wins you need, float the basis you can defend, and keep buydowns hedged.
**Today’s Events**
ADP jobs (Oct): 86K vs 69K forecast, 90K prior
Trade Gap (Sep): -$105.0B vs -$108B forecast, -$105.6B prior
S&P Global Composite PMI (Oct): 55.9 vs 57.6 forecast, 58.4 prior
S&P Global Services PMI (Oct): 56.1 vs 57.9 forecast, 58.8 prior
ISM Services Business Activity (Oct): 53.8 vs 56.5 prior
ISM Non‑Manufacturing PMI (Oct): 54.5 vs 54.8 forecast, 54.9 prior
ISM Services Employment (Oct): 51.4 vs 50.1 prior
ISM Services Prices (Oct): 73.0 vs 74.0 prior
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |