**WTMS Blog Today = What’s up in Mortgage Today (AM) – 11/06/2026**
Bonds are backpedaling after a hot jobs print: October nonfarm payrolls rose 165k with unemployment at 4.1 percent and wages up 0.4 percent month-over-month, pushing the 10-year near 4.90 percent and pressuring MBS. This follows a week where falling oil and post-election “gridlock” vibes fueled a bull flattening and multi-week yield lows. Volatility remains elevated as AI-related equity swings and crude headlines tug rates in both directions.
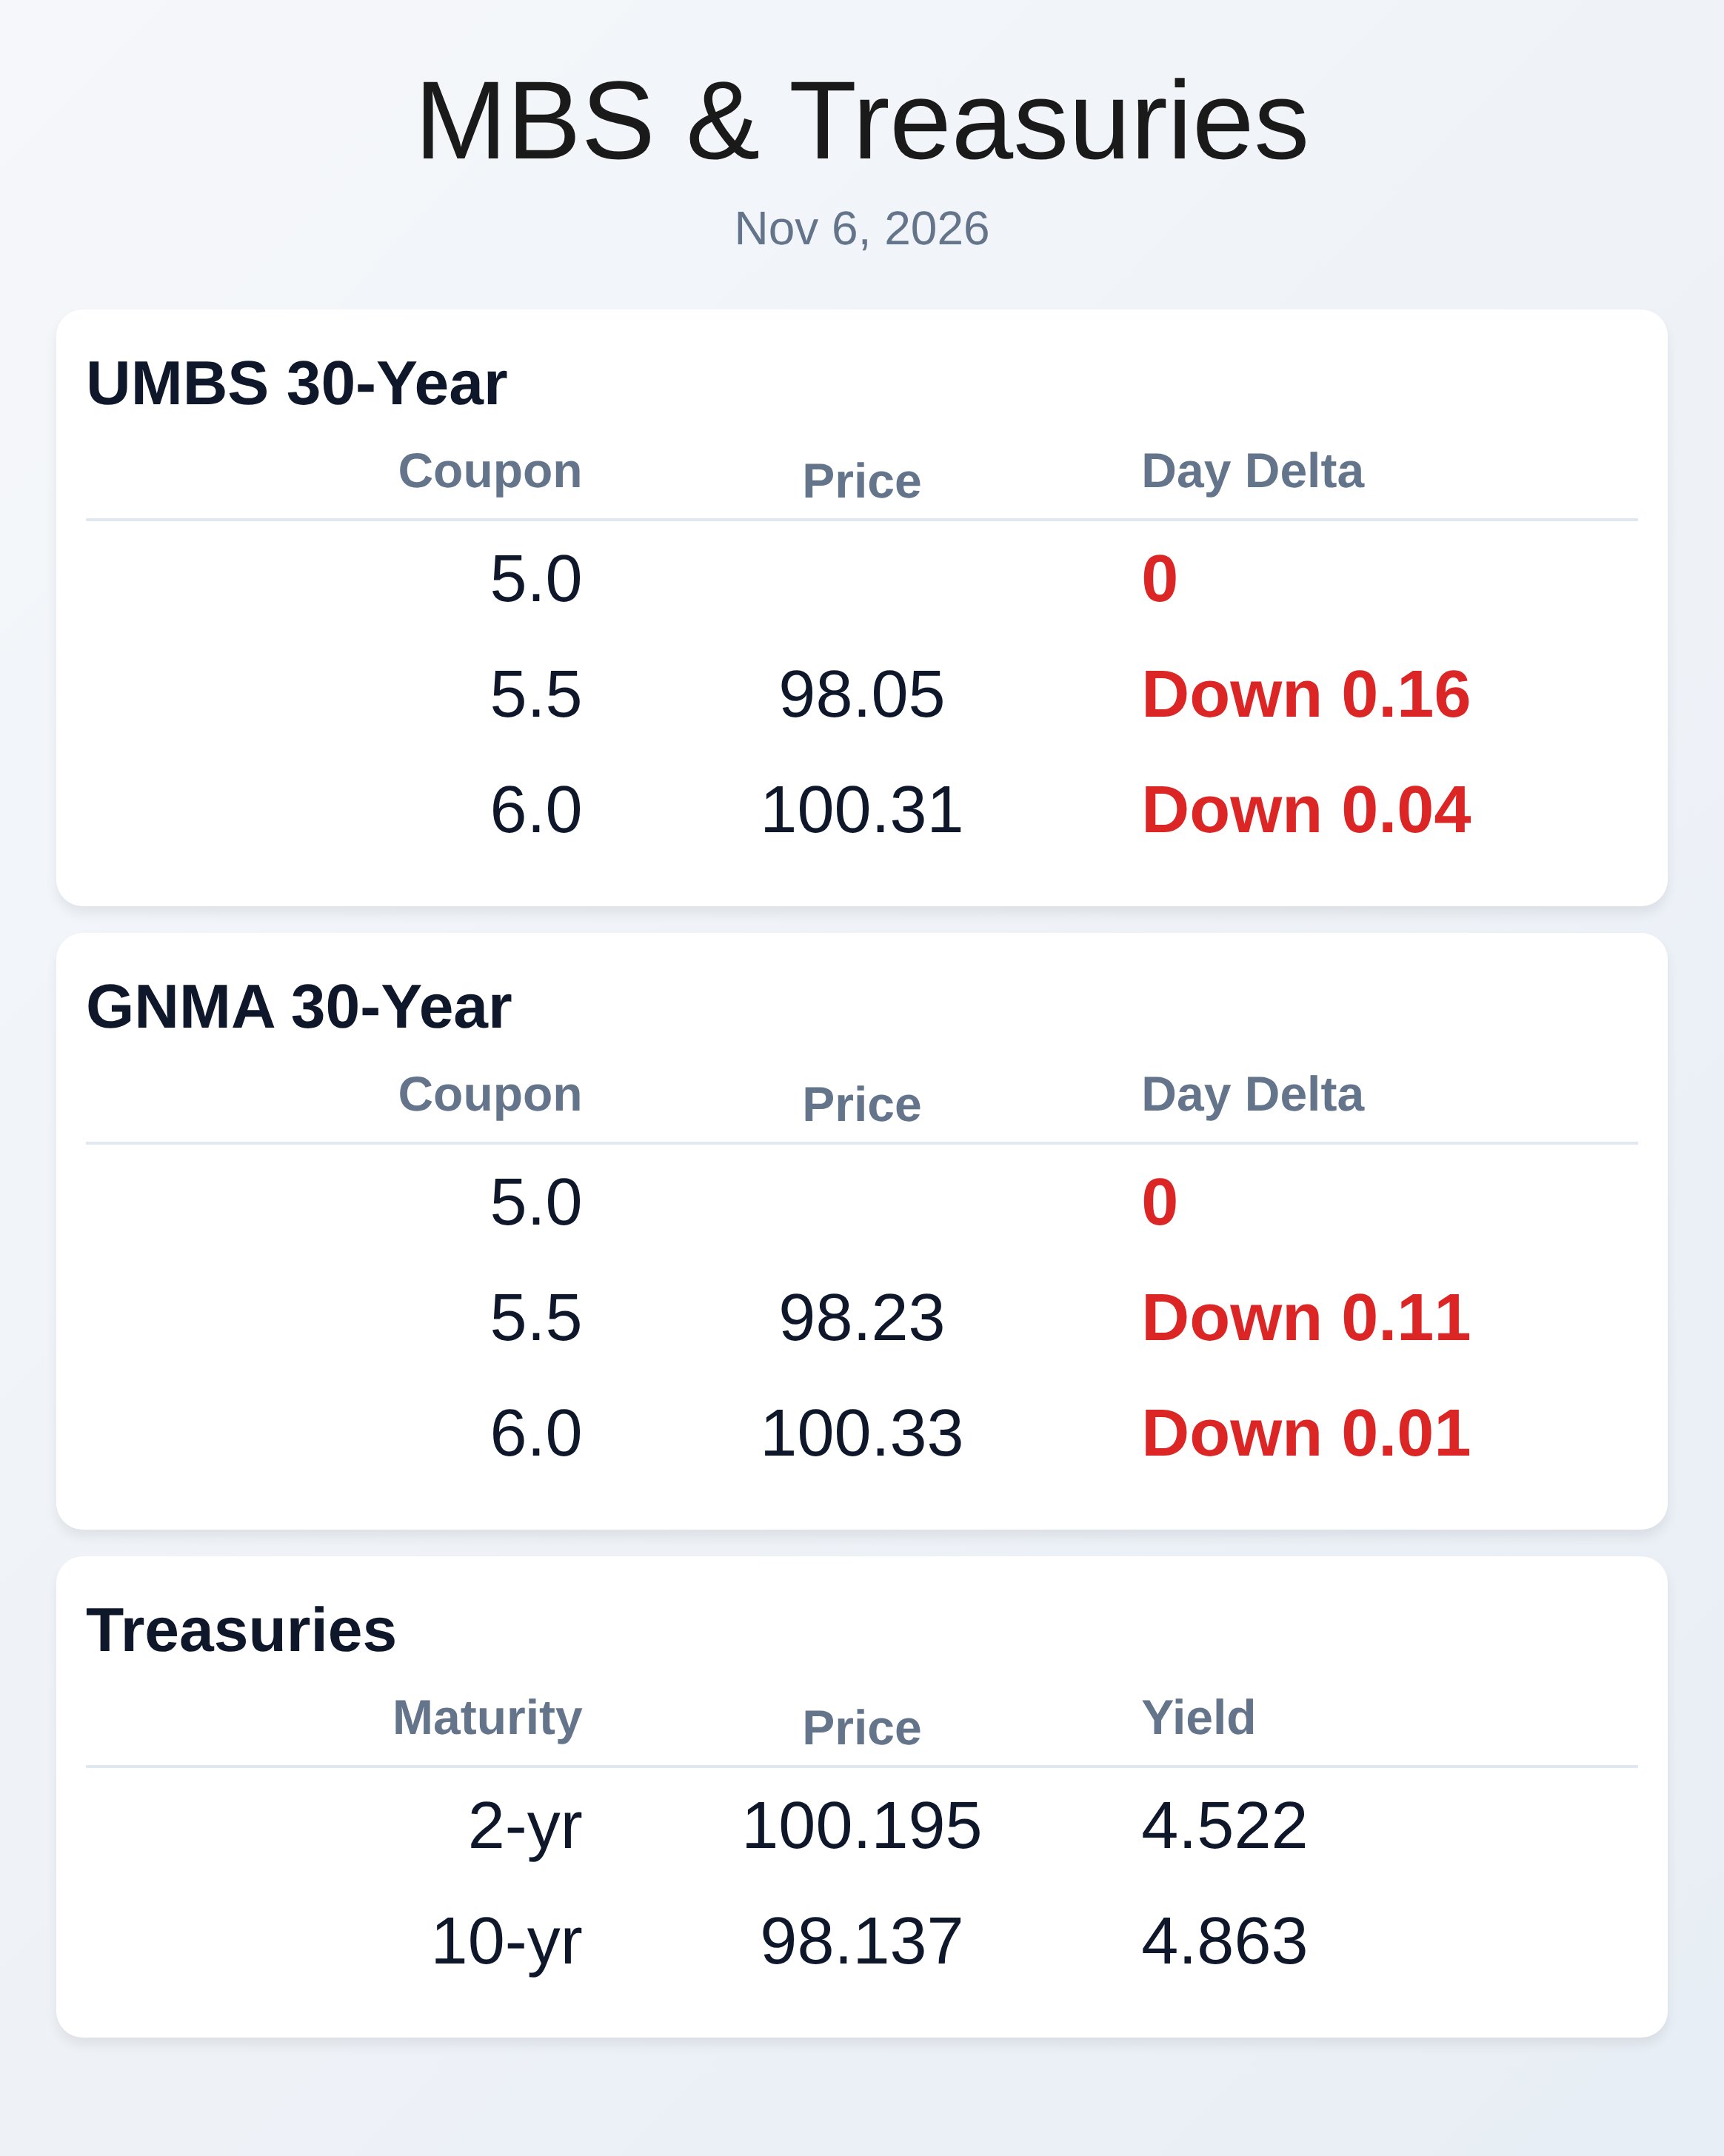
For lenders, this is a classic “rally, then reality” week with intraday reprices tied to data and risk sentiment. Expect wider rate sheet dispersion as desks manage headline risk into the weekend. UMBS production coupons are modestly weaker to start, giving back a slice of this week’s gains after Thursday’s steadier tone.
Earlier sessions saw the best marks since mid-September as 6.0s and 6.5s caught a bid, but today’s payrolls-induced selloff has trims running a few ticks to a quarter point. Payups in smaller-balance and prepay-favorable cohorts held up through midweek, though bid-ask remains choppy when rates lurch. Primary/secondary spreads haven’t fully followed Treasuries, so consumer rate relief trails benchmark moves.
Liquidity remains thinner on coupon transitions and into refunding supply next week. GNMA performance is again under the microscope as FHA credit signals diverge from GSEs. TransUnion reported FHA loans at 60+ DPD now comprise 47.2 percent of serious delinquencies, the highest share in 20+ years, while GSE and jumbo delinquency rates remain comparatively stable.
That mix continues to shape Ginnie coupon stack behavior and servicer advance strategies. For lock desks, GNMA concessions can widen on risk-off days and compress when oil slides and haven demand returns. Watch for relative value to toggle as MSR hedgers recalibrate to slower speeds and seasonal prepay drift.
The 10-year Treasury has traversed a wide range in days: from sub-4.85 percent midweek on oil’s $10 drop and a post-election “constrained fiscal” narrative, back toward 4.90 percent after stronger labor data. Jobless claims of 189k and solid productivity complicate the “near-term easing of pressure” story, even as refunding sizes were left unchanged. Curve moves remain a function of safe-haven flows, AI-equity risk, and energy—any stabilization in tech or crude can nudge yields higher.
Net-net, the market is back to data dependence with headline volatility dictating intraday direction. On the origination front, Q2 originations rose 12.8 percent year over year to roughly 1.5 million, with purchases up 7.1 percent and refis up about 40 percent; HELOCs climbed 20.3 percent, per TransUnion. ARM share reached 11.3 percent recently as borrowers chase payment relief, and lenders are leaning into home-equity as the best recapture lever in a rate-locked world.
Zillow Home Loans’ new forgivable 3.5 percent FHA down-payment second underscores how acquisition platforms are using DPA to retain buyers inside their ecosystems. Competitive dynamics continue to favor faster, clearer pricing and execution over pure rate alone. Expect product mix to keep doing the heavy lifting while volume stays seasonally fragile.
Housing activity remains soft: Realtor.com reports October contract signings at a record low for the month, with active listings up 7.4 percent year over year but new listings down 7.5 percent and median asking prices off 2.2 percent. Builders are still relying on buydowns and incentives, but affordability is dominated by taxes, insurance, and utilities as much as rates. With inventory clearing more than surging, lenders should arm agents with payment options (ARMs, temporary buydowns) and equity strategies to convert fence-sitters.
Pipeline discipline and borrower communication matter more than ever when macro swings whipsaw eligibility and pricing within hours.
**Locking vs Floating**
With the rally driven more by risk-off and oil than a clean disinflation trend, rate gains are fragile and prone to reversal on stronger data or tech stabilization. After today’s upside payrolls surprise, bias tilts toward near-term locking on live loans inside 15–30 days.
Floats further out can work if oil resumes its slide and equities wobble, but guard against negative reprices and be nimble. In short, respect the range, harvest wins quickly, and don’t let a good rate sheet turn into a hope-and-pray float over the weekend.
**Today’s Events**
October Nonfarm Payrolls, Unemployment Rate, and Average Hourly Earnings (released)
November University of Michigan Consumer Sentiment (prelim)
September Consumer Credit
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |