**WTMS Blog Today = What’s up in Mortgage Today (AM) – 11/11/2026**
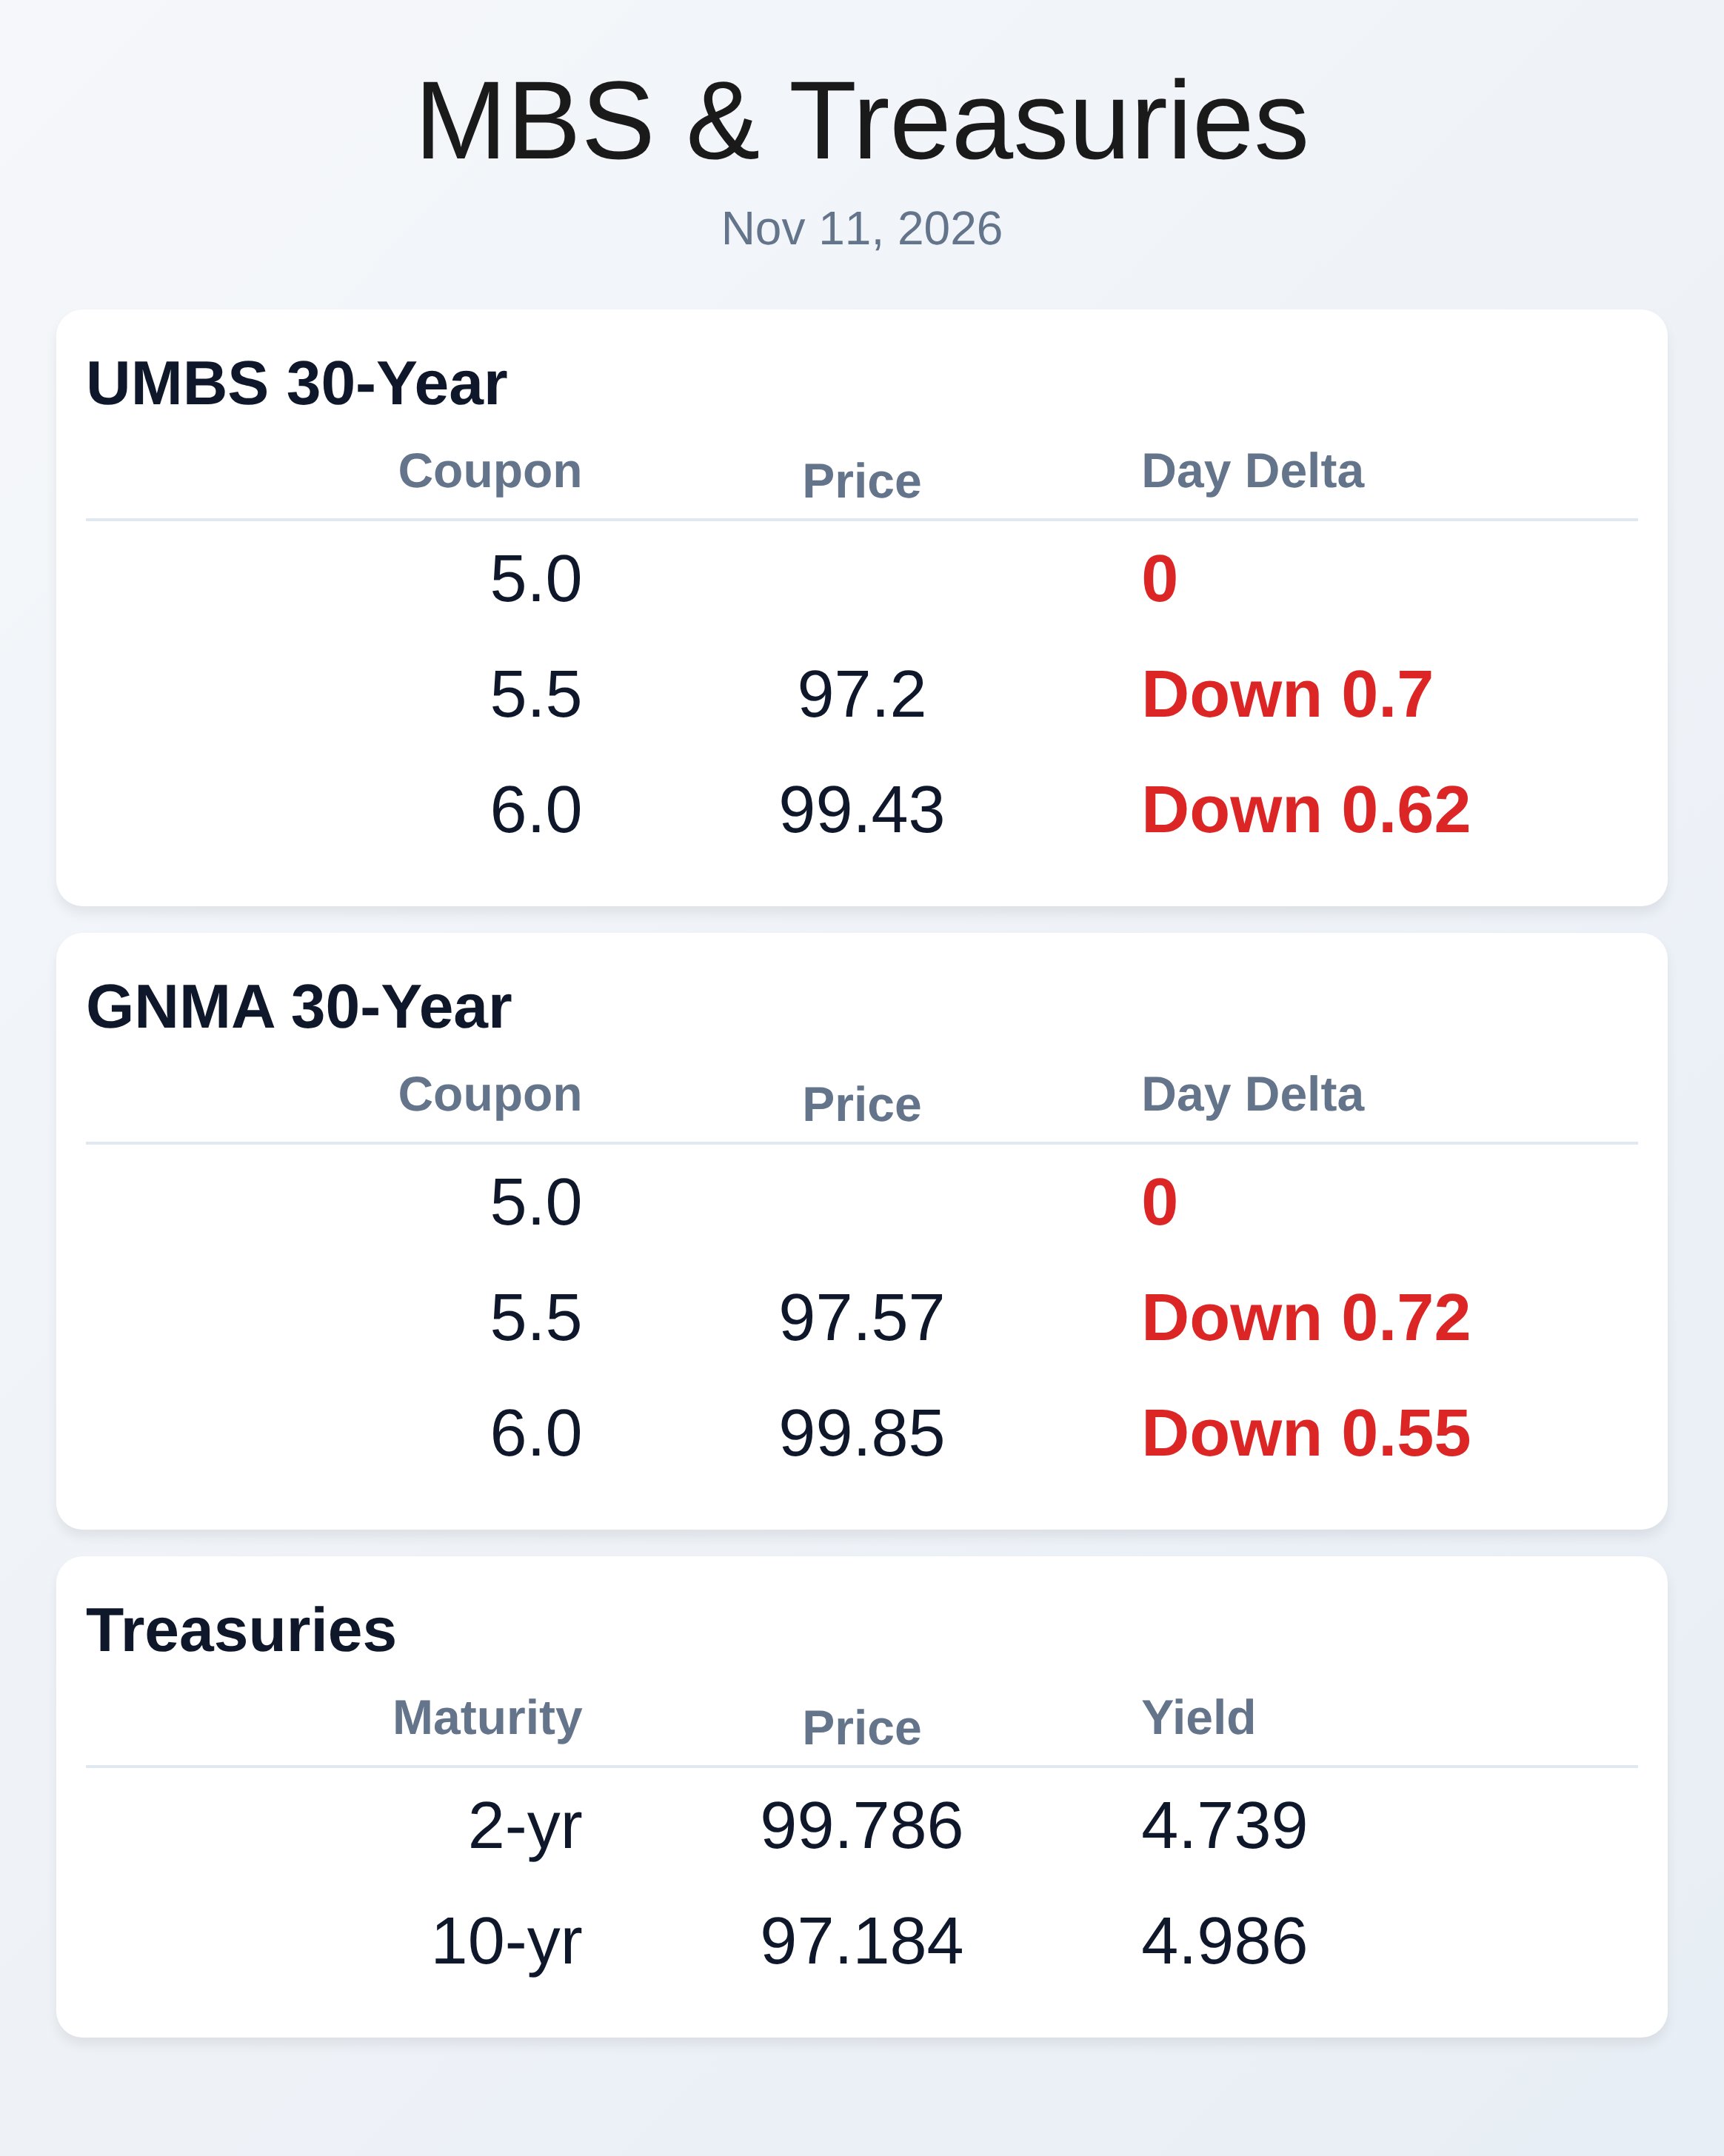
Bonds are catching their breath after Tuesday’s hotter CPI (+0.4% headline, +0.3% core) revived rate-hike odds and pushed the 10-year back toward 5.00%. UMBS prices slipped on the print, with production coupons lagging Treasuries as volatility picked up and liquidity thinned into the holiday. With the bond market closed today for Veterans Day, lenders should expect limited or static rate sheets until trading reopens.
Near term, auction supply and Friday’s PPI will steer the next leg. Bigger picture, last week’s five-week rally bent but didn’t fully break. Ginnie Mae remains the growth engine: it’s 42% of agency issuance year-to-date and reached 47% in October as FHA/VA outpaced conventional.
That tilt matters for pipelines and servicing, given slower seasonals, slightly higher delinquency sensitivity, and cash-flow timing. VA volume deserves a nod today: zero-down remains a powerful tool, even as affordability tightens. Prepay speeds softened again in October, reducing convexity risk but stretching MSR cash flows.
Expect investors to keep favoring specified pools with cleaner VA/FHA attributes. The 10-year’s round-trip near 5.00% has been fueled by hawkish Fedspeak (Waller opened the door to a December move), hotter CPI, and soft auction demand. Real yields remain elevated, keeping mortgage spreads sticky even when Treasuries rally.
Oil’s retreat helped briefly, but the inflation trend still rules the tape. Until core inflation convincingly cools, the market will fade rallies on strong data and thin liquidity days. Translation: volatility remains a feature, not a bug.
Origination mix keeps shifting to where execution lives. ARM share climbed to 17%—the highest since 2019—as buyers trade rate for payment relief and future refinance optionality. HELOCs remain ascendant on record tappable equity, giving lenders a durable recapture lane while first-lien refi incentives stay scarce.
Non-QM grows as product fit, but execution discipline is paramount; bid/ask and pool sale risk can erase thin gains. Credit-score modernization is here too: VantageScore 4.0 vs. FICO 10T choices carry pricing, hedging, and investor-acceptance implications.
Housing demand remains rate sensitive: contract signings fell to a record-low October pace, even as inventory improved and asking prices edged down. Competitive pressures are shifting to cash-to-close, not just rate. That’s why programs like Zillow’s FHA down-payment assistance (forgiving second) matter—they change the math on borrower eligibility and lender win rates.
Expect more lenders to pair buydowns, DPA, and ARMs to keep purchases moving through year-end. Execution and education will separate winners. Playbook for today: with markets closed, focus on file quality, pricing exceptions discipline, and Monday’s pipeline posture.
For VA and FHA pipelines, recheck AUS after CPI and confirm MI/DPA math still appraises cleanly. For HELOCs, compress cycle time—speed is winning share. And prep talking points now for Friday’s PPI and next week’s refunding supply, when rate sheets will need quick lock decisions.
**Locking vs Floating**
Post-CPI, the path of least resistance is choppy and upward for yields, with rallies prone to fade on strong data or supply. If recent improvements meet borrower goals or price exceptions are stacking, bias to lock on strength rather than gambling into PPI and next week’s auctions. Floating only makes sense with tight triggers, clear milestones, and minimal fallout risk.
Production coupons are underperforming on volatility—assume headline sensitivity remains high. In short: protect wins; don’t chase dimes into data.
**Today’s Events**
– Veterans Day: U.S.
bond markets closed; rates likely static until trading reopens
– No major economic releases scheduled; next key data is Friday’s PPI and University of Michigan Sentiment
Subscribe free at WellThatMakesSense.com to get this in your inbox each morning.