**WTMS Blog Today = What’s up in Mortgage Today (PM) – 11/10/2026**
Hotter CPI ended the early‑November bond rally, sending mortgage bonds and rates sharply the wrong way. Traders shed the “tech-jitters” safe‑haven trade and repriced for more Fed restraint. The move resets near‑term momentum and puts the recent downtrend in rates at risk.
Volatility is elevated into the mid‑week holiday. Expect choppy price action around liquidity pockets. UMBS led the downturn as front‑end Treasury yields surged on the inflation surprise.
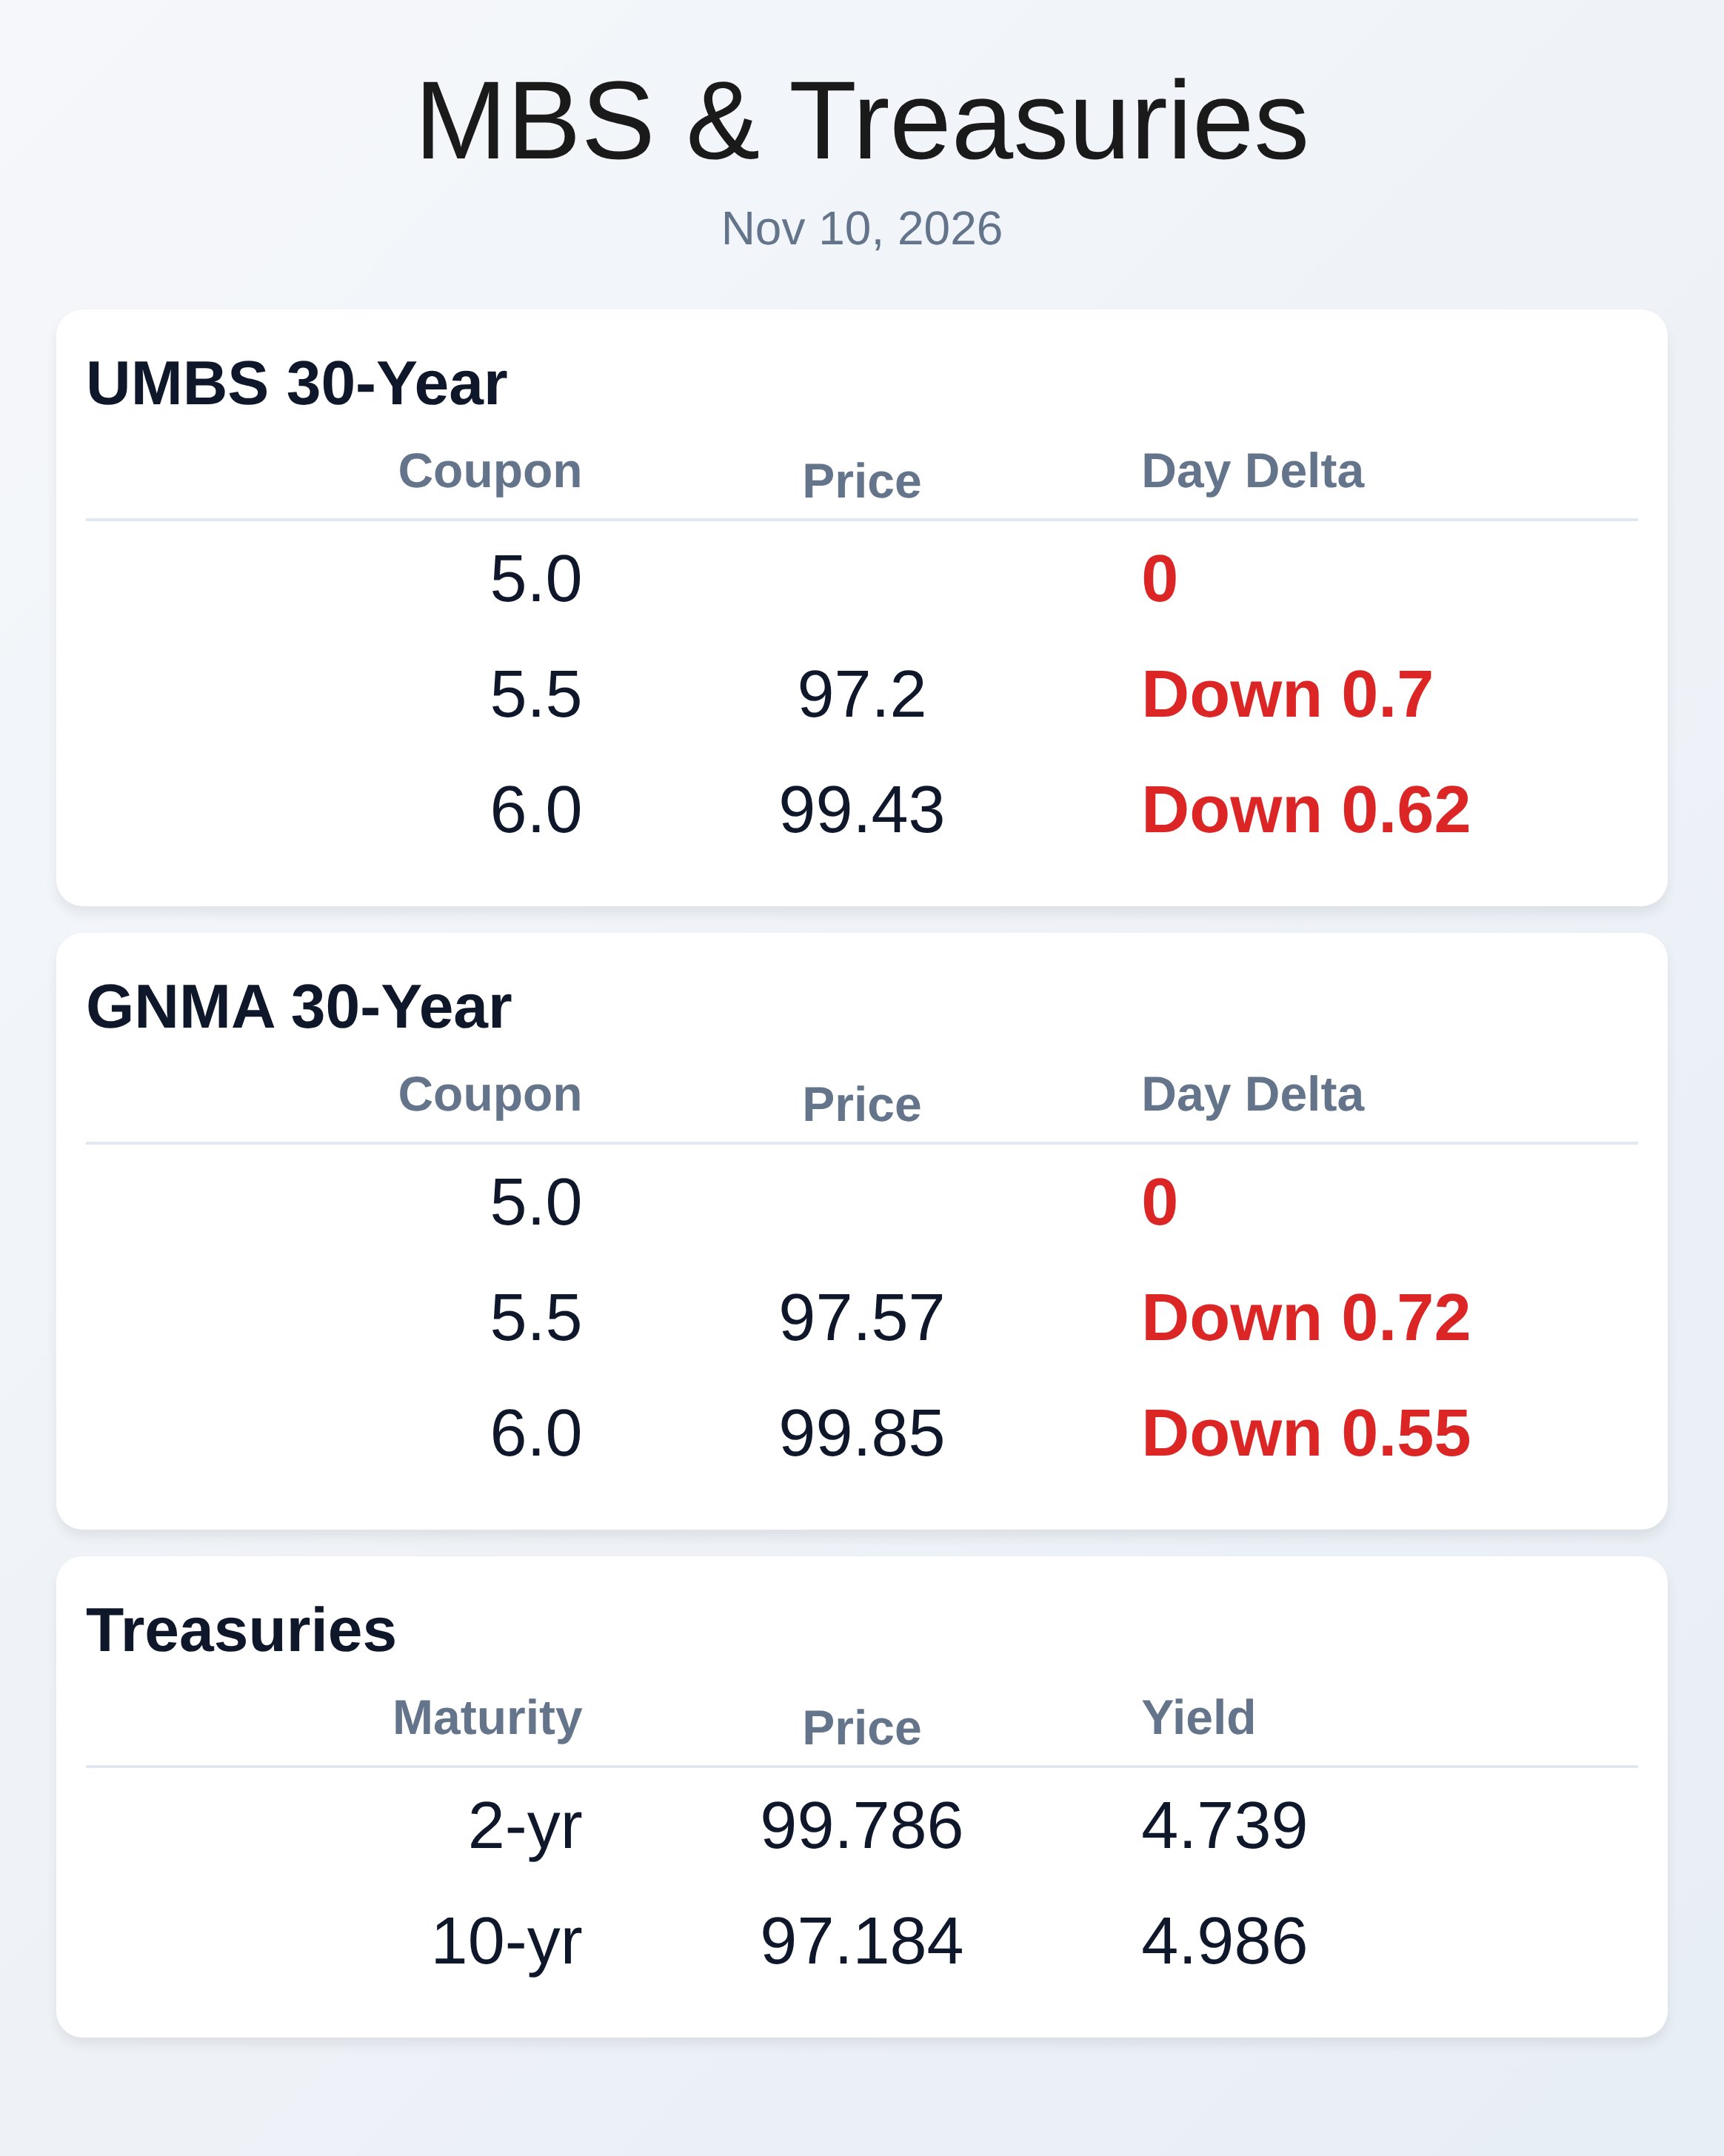
By the close, 30‑year UMBS 6.0 fell 62 ticks to 99.43, while the 10‑year Treasury yield jumped roughly 10 bps to 4.98 percent. Losses were broad across coupons and GNMA stacks, with Ginnie 6.0 down 59 ticks. Fed‑funds futures nudged higher for December hike odds, reflecting the stickier inflation profile.
Bid/ask and liquidity widened intraday before stabilizing late. Context matters: last week’s rally rested on AI/tech credit fears and slumping oil, not on softer inflation. With that cover fading today, the market refocused on the Fed’s inflation mandate.
A mid‑week holiday can distort flows, so follow‑through may be uneven. A durable trend reversal likely needs either renewed tech stress or unequivocally softer inflation data. Until then, respect the range and trade defensively.
On the origination front, modest rate relief into early November didn’t lift activity much. MBA data showed purchase apps slipping again, while Mortgage News Daily’s rate index hovered in the low‑7s (about 7.30–7.37 percent). Adjustable‑rate share pushed to a yearly high as borrowers hunt payment relief.
Turn times and pricing discipline matter more than ever with secondary spreads still sensitive to volatility. Expect intraday reprice risk to stay lively. Servicing strategy remains pivotal as equity‑driven refis dominate what little refi volume exists.
ICE estimates homeowners hold a record $17.5 trillion in tappable equity, yet servicers retained only 27 percent of refinancing borrowers last quarter. Cash‑out transactions are the main runoff driver. Lenders with strong database monitoring, HELOC/cash‑out options, and timely outreach will win more of that business.
Housing remains a tale of leverage, not lift. Inventory has improved and buyers are negotiating more, but pending sales and contract signings continue to lag. Payments rose ~13 percent year‑over‑year even with largely flat prices, keeping affordability strained.
For originators, that favors precise structuring: concessions, buydowns, and ARMs tailored to borrower cash‑flow constraints.
**Locking vs Floating**
Today’s CPI upside puts the recent rate rally at risk, so near‑term closings should favor locking on morning strength and avoiding late‑day whipsaws. Tactical floaters need tight triggers (e.g., 10‑year holding below 4.93–5.00 percent) and a willingness to lock quickly on adverse moves.
A sustained leg lower in rates likely requires fresh downside surprises in inflation or renewed tech/AI credit stress. Expect elevated intraday volatility around the mid‑week holiday and data headlines; keep pipeline hedges snug and be selective with premium pricing.
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |