**WTMS Blog Today = What’s up in Mortgage Today (PM) – 11/06/2026**
Bonds held up better than expected after a hotter jobs print, with UMBS 6.0 essentially flat and the 10-year Treasury yield only slightly higher. October nonfarm payrolls rose 165k with unemployment at 4.1%, outcomes that would typically pressure rates more. The restrained move caps a week where rates improved on tech-sector stress and lower oil.
Into the close, pricing was steady-to-softer for conventionals while Ginnies edged up. Net: a resilient finish after a volatile week. Rates’ recent improvement still hinges on “neocloud/AI” jitters and softer oil, not a broad macro pivot.
Multiple high-profile tech names hit fresh lows this week, and that flight-to-quality supported Treasuries and MBS. Election results injected intraday swings, but bond gains continued to correlate most with tech equity pain. If tech stabilizes, the tailwind for rates can fade quickly.
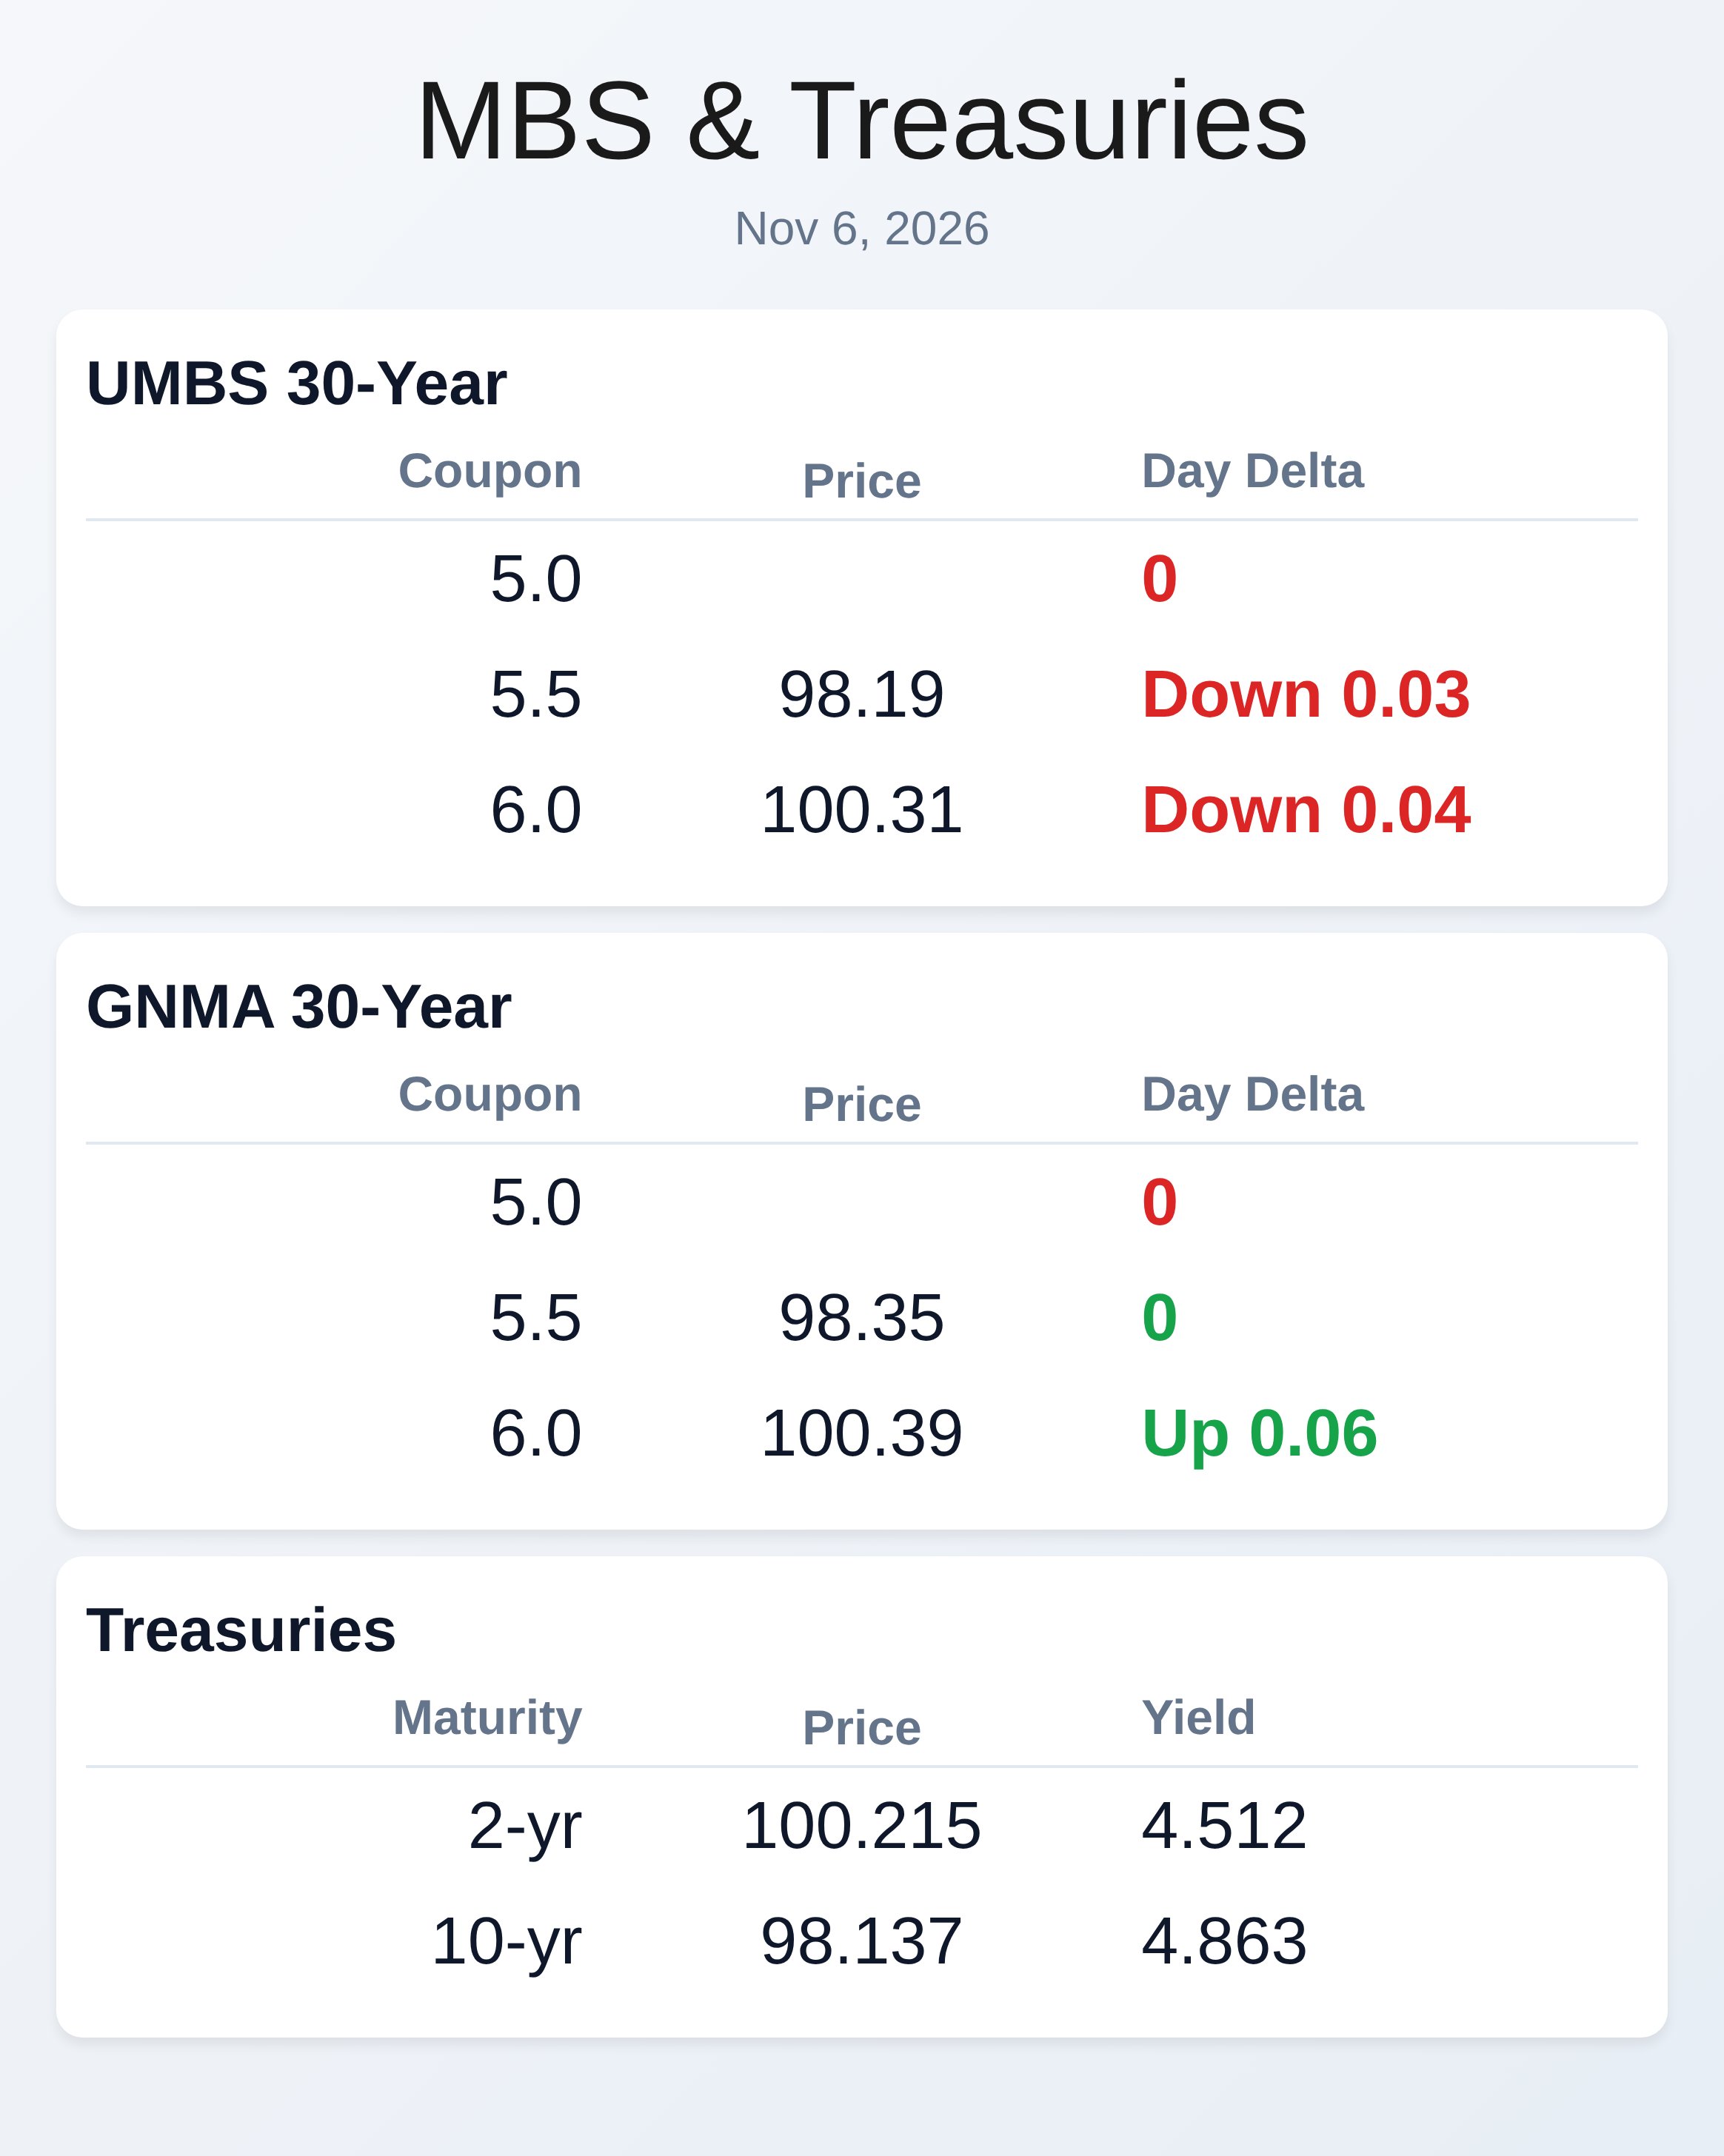
Keep expectations data- and headline-dependent. Agency MBS performance was mixed today: 30-year UMBS 6.0 hovered near 100.32 (-0.03) while 30-year GNMA 6.0 ticked up to 100.39 (+0.05). Fifteens lagged, with 15-year UMBS 5.0 down 0.18.
That pattern reflects lingering liquidity and convexity frictions at current rate levels. Spreads remain sensitive to intraday Treasury swings and any sign of rate-vol/stock contagion. The 10-year closed near 4.86%, modestly above Thursday but well below last week’s highs, even after a strong jobs headline.
Earlier in the week, refunding chatter and supply concerns added chop, but safe-haven bids offset much of that. Curve moves were consistent with a market still pricing restrictive policy for longer while allowing room for risk-off rallies. The next decisive leg likely needs either a clear inflation downshift or deeper equity/AI stress.
Originators continue to navigate a bifurcated P&L: servicing steadying results while production economics stay tight. Rocket posted a strong Q3 rebound, UWM returned to profit largely on MSR dynamics, and Pennymac reported an origination loss while servicing carried the quarter. On credit, lenders expanding VantageScore usage report measurable LLPA savings for some borrowers, but impacts vary by profile.
Takeaway: eligibility and execution are increasingly lender/model-specific—shop the file. Demand remains tepid: MBA applications slipped, with purchases down and refis essentially flat from very low levels. Redfin data show buyers gaining leverage but pending sales still sliding, underscoring affordability strain.
ARMs’ share has risen as borrowers search for payment relief at the margin. Inventory is improving in spots, yet rate sensitivity continues to dominate. Expect pipeline wins to come from precise pricing, buydown craft, and faster turn-times rather than volume tailwinds soon.
**Locking vs Floating**
Recent gains are still largely tech-jitters-driven and fragile. If you’re near rate-sheet lows or need certainty, bias to lock; the 10-year has nearby guardrails around ~4.82–4.88 support and ~4.93–5.00 resistance. Risk-tolerant borrowers can float selectively with hard triggers at those levels and a close eye on equity headlines.
Bigger, durable rate relief still needs cooler inflation or clearer growth slowing. Be nimble; reversals can come fast if stocks stabilize.
**Today’s Events**
Nonfarm Payrolls (Oct): 165k vs 65k forecast (prior 29k)
Unemployment Rate (Oct): 4.1% vs 4.2% forecast (prior 4.2%)
Participation Rate (Oct): 61.9% (prior 61.8%)
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |