WTMS Blog Today= The 10 Metro Markets Every Loan Officer Must Watch in 2026 (Yes, Really)
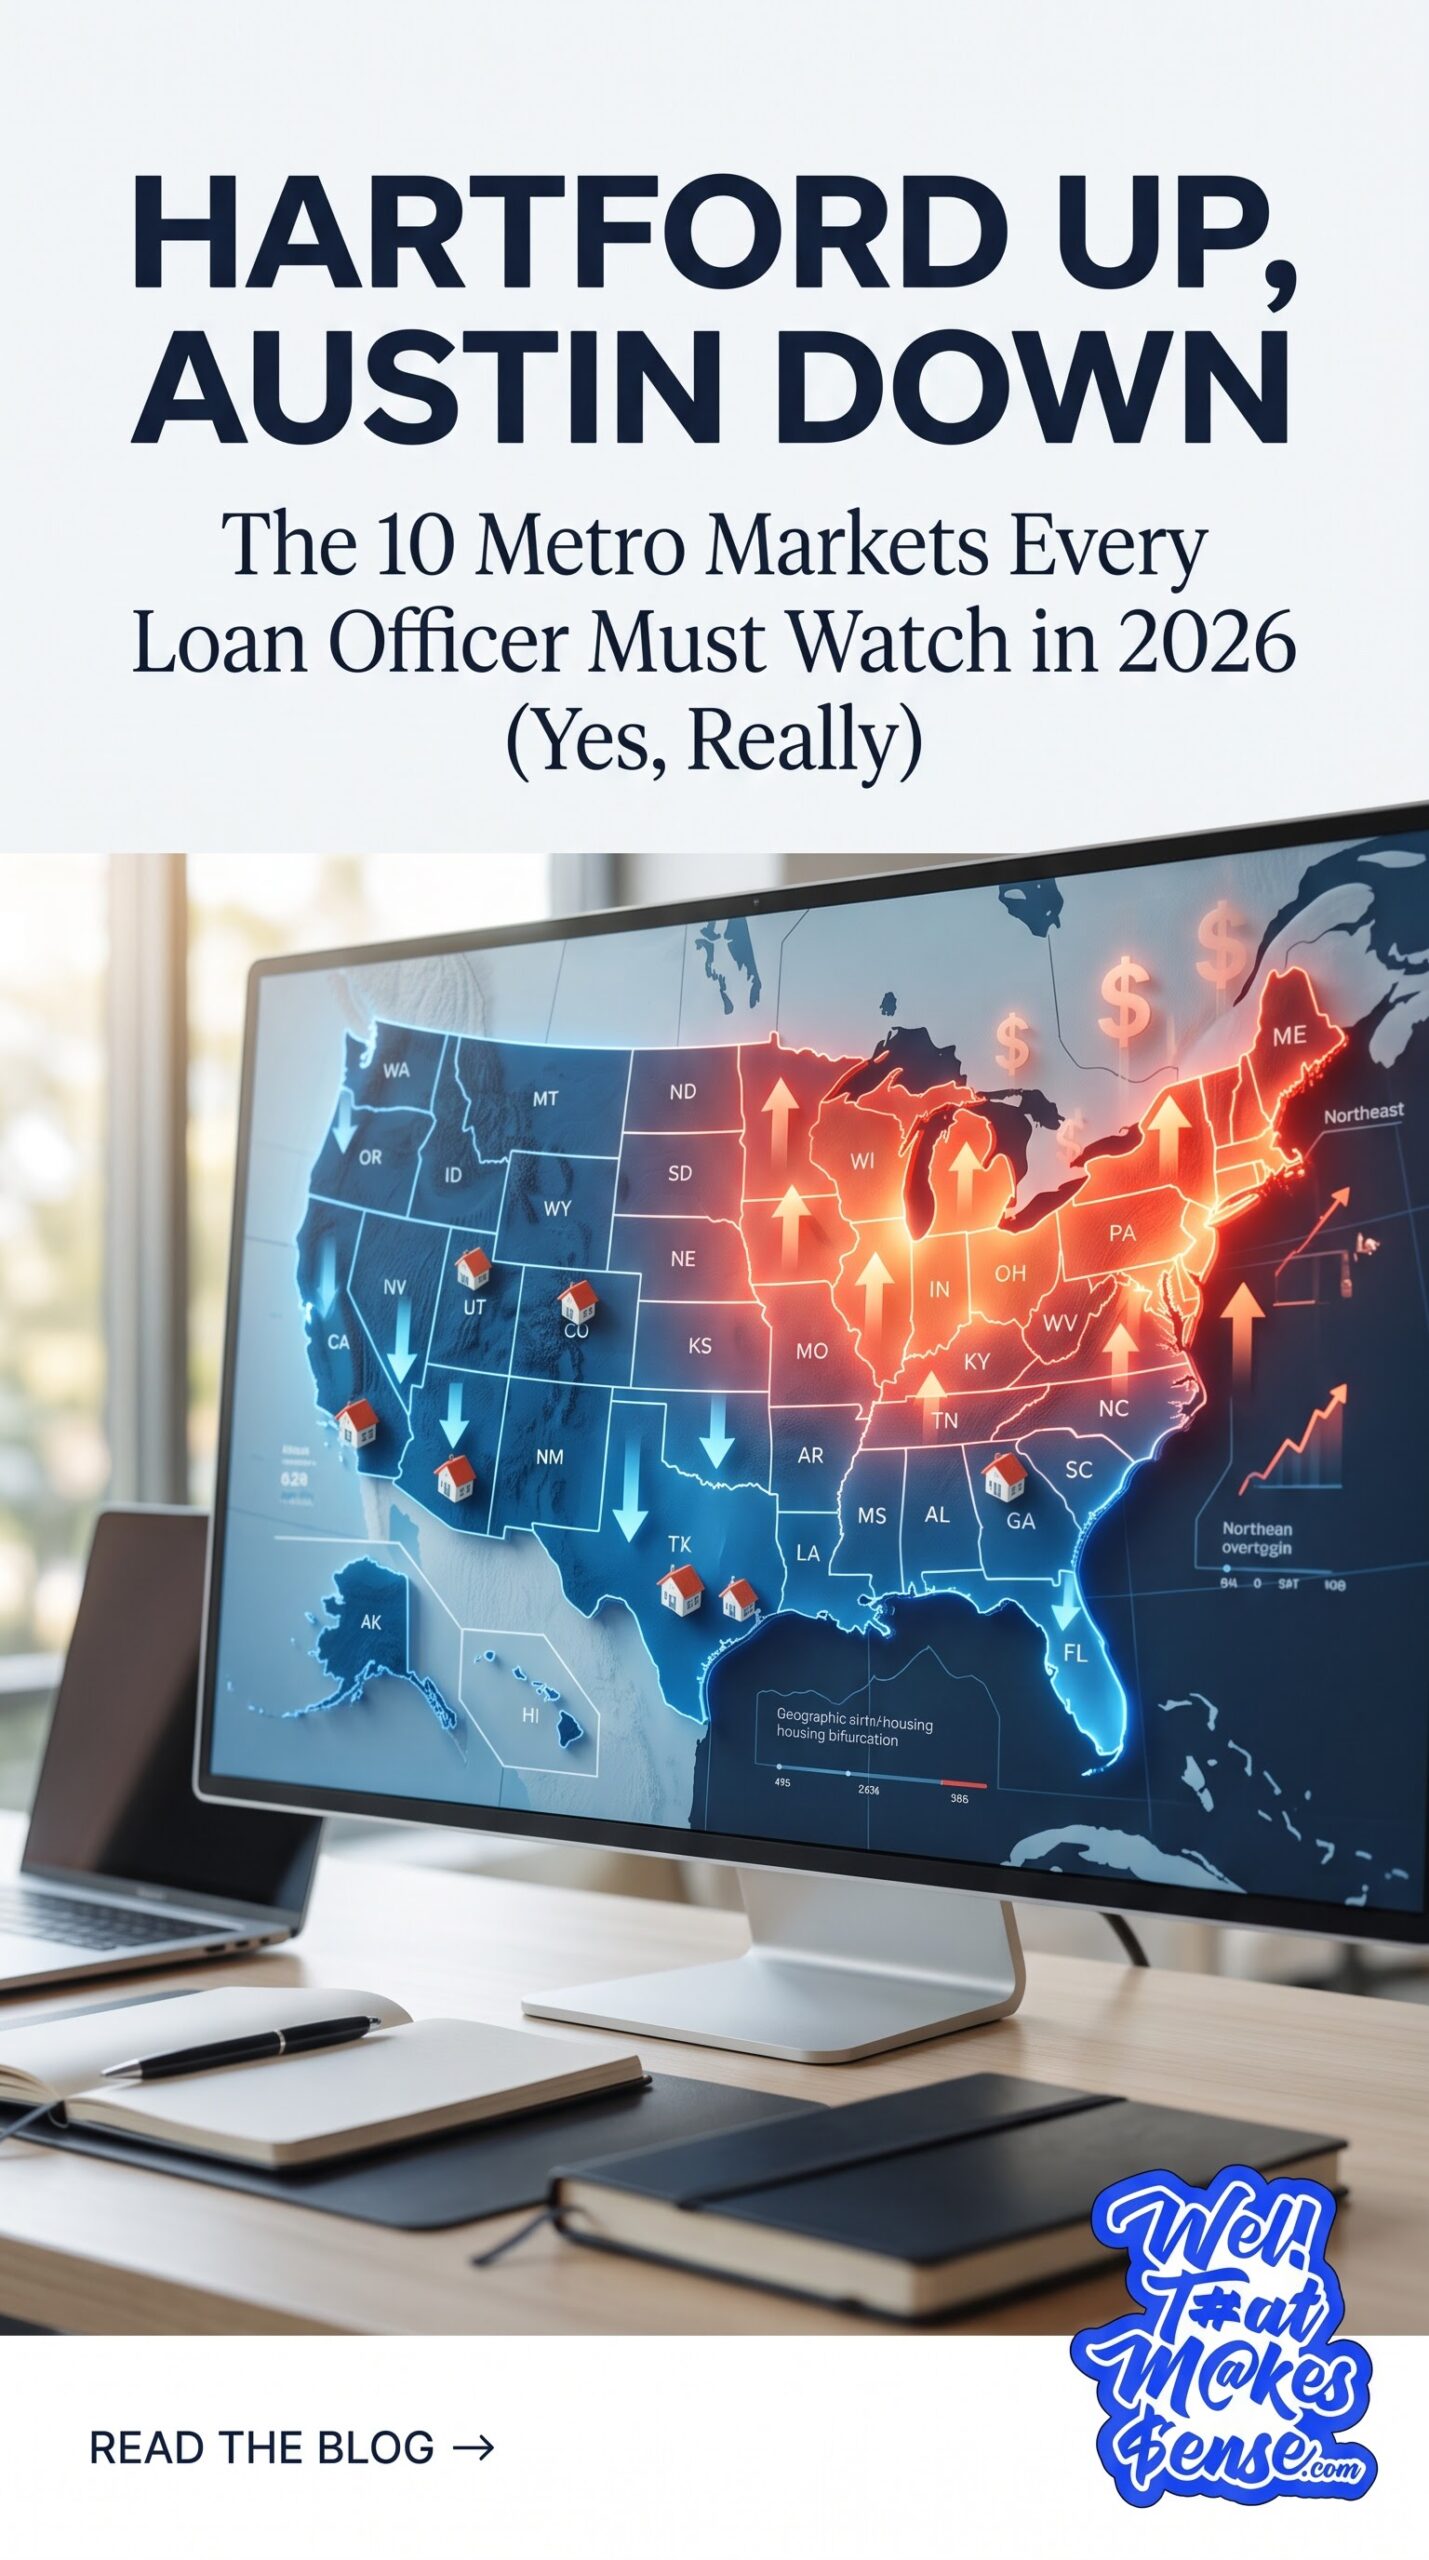
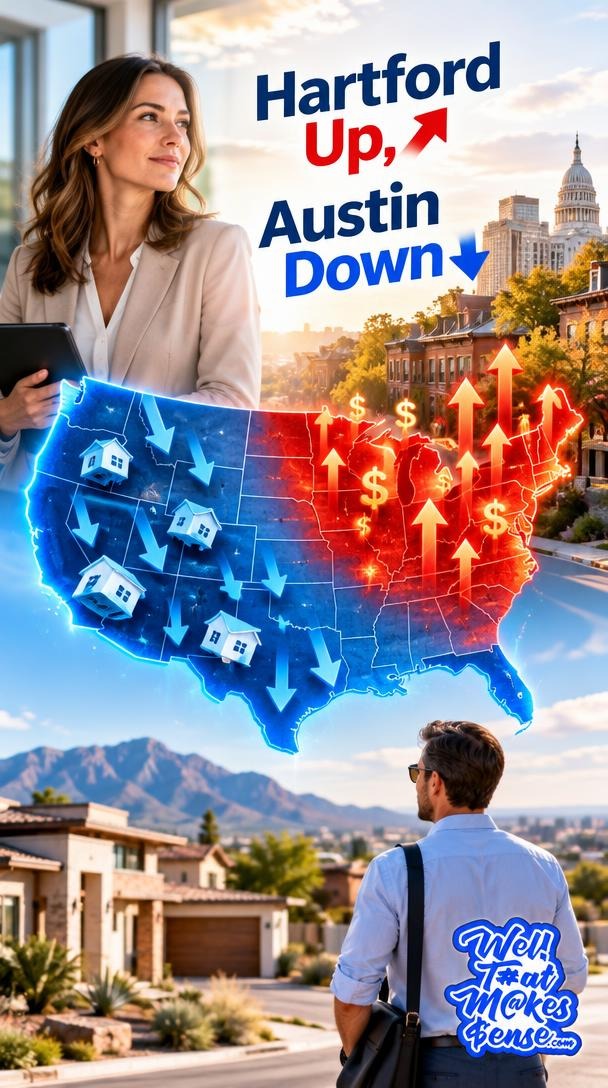
Hartford’s up 28% from peak while Austin’s down 29%—here’s where your buyers have leverage and where they’ll lose every bidding war.
Picture this: Your buyer just lost their third offer in Hartford. Meanwhile, your colleague’s client in Austin negotiated $40,000 off asking and the seller threw in a rate buydown. Same week. Same loan program. Radically different outcomes.
Welcome to the most geographically bifurcated housing market in fifteen years. According to ResiClub’s analysis of the Zillow Home Value Index, 76 of the nation’s 300 largest metros posted year-over-year price declines through October 2026—up from 54 markets just two months earlier. That’s 25% of major markets where prices are falling while the other 75% are still climbing. The gap between the strongest and weakest markets? A staggering 56.8 percentage points when you compare Hartford’s +28.0% above its 2022 peak to Austin’s -28.8% below peak.
If you’re still giving every client the same “it’s a balanced market” speech, you’re leaving closings on the table. Here’s the geographic intelligence that separates closers from order-takers.
The Five Metros Where Your Buyers Will Lose Every Bidding War
These aren’t just “hot markets”—they’re inventory deserts where pre-approvals expire faster than milk in July. ResiClub data shows these metros leading year-over-year price growth, all sharing one characteristic: active inventory remains well below pre-pandemic 2019 levels.
Hartford, CT leads the pack at +28.0% above 2022 peak. The metro never got the pandemic building boom that flooded Sun Belt markets. Inventory scarcity means your buyers need aggressive escalation clauses and zero financing contingencies if they want a chance. One appraisal gap? That’s the cost of entry, not a negotiating disaster.
Buffalo, NY and Rochester, NY round out the Northeast inventory crisis. These Rust Belt metros saw modest pandemic price increases compared to Austin or Tampa, which means less room to fall during the correction. Add in minimal new construction and you’ve got seller leverage that hasn’t budged since 2022. Your pre-approval letters need to be flawless—one whiff of weak financials and your buyer’s offer hits the recycling bin.
Midwest metros like Grand Rapids, MI and certain Illinois markets complete the top five. The common thread isn’t weather—it’s that builders never oversupplied these markets during the pandemic. When inventory growth is measured in weeks instead of months of supply, sellers can still demand full price and your buyer’s “let’s wait and see” strategy becomes “let’s watch someone else close.”
In these markets, your job isn’t finding deals—it’s preparing buyers for a knife fight with paperwork. Lock periods matter. Appraisal waivers matter (where allowed). Your reputation with listing agents matters more than your rate sheet.
The Five Metros Where Buyers Finally Have the Upper Hand
Now flip the script. These Sun Belt and Mountain West metros saw the biggest pandemic price surges, the most aggressive builder activity, and are now dealing with the hangover. ResiClub identifies these as markets where active inventory exceeds pre-pandemic 2019 levels “by a solid clip.”
Austin, TX sits at -28.8% below its 2022 peak. The poster child for pandemic overheating followed by overcorrection. Domestic migration that looked permanent in 2021 slowed dramatically by 2023. Builders kept delivering inventory into a cooling market. Result: your buyers can negotiate inspection repairs, closing cost credits, and rate buydowns simultaneously. Appraisal gaps? In Austin, you’re more likely to appraise over asking on new construction offering incentives.
Tampa, FL and other Florida metros face similar dynamics. Insurance costs that would make a bookie wince, inventory that keeps climbing, and sellers who bought in 2021 realizing they might need to accept 2019 prices. Your buyers here should start 10-15% below asking on anything that’s been listed more than 45 days. The worst that happens? Counteroffer. The best? You’re a hero.
Boise, ID and Phoenix, AZ complete the correction corridor. These markets combined pandemic migration surges with builder enthusiasm that would make a golden retriever look pessimistic. Now? Months of supply that actually favor buyers for the first time since 2019. When new construction builders are offering 5% in closing costs plus rate buydowns, your resale seller clients need to match or watch their listing go stale.
In these markets, your role shifts from warrior to strategist. Teach buyers to negotiate. Show them comparable sales from the past 90 days, not the 2022 peak. Position patience as power—because in a market with rising inventory, time favors the buyer with a solid pre-approval.
What Builder Sentiment at a 14-Year Low Actually Means for Your Pipeline
The NAHB/Wells Fargo Housing Market Index dropped to 25 in November 2026—the lowest reading since April 2012. Any score below 50 means more builders see conditions as poor than good. This wasn’t a subtle decline: builder confidence fell four points in a single month.
Here’s what NAHB Chief Economist Robert Dietz told members: “Mortgage rates above 7%, softer consumer confidence and an uncertain economic outlook are holding buyers back.” Add in immigration enforcement reducing available labor, higher fuel costs hitting subcontractors, and tariff-driven material price increases, and you’ve got builders tapping the brakes hard.
The numbers: 46% of builders cut prices in November—the highest share in the post-COVID period. Another 68% offered sales incentives, marking the 20th consecutive month where at least 60% of builders used incentives. When builders get desperate, they don’t just lower prices—they buy down rates, cover closing costs, throw in upgrades, and suddenly your buyer’s monthly payment drops $300 compared to resale.
For loan officers, plummeting builder sentiment creates a short-term opportunity and a medium-term problem. Short-term: new construction becomes genuinely competitive on monthly payment, not just on “new and shiny.” You can move buyers who were priced out of resale into new builds with incentives that make the math work. Medium-term: if builders stop building in your market, inventory constraints return and we’re back to bidding wars in 18-24 months (looking at you, Hartford).
The bifurcation matters here too. Builders in Austin and Tampa might scale back, but they’re scaling back from oversupply. Builders in Hartford and Buffalo barely built anything during the boom—they’re not cutting back because they never ramped up. Your market’s builder sentiment matters less than your market’s inventory position relative to 2019 levels.
The Inventory Dynamic That Explains Everything (Almost)
ResiClub’s data reveals the clearest predictor of which markets favor buyers versus sellers: current active inventory compared to pre-pandemic 2019 levels. Not compared to 2020 or 2021—those years were aberrations. 2019 represents the last “normal” baseline.
Markets where inventory remains below 2019 levels: sellers retain pricing power. Hartford, Buffalo, Rochester, and many Northeast/Midwest metros never saw the builder frenzy. Existing homeowners locked into 3% mortgages aren’t listing. New construction didn’t flood the zone. Result: every buyer competes for limited inventory, which props up prices even as mortgage rates hover above 7%.
Markets where inventory exceeds 2019 levels: buyers gain negotiating leverage. Austin, Tampa, Boise, Phoenix, and much of the Sun Belt saw builders deliver units into 2024 and 2025 based on 2021 demand projections. Domestic migration cooled. Mortgage rates doubled. Inventory stacked up. When supply outpaces demand, prices fall—it’s not complicated, just painful if you’re selling.
The national picture: 76 of 300 major metros show year-over-year price declines as of October 2026, up from 54 in August. That’s a 41% increase in markets seeing price drops in just two months. The softening is “regaining momentum,” as ResiClub puts it, coinciding with the recent jump in long-term yields and mortgage rates back above 7%.
For loan officers, this inventory lens clarifies everything. Stop asking “is it a buyer’s or seller’s market nationally?” Start asking “where does my client’s target market sit relative to 2019 inventory levels?” That single question determines your strategy, your messaging, and whether your pre-approval converts or expires unused.
How to Position Yourself as the Geographic Expert When Clients Ask ‘Should I Wait?’
Every buyer since 2022 has asked some version of: “Should I wait for rates to drop?” or “Should I wait for prices to fall?” The honest answer in 2026 depends entirely on geography, and your ability to articulate that distinction is what separates you from the loan officer reading rate sheets over the phone.
For buyers in rising markets (Hartford, Buffalo, Grand Rapids): waiting costs them. Inventory isn’t improving. Prices aren’t falling. If rates drop from 7.2% to 6.5%, demand surges and they’ll face even more competition for the same limited inventory. Your message: “In this market, waiting for perfect conditions means watching prices rise faster than rate improvements can offset. Let’s find what you can afford now and refinance when rates improve.”
For buyers in falling markets (Austin, Tampa, Boise): patience has an expiration date. Yes, inventory is rising and prices are softening. But ResiClub notes that 76 markets are falling while 224 are rising—and the longer this bifurcation persists, the wider the gap becomes. Your message: “You have negotiating power right now that you haven’t had in five years. Use it. But if builders stop building and inventory gets absorbed, this window closes. Let’s define your walk-away price and negotiate hard.”
For buyers who insist on waiting in any market: show them the math. A 1% rate drop on a $400,000 loan saves roughly $240/month. A 5% price increase on that same home costs $20,000 more down payment (at 20% down) plus higher monthly payments on a larger loan. In rising markets, waiting for rate improvements while prices climb is financial self-sabotage. Run the numbers. Make it concrete.
The geographic expert move: create a simple one-page market snapshot for your top three metros. Current inventory versus 2019 levels. Year-over-year price change. Average days on market. Percentage of sellers offering concessions. Update it quarterly. When a buyer asks “should I wait?”, you pull out data specific to their target market and answer with authority instead of platitudes.
The Bottom Line on Geographic Intelligence in 2026
The national housing market is a myth. There is no single “market”—there are 300 distinct markets moving in different directions at different speeds, and 76 of them are falling while 224 are rising. Hartford is up 28% from peak while Austin is down 29% from peak. Those aren’t rounding errors; they’re different planets.
Your action items for the next 30 days: First, identify where your top ten clients or prospects are actually shopping and map those metros against ResiClub’s inventory data relative to 2019 levels—you need to know if you’re playing in a buyer’s or seller’s market before you open your mouth. Second, adjust your pre-approval strategy accordingly: in tight inventory markets, your underwriting needs to be flawless and your relationships with listing agents matter more than your rate; in loose inventory markets, teach your buyers to negotiate like it’s 2019 because sellers haven’t adjusted their expectations yet. Third, stop giving the same market update to everyone—a buyer shopping Buffalo needs radically different advice than a buyer shopping Tampa, and if you’re not customizing your message by geography, you’re the generic loan officer they forget by Tuesday.
The loan officers closing deals in 2026 aren’t the ones with the lowest rates. They’re the ones who can look at a buyer’s target market and say with confidence: “Here’s what leverage you have, here’s what you’re competing against, and here’s exactly how aggressive your offer needs to be.” That’s not market commentary—that’s geographic intelligence, and it’s the difference between a closing and a pre-approval that expires unused.
You made it through a 56-point price spread between Hartford and Austin without falling asleep—that’s the kind of focus that closes loans. Want more geographic intelligence delivered before your competitors figure out which markets actually favor buyers? Subscribe to Well That Makes Sense at WellThatMakesSense.com and follow us on social for the market data that matters.
Just promise you won’t use this intel to explain to your Austin seller why their 2021 Zestimate isn’t coming back. Some conversations require hazard pay.