WTMS Blog Today= Builder Confidence at 14-Year Lows: The Supply Crunch You’re Not Pricing In (Yes, Really)
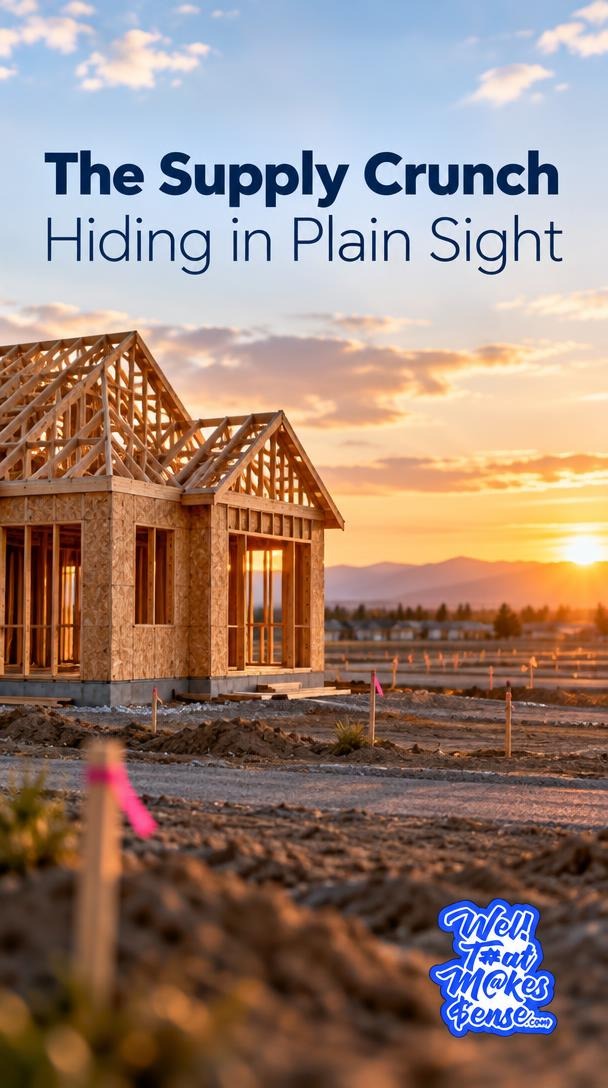
While builders slash prices today, they’re also scaling back construction—creating the tighter purchase market that will define your 2027 pipeline.
Picture this: Your buyer just forwarded you another headline about builder sentiment crashing to a 14-year low, asking if they should wait for prices to drop further. Meanwhile, you’re watching builders in three local subdivisions quietly shelve their next phases.
Here’s the disconnect most loan officers miss: falling builder confidence doesn’t mean falling home prices are coming. It means falling home construction is coming. And that supply crunch, 12 to 18 months out, is the urgency conversation that moves purchase clients off the fence today.
The NAHB/Wells Fargo Housing Market Index dropped to 25 in November 2026, the lowest reading since April 2012. Buyer traffic fell to 16, its weakest in 15 years outside COVID. And 46% of builders cut prices this month, the highest share in the post-pandemic period, according to the National Association of Home Builders. On the surface, it looks like a buyer’s market arriving just in time.
The Metric That Matters: Builders Aren’t Just Discounting, They’re Disappearing
Here’s what the headline writers are missing: when builder confidence collapses, builders don’t just offer incentives and wait it out. They scale back construction. NAHB Chairman Bill Owens put it plainly: “With fewer buyers in the market, more builders are scaling back construction.”
That’s the sentence that should change how you talk to every purchase client sitting on the sidelines. Yes, 68% of builders are offering sales incentives right now, also a post-COVID high. Yes, price cuts are happening. But those same builders are simultaneously pulling permits, delaying phases and mothballing projects in markets where buyer traffic has evaporated.
The math is straightforward: fewer starts today equals tighter inventory in 2027 and 2028. And unlike the resale market, where locked-in homeowners can theoretically be coaxed out with the right price, construction that doesn’t happen this year simply doesn’t exist next year. You can’t list a home that was never built.
This isn’t speculation. It’s how builders have always responded to margin compression. When mortgage rates sit above 7% and construction costs remain elevated by tariffs and labor shortages (NAHB Chief Economist Robert Dietz specifically cited “building material costs pushed higher by tariffs” and “an ongoing shortage of construction workers”), builders protect their balance sheets by building less, not by building at a loss indefinitely.
The Regional Story: Where Builders Are Retreating and What It Signals
The supply pullback isn’t uniform, and that’s where your local market intelligence becomes your edge. According to ResiClub’s analysis of the Zillow Home Value Index, 76 of the nation’s 300 largest housing markets posted year-over-year home price declines as of October 2026, up from 54 markets just two months earlier.
The markets seeing the most pressure? Largely Sun Belt and Mountain West metros that overbuilt during the pandemic boom and now face elevated inventory. Places where active inventory exceeds pre-pandemic levels by a solid clip—think certain Texas, Florida, Washington and Colorado markets—are the same places where builders are most aggressively scaling back.
Meanwhile, markets in the Northeast and Midwest where active inventory remains well below 2019 levels are still posting modest price gains. Hartford, Connecticut sits 28% above its 2022 peak. Austin, Texas sits 28.8% below its 2022 peak. That bifurcation tells you exactly where builders have room to keep building (nowhere with margin pressure) and where they don’t (everywhere with margin pressure).
Here’s the purchase pipeline insight: if you’re working a market where inventory has normalized or ticked higher, your buyers are watching builder incentives and assuming more supply is coming. They’re wrong. Those same builders are the ones most likely to pull back on future phases, which means today’s “soft market” is actually the high-water mark for choice.
The Labor and Material Squeeze: Why This Isn’t a Short-Term Blip
Even if builder sentiment recovers tomorrow, the supply constraints baking into the market won’t reverse quickly. Dietz called out three structural headwinds: immigration enforcement reducing the construction labor pool, tariffs pushing material costs higher, and regulatory burdens undermining affordability.
Translation: the cost side of the builder equation isn’t improving. Stepped-up immigration enforcement is “keeping legal workers off job sites, deepening labor shortages and driving up costs,” according to NAHB. Higher fuel prices are prompting subcontractors to raise rates. And builders can’t simply wait for mortgage rates to fall if their input costs keep climbing.
This is the part of the builder sentiment story that most buyers (and most loan officers) gloss over. Builders aren’t just reacting to demand. They’re reacting to whether they can profitably deliver a home at a price point buyers can afford to finance at current rates. When that equation doesn’t work, they stop building. And when they stop building in 2026, your buyers face tighter inventory in 2027.
You’re not selling fear. You’re selling math. The same forces that are crushing builder margins today—high rates, high costs, tight labor—are the forces that will constrain new supply tomorrow, precisely when current homeowners remain locked in by low rates and resale inventory stays thin.
The Mortgage Connection Your Buyers Aren’t Making
Here’s the urgency message that actually moves purchase clients: waiting for “the bottom” means waiting for less inventory and renewed competition. The soft market with builder incentives happening right now isn’t the beginning of a prolonged downturn. It’s the pause before supply constraints tighten further.
Nationally aggregated home prices rose just 0.7% year-over-year from October 2025 to October 2026, per ResiClub’s analysis, down from 1.0% the prior month and 1.3% two months before that. That deceleration, combined with builder incentives and rate buydowns, gives today’s buyers more leverage than they’ve had in years. But leverage over current inventory doesn’t help when future inventory shrinks.
Frame it this way: your buyer can act now and choose from the full range of available homes, including new construction with meaningful incentives, or they can wait 18 months and compete for a smaller pool of resale listings while new construction activity remains depressed. Which scenario gives them more negotiating power?
The builder sentiment crash isn’t a reason to wait. It’s proof that the window is closing. Builders offering rate buydowns and price cuts today are the same builders who won’t break ground on their next phase tomorrow. And when buyer traffic eventually recovers—whether rates fall or buyers simply adjust to the new normal—the supply that should have been built in 2026 won’t be there to meet it.
How to Position This Without Sounding Like a Doomsayer
You’re not predicting a crash or a boom. You’re connecting dots your buyers aren’t connecting. Here’s the conversation framework that works:
Start with validation. “You’re right that builder confidence is low and some markets are seeing price cuts. That’s real, and it’s giving buyers more options right now than they had six months ago.”
Pivot to the supply insight. “What most people miss is that low confidence doesn’t just mean discounts—it means builders are scaling back construction. The NAHB just reported sentiment at a 14-year low, and builders are responding by pulling back on new projects. That’s less supply 12 to 18 months out.”
Tie it to their decision timeline. “So the question isn’t whether prices might soften another few percent in some markets. It’s whether waiting for that potential softening is worth facing a tighter market with fewer choices when you’re actually ready to move. Especially when builders are offering rate buydowns and incentives right now that won’t be on the table once they’ve scaled back.”
You’re not pushing. You’re reframing the risk. The risk isn’t buying before the mythical bottom. The risk is waiting through a temporary soft patch and emerging into a supply-constrained market where today’s buyer leverage has evaporated. And you have the NAHB data to back it up.
The Products and Programs That Make This Actionable
Data-driven urgency only works if you pair it with a clear path forward. This is where your product knowledge separates you from the loan officer who just forwards rate sheets.
Lead with builder incentives and rate buydowns. With 68% of builders offering incentives, you should know which local builders are buying down rates, covering closing costs, or offering price cuts. That’s not just a sales tool—it’s proof that today’s market gives buyers leverage they won’t have once construction activity contracts.
Position adjustable-rate products for the fence-sitter. If your buyer is worried about rates above 7%, show them how a 7/1 or 10/1 ARM captures a lower rate now while giving them years to refinance if rates eventually fall. The builder pullback story makes the ARM conversation easier: act now with a lower payment, refinance later if the opportunity arises, but don’t sit out the market waiting for perfect conditions while inventory tightens.
Use the bifurcation data to target your outreach. If you’re working a market where inventory has normalized (or where prices are flat to down year-over-year), your messaging should emphasize that this is the inventory peak, not the beginning of a buyer’s market. If you’re in a market where inventory remains tight and prices are still climbing modestly, the builder pullback reinforces that waiting won’t improve their options.
The loan officers winning purchase business right now aren’t the ones predicting the future. They’re the ones explaining the present in a way that clarifies the decision. And the present is this: builder sentiment is low, construction is pulling back, and the soft market your buyers are waiting to “get softer” is actually the narrow window before supply constraints bite harder.
Your Next Move: Turn Sentiment Data Into Pipeline Conversations
Here’s what this looks like in practice. Pull the NAHB release. Identify which local builders are offering the most aggressive incentives. Then reach out to every purchase client in your pipeline who’s been waiting for “the right time” with a simple message: “Builder confidence just hit a 14-year low, and here’s why that’s actually your buying signal, not your waiting signal.”
Walk them through the supply math. Show them the local builder incentives. Position the ARM or the buydown program that makes the payment work today. And frame the decision clearly: act now while builders are still building and offering deals, or wait 18 months and compete for less inventory in a market where today’s incentives are long gone.
The loan officers who will own the purchase market in 2027 are the ones having this conversation in late 2026. Because when buyer traffic eventually recovers and your competitors are scrambling to explain why inventory is tight and competition is back, you’ll have a pipeline full of clients who moved when you told them the window was open.
Builder sentiment at 25 isn’t a reason to panic. It’s a leading indicator. And leading indicators are only useful if you lead with them. The supply crunch is coming. The only question is whether your buyers act before it arrives or spend 2027 wishing they’d listened when you connected the dots.
You made it through 1,600 words on builder sentiment without falling asleep, which means you’re exactly the kind of loan officer who turns data into deals. Subscribe to Well That Makes Sense at WellThatMakesSense.com for more market intelligence that actually moves buyers, and follow Well That Makes Sense on social for the posts that make you look smarter than your competitors at the next industry mixer. Because nothing says “I understand supply-demand dynamics” like explaining why low builder confidence is secretly bullish for purchase pipelines—while everyone else is still forwarding rate sheets.