**WTMS Blog Today = What’s up in Mortgage Today (PM) – 10/12/2026**
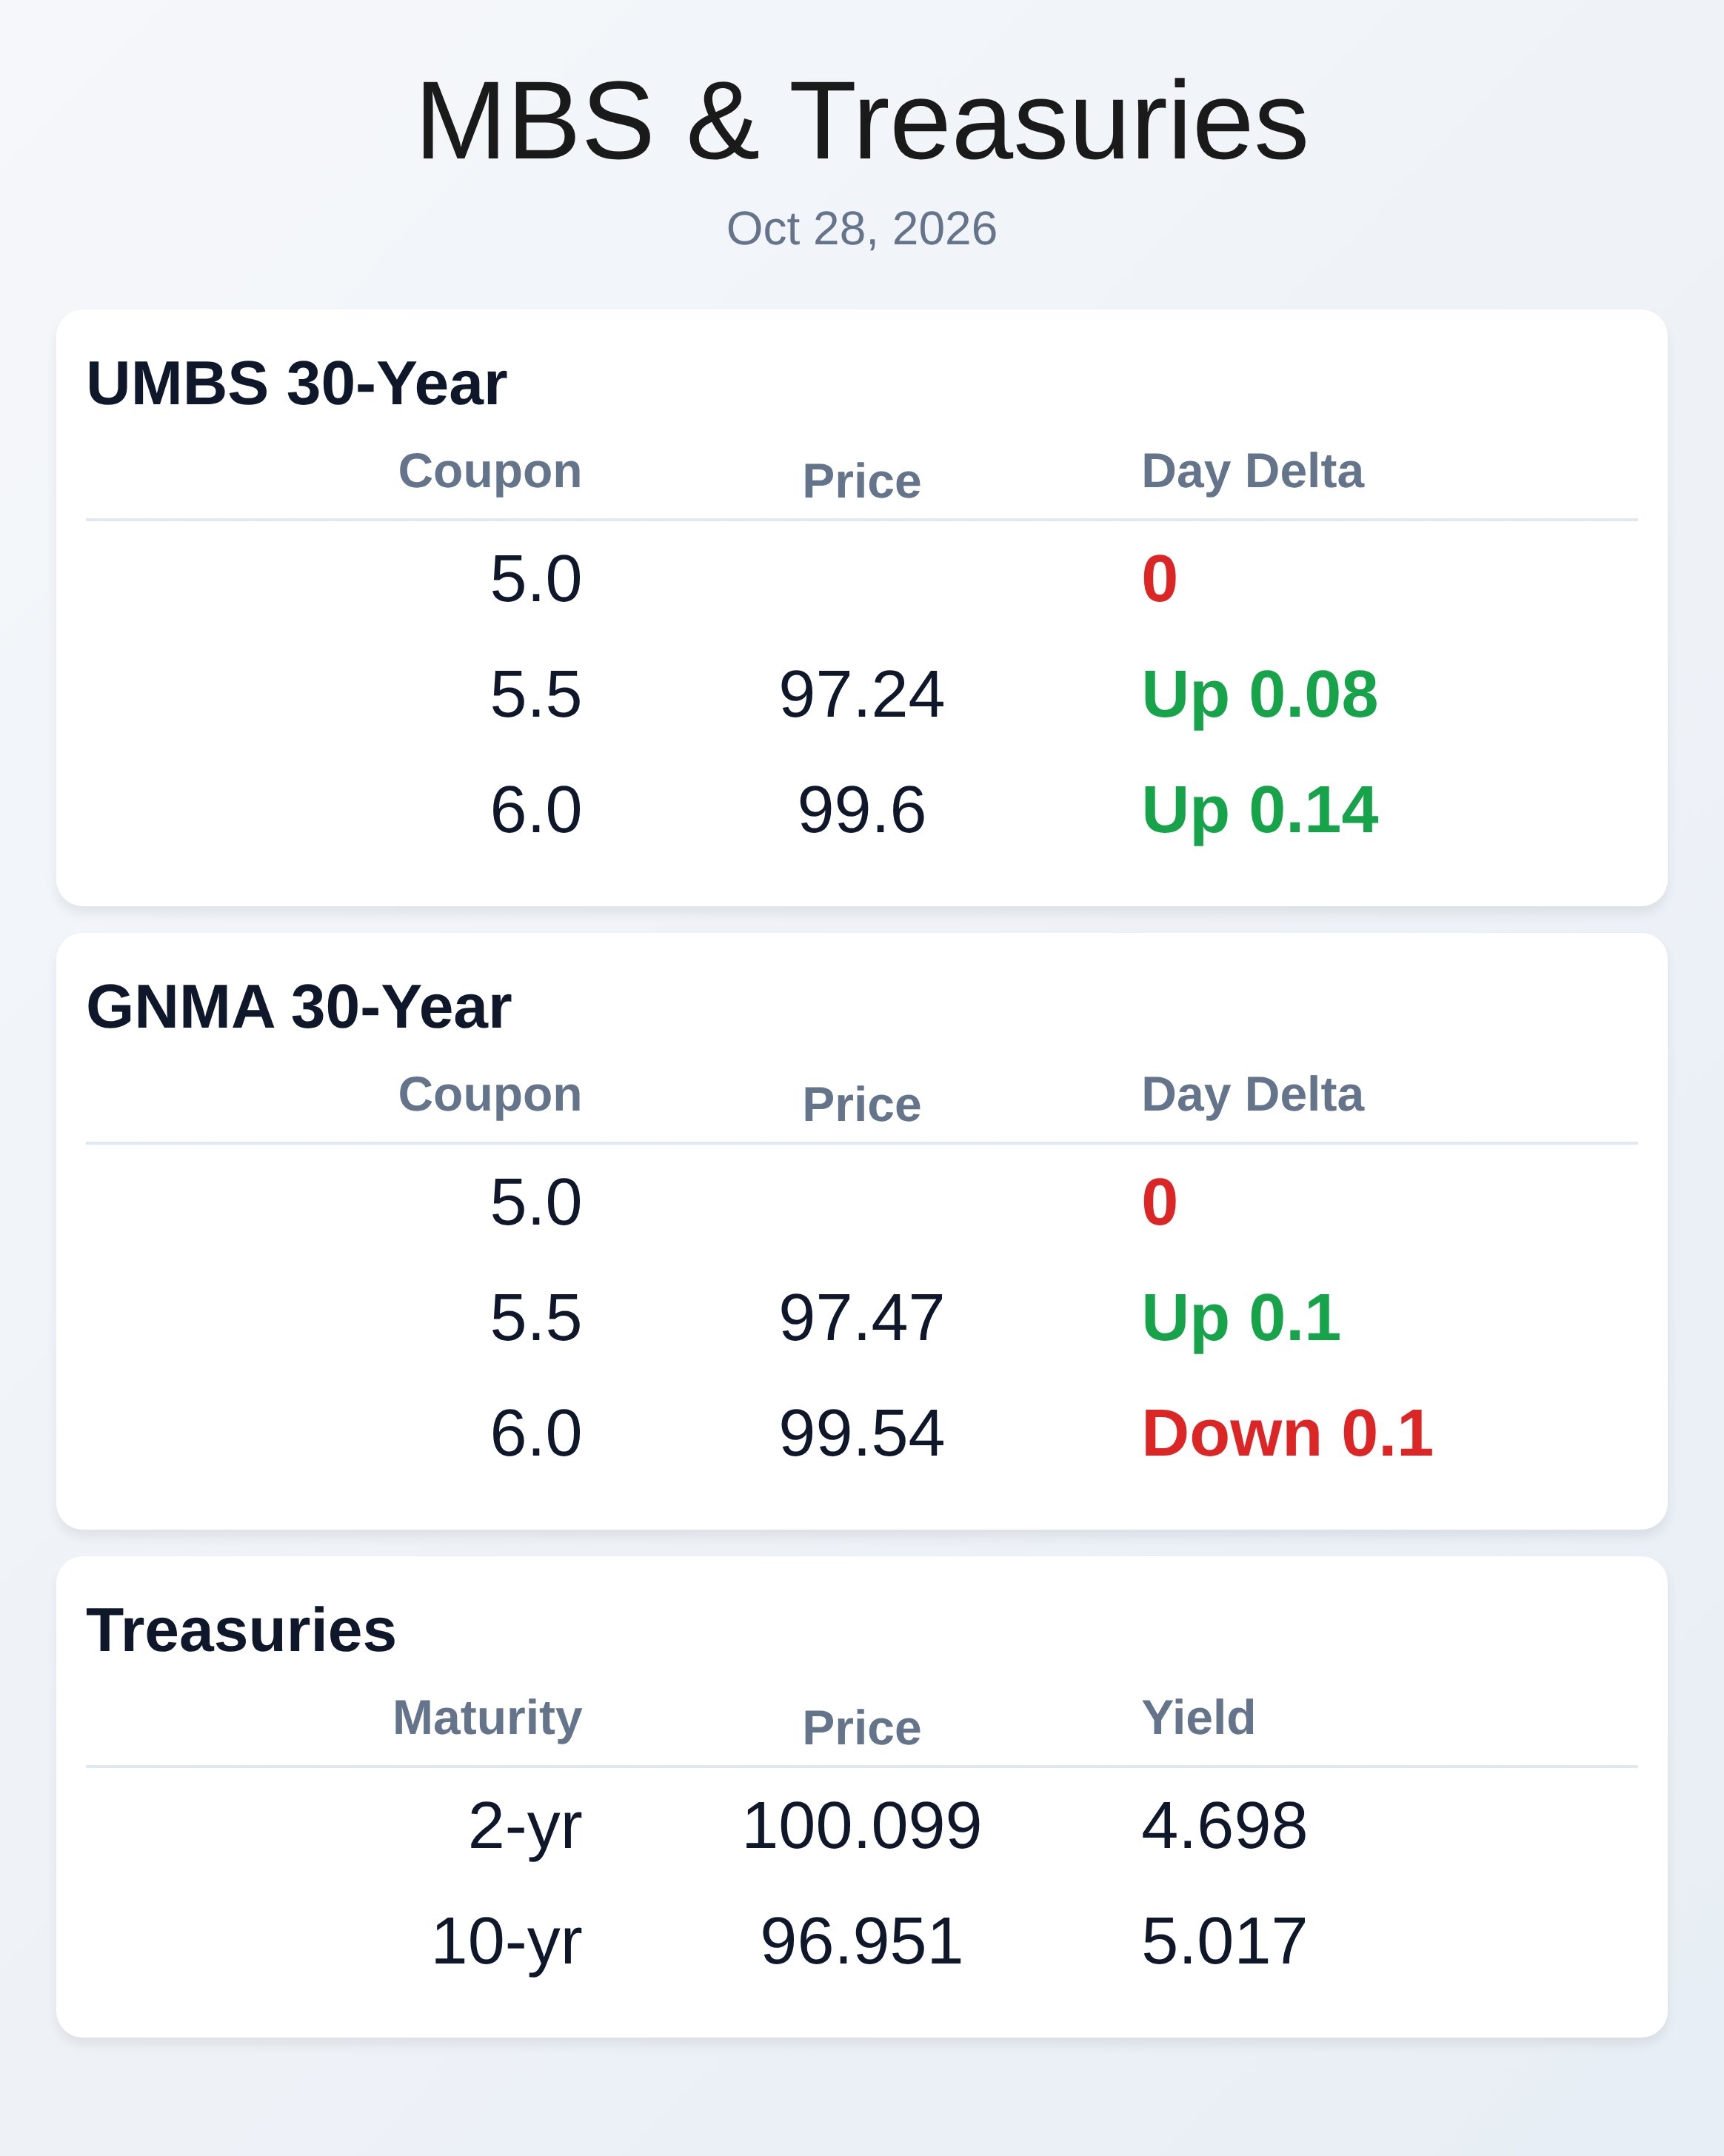
The mortgage market is holding steady at a crossroads as bond traders wrestle with competing forces: persistent inflation worries, geopolitical tensions pushing oil higher, and growing anxiety about AI-driven debt bubbles. UMBS 6.0 closed Friday at 98.27, while the 10-year Treasury yield sits at 5.243%, after a week of volatile swings between optimism about tech weakness and concern about stubborn price pressures. MBA’s economic team downgraded 2027 origination forecasts to just under $2 trillion, down 5% from 2026, signaling origination volume headwinds will persist through year-end and into spring.
Sellers now outnumber buyers by 63%—a record gap since 2013—giving real estate agents unprecedented leverage in negotiations even as that market remains starved for qualified borrowers. Mortgage applications fell 4.2% week-over-week last week, and the primary-secondary spread widened to 92 basis points as lenders brace for tighter margins and more selective customer acquisition. The week ahead will test whether mid-October’s bond rally holds ground or fades into another round of selling.
The Consumer Confidence Index and economic data releases later this week could accelerate a rebound in Treasury yields if they signal the labor market remains too strong for the Fed to pause indefinitely. Wall Street had priced in nearly zero probability of an October rate hike going into this week, but recent inflation prints have traders reconsidering whether the Fed truly has the luxury of sitting pat through year-end. For mortgage originators, the backdrop remains challenging: purchase originations are forecast to gain just 0.8% next year to $1.42 trillion, while refinance volume craters 17% to $571 billion as existing homeowners with sub-5% rates have no rational incentive to touch their mortgages.
Technology valuations and AI credit concerns continue to dominate sentiment, with brief periods of weakness in semiconductor stocks triggering sharp bond rallies as investors seek safe havens. The MBA’s week in Chicago highlighted just how wide the gap has grown between mortgage banking cost structures and the revenue lenders can generate in this environment, with multiple industry voices warning that traditional retail delivery models are becoming economically unsustainable. Pending home sales hit a 12-year low as higher rates and limited inventory converge to squeeze both demand and supply, leaving brokers and loan officers fighting harder than ever to capture a smaller pool of qualified buyers.
Credit remains surprisingly resilient despite affordability pressures, though FHA originations are climbing as borrowers with moderate credit profiles lean on government programs to bridge the down-payment gap. The tension between rate stability and mortgage demand will likely define the remainder of Q4, with lenders forced to optimize cost structures and technology investments to survive margins that show no sign of meaningful improvement.
**Locking vs Floating**
Traders continue to assess whether last week’s tech-driven rally establishes a floor in yields or merely provides another tactical relief bounce before yields resume their climb.
The playbook remains hazardous: lock aggressive borrowers facing imminent closings, float only those with genuine pipeline cushion and strong fallback options.
**Today’s Events**
October Consumer Sentiment (preliminary): Forecast 47.6, Prior 48.1
University of Michigan Consumer Sentiment data may provide clues about whether rising rates and economic uncertainty are finally beginning to dent household confidence.
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |