**WTMS Blog Today = What’s up in Mortgage Today (PM) – 10/23/2026**
Mortgage rates delivered their best daily performance since August 2025 this week as technology stock turmoil sent investors scrambling into the safety of Treasury bonds. The 10-year yield plummeted 159 basis points on Thursday alone, with UMBS 6.0 climbing nearly 70 basis points to 99.55 as flight-to-safety dynamics overwhelmed concerns about persistent inflation and elevated oil prices. Artificial intelligence sector weakness, particularly pressure on companies like Coreweave facing funding uncertainties, triggered broad equity selloffs that fundamentally shifted bond market demand.
Mortgage origination margins improved noticeably as secondary markets tightened spreads, offering meaningful relief after weeks of constrained gain-on-sale margins. The rally’s staying power depends entirely on whether technology credit concerns persist or stabilize, creating genuine uncertainty for locking strategy into early November. President Trump signed a sweeping housing executive order Thursday targeting mortgage insurance cancellation, refinance costs, and GSE fee structures through the FHFA.
The order directs proactive mortgage insurance cancellation for eligible borrowers based on current property values, though the pilot applies only to loans originated after the program begins, limiting immediate impact on existing homeowners. Title insurance waiver programs become permanent, potentially saving $500 to $1,500 per refinance while loan-level price adjustments face potential reduction on qualifying rate-reduction refis. However, critics note the proposal favors existing homeowners over purchase borrowers, as savings flow primarily to refinancing and mortgage insurance cancellation rather than addressing home price affordability.
The MBA’s competing affordability roadmap proposes reducing credit score reporting requirements, lowering FHA insurance premiums, and streamlining refinancing across both GSEs. Origination volume projections worsened measurably this week with the MBA forecasting 2027 total single-family mortgage volume declining 5% to just under $2 trillion, down from $2.1 trillion expected in 2026. Purchase originations face only modest 0.8% growth while refinance volume collapses 17% to $571 billion as rising rates throughout October destroyed refinance economics for the vast majority of borrowers.
September funding volume declined 15% year-over-year according to proprietary application data, with retail declining 7% month-over-month despite a 30-year funded rate of 6.58%. Mortgage applications fell another 2.7% week-over-week as rates climbed to 7.5%, their highest level in nearly three years, pushing adjustable-rate mortgage adoption to 10.5% of applications. September prepayment speeds slowed sharply with Fannie Mae speeds falling 7% month-over-month to 6.7 CPR as only 0.5% of mortgages remained economically attractive to refinance.
Home sellers outnumber buyers by 63%, the widest gap since 2013, creating a buyer’s market across 41 of 50 major metros while just five remain seller-favored. Existing home sales rose 1.5% month-over-month to 3.99 million annually, but still trail year-ago levels by 2.2%, with inventory climbing 4.6% year-over-year to 1.6 million homes representing 4.8 months supply. The median existing home price reached $417,500, marking the 39th consecutive month of year-over-year gains despite affordability pressures crushing demand.
Even borrowers willing to put down 20% face an affordability gap, with the median home requiring $90,191 in annual income versus the $79,534 average wage, creating a gap of nearly $11,000. Homes became less affordable than historical averages in 570 of 583 counties analyzed, demonstrating the breadth of the affordability crisis across virtually every market. Wire fraud and defect risk reached troubling levels in the third quarter with FundingShield’s analytics showing 45.9% of monitored transactions carrying material wire and title-related risks across a $108.7 billion portfolio.
Problematic transactions averaged 2.2 issues each, with 47.8% involving closing protection letter discrepancies, 6% involving wire-instruction defects, and 1.6% involving licensing irregularities. GSE repurchase activity increased 19.5% in Q2’26 with 1,401 loans totaling $465.2 million in UPB repurchased, with loans from Q3’25 and Q4’25 accounting for 46.5% of activity. Rocket Mortgage, United Wholesale Mortgage, and Lakeview Loan Servicing represented the three largest originators by repurchase share at 9.7%, 5.4%, and 2.4% respectively.
Fannie Mae also expanded occupancy verification requirements effective November 13, requiring automated valuation model screening to flag potentially inaccurate designations before purchase.
**Locking vs Floating**
Tech stock weakness created genuine safe-haven demand for bonds, but the rally’s continuation depends on whether semiconductor and AI-related credit concerns spread to the broader market or stabilize. Intraday volatility remained elevated as options expiration and thin Friday trading exaggerated moves in both directions, though closing prices held near session highs.
Rates appear to have found support in the 5.05% to 5.10% range this week, but another tech recovery could quickly send yields back toward the 5.27% to 5.34% resistance levels recently tested. Lenders should avoid overcommitting to aggressive repricing until Monday’s opening establishes confirmation of either continued safe-haven demand or profit-taking reversals.
**Today’s Events**
Import prices September: 1.1% vs 0.8% forecast
Industrial Production September: 0.7% vs 0.4% expected
Consumer Sentiment October (preliminary): 47.6 vs 48.1 prior
Existing Home Sales September: 3.99M vs 3.95M forecast
**Bond Pricing**
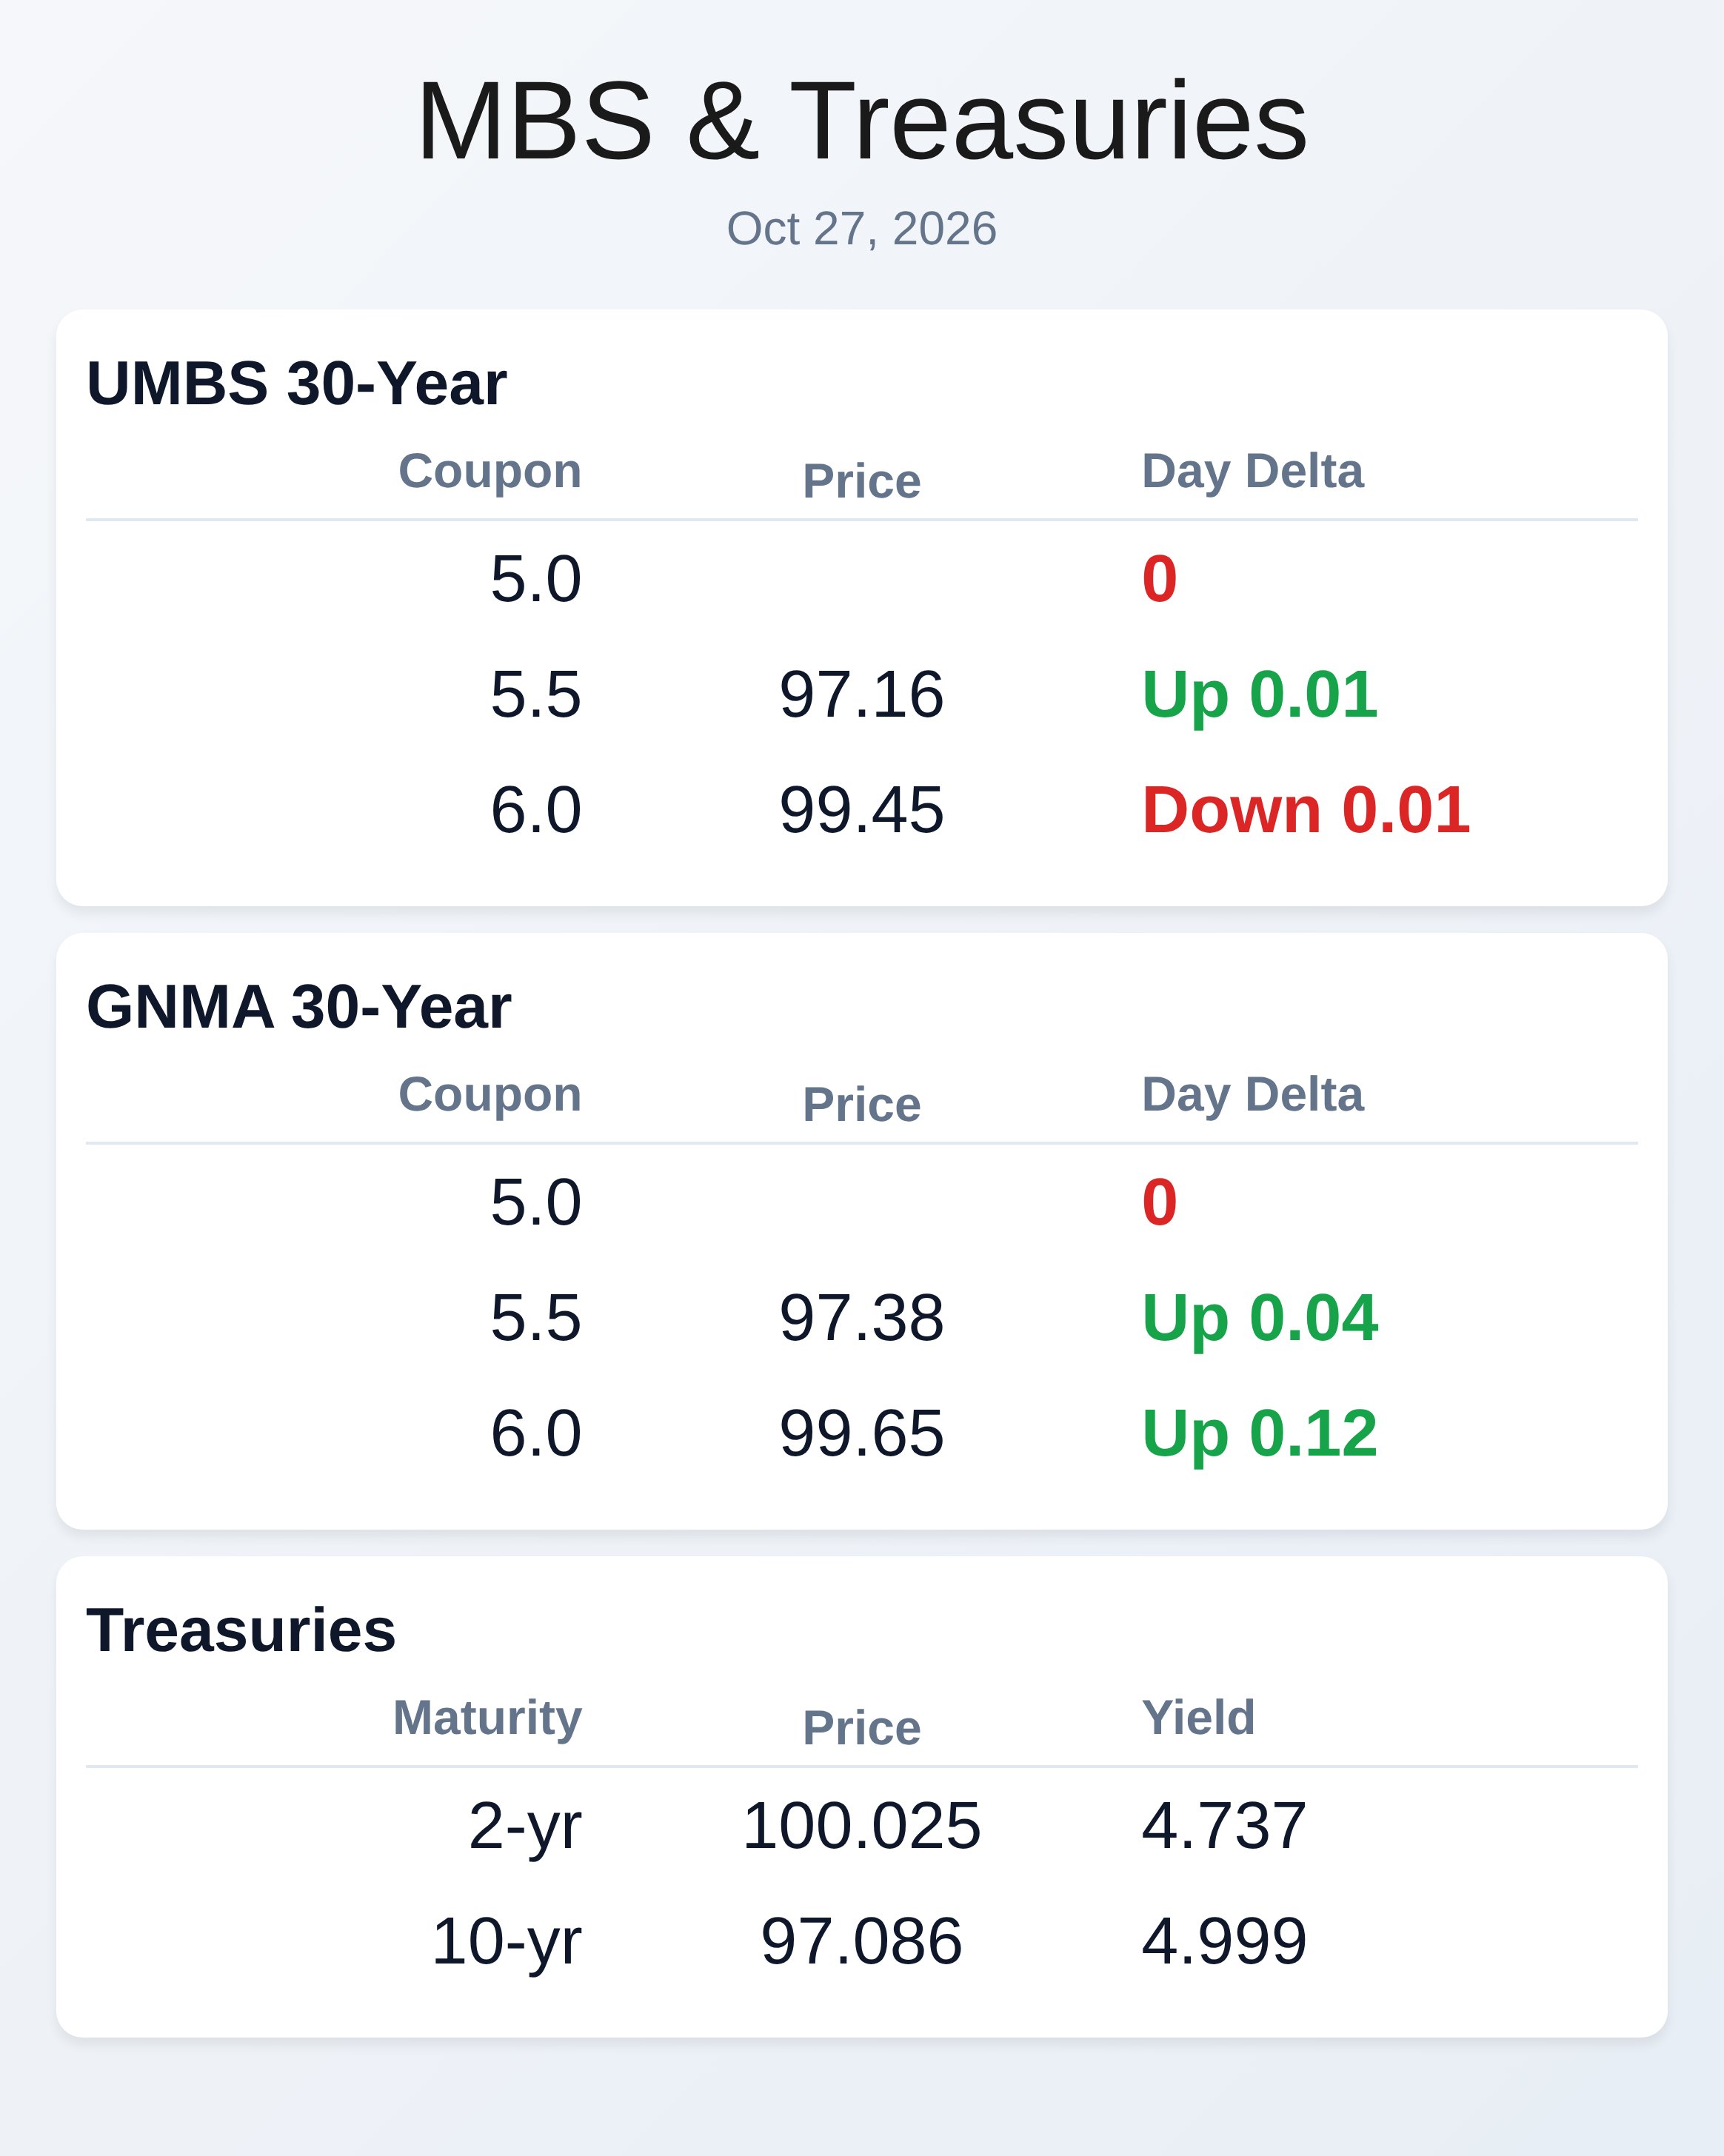
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |