**WTMS Blog Today = What’s up in Mortgage Today (AM) – 11/09/2026**
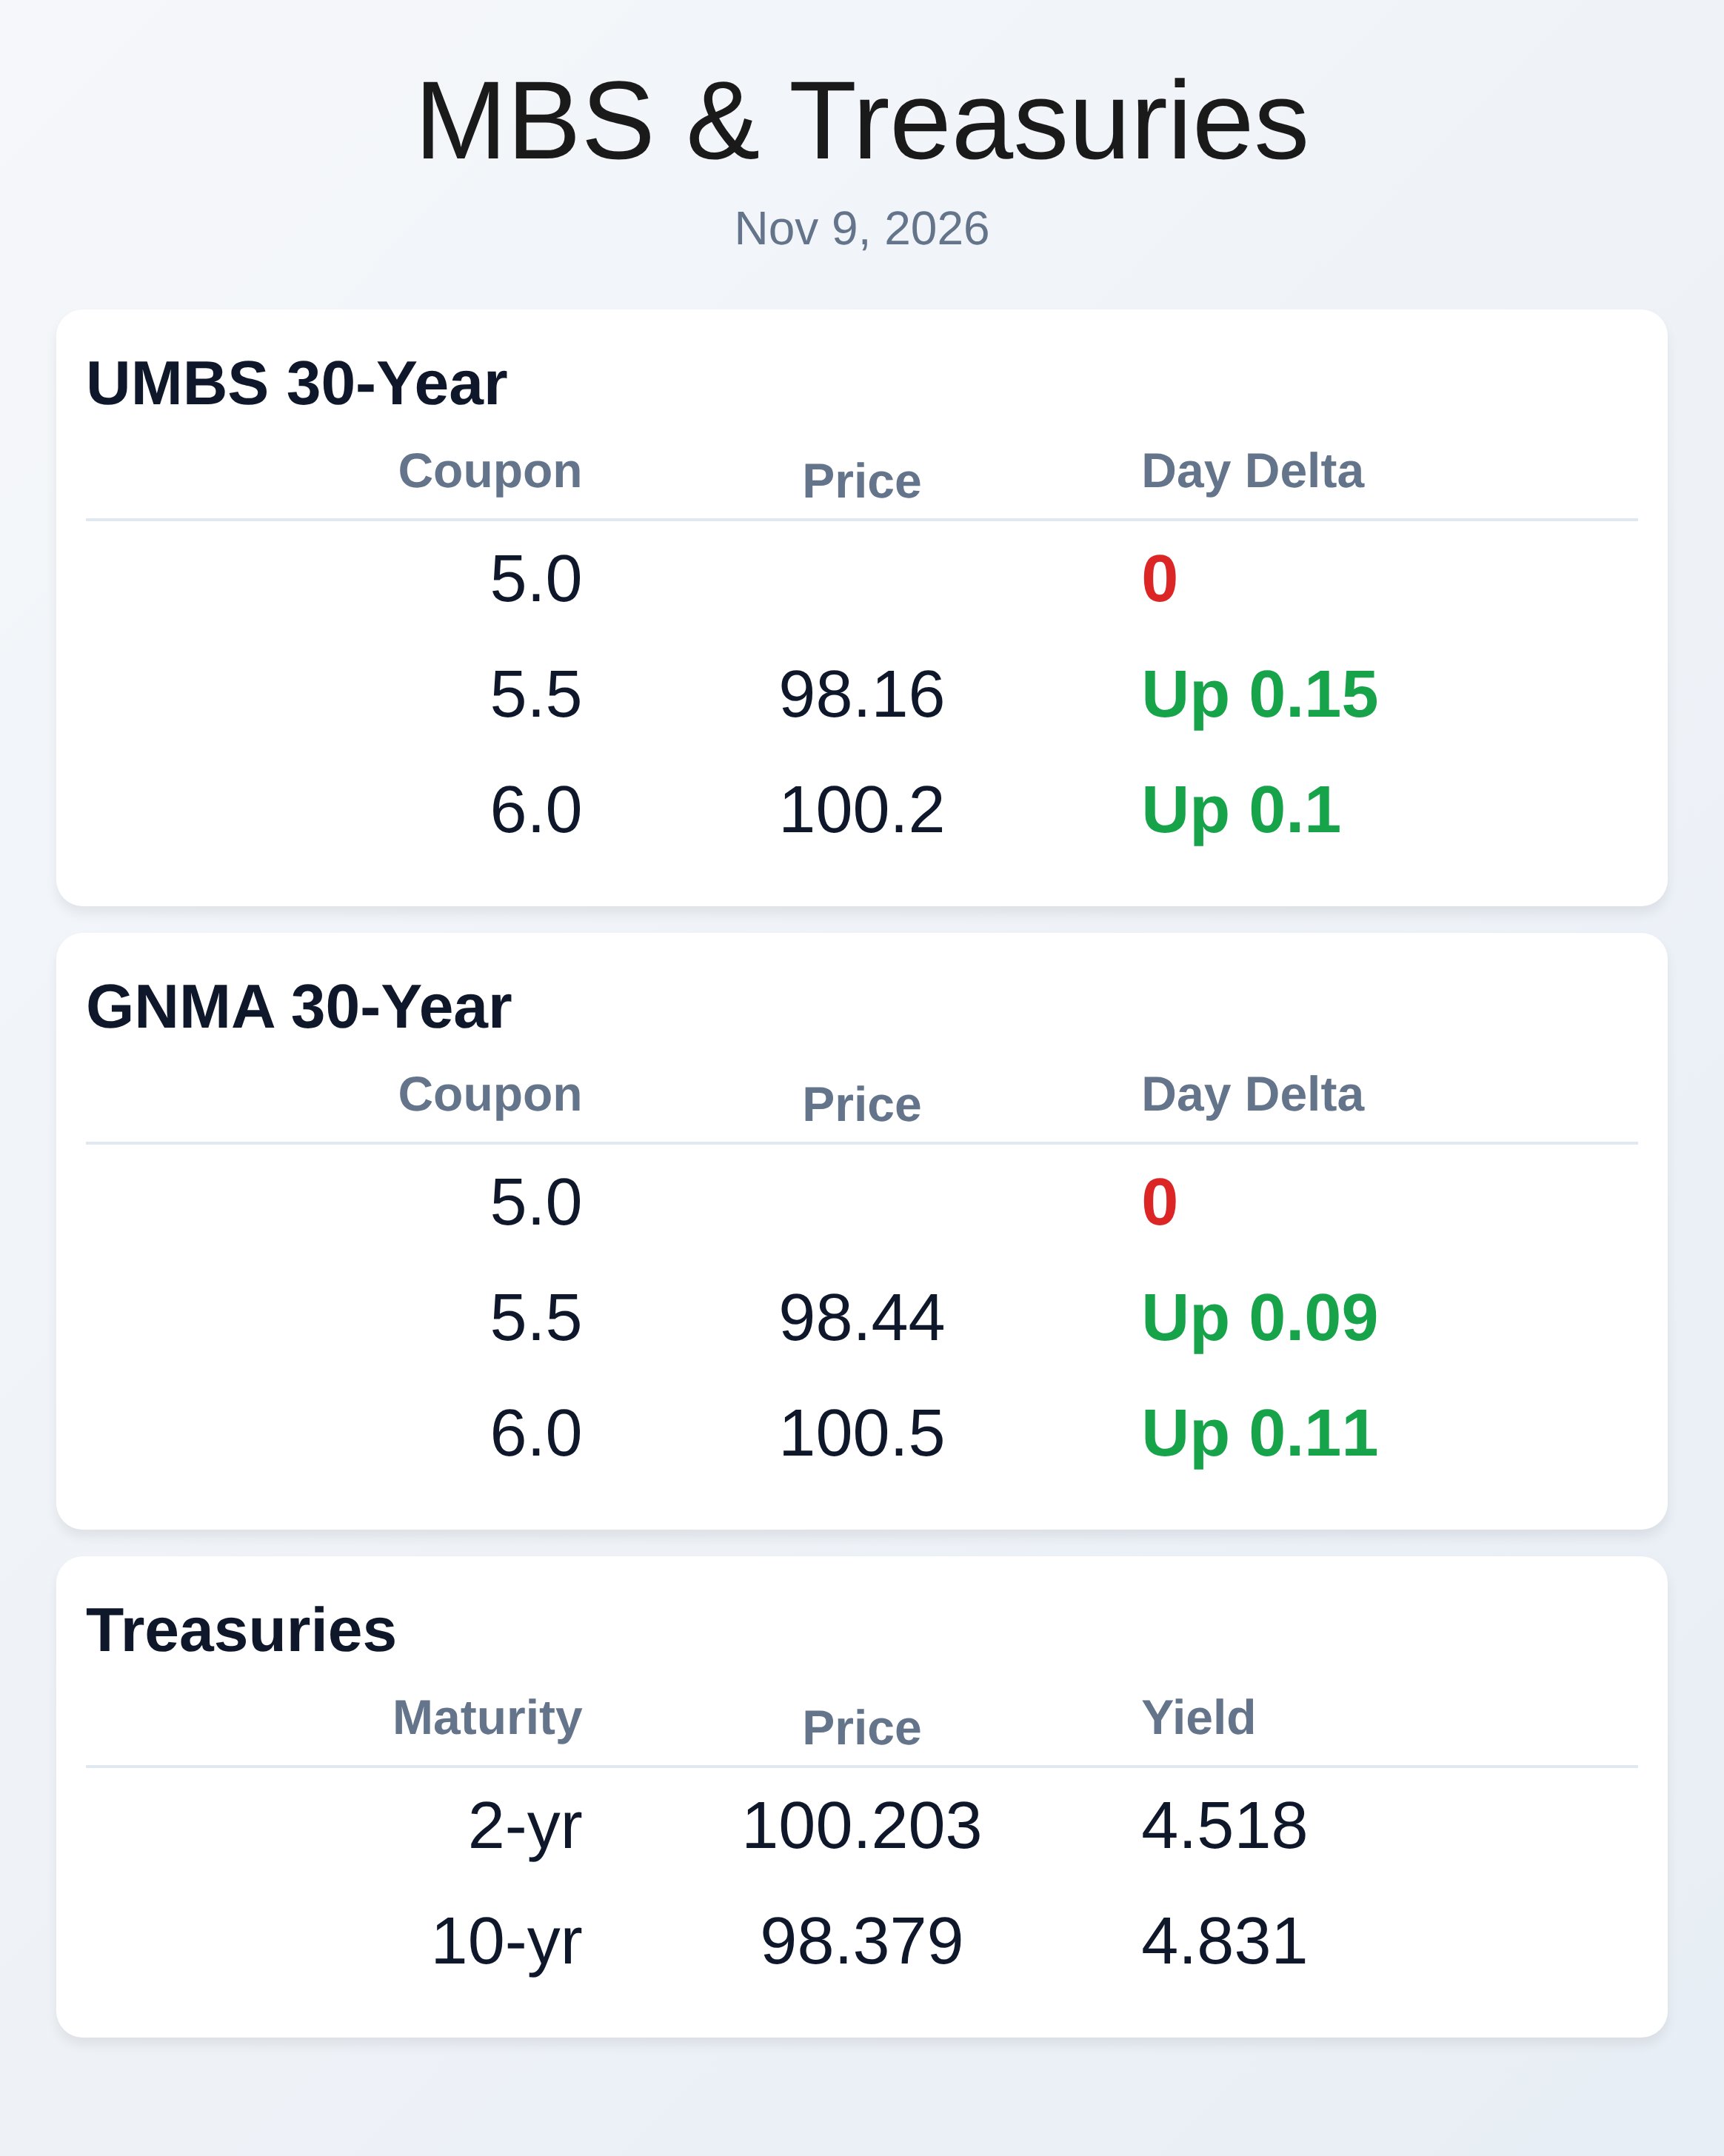
Bonds are starting the week steady near the recent lows, with the 10-year hovering around 4.85–4.86% as oil’s pullback and last week’s risk-off tone keep a lid on yields. After a five-week rebound, UMBS are holding most of their gains, but intraday volatility remains elevated. The AI-led equity shakeout added to the safe-haven bid, while the election outcome reduced odds of big new fiscal stimulus.
Net: rate sheets are modestly better than late October, but headline sensitivity is still high. Eyes shift quickly to tomorrow’s CPI for the next directional cue. UMBS performance improved into month-end as production coupons firmed and the conventional current coupon ticked down toward the high‑5s.
Primary/secondary spreads tightened slightly, reflecting better investor appetite despite choppy flows. October prepayment speeds slowed again, reinforcing extension in discount collateral and supporting payups in well-specified pools. Hedgers should stay nimble: basis has traded well vs.
Treasuries, but liquidity pockets remain thin on headline bursts. Expect dealers to stay balanced ahead of CPI and this week’s refunding. Ginnie paper lagged a touch on spread moves, with GNMA speeds dropping more than conventionals amid still‑elevated FHA credit tails.
TransUnion’s latest data show FHA loans comprising a rising share of 60+ day delinquencies, even as agency and jumbo credit remain broadly stable. That credit mix keeps cashflow dispersion high across coupons and servicers. For pipeline managers, assign appropriate extension/turnover assumptions on GNMA production to avoid convexity surprises if rates back up.
The election’s Democratic sweep tempered expectations for another fiscal push, aiding last week’s rally; now the focus turns back to the Fed and inflation. Markets still lean toward a December hike, but oil’s slide and softer long-run growth expectations have pulled real yields down from October’s peaks. Chair Warsh’s move to fewer rate-setting meetings in 2027 adds to the “wait-and-see” posture.
Bottom line: we’re range‑bound into CPI, with macro and AI headlines the swing factors. On the origination front, apps rose modestly in late October while ARMs climbed to their highest share in over a year as borrowers hunt payment relief. HELOC demand remains strong, and lenders report faster verification and fulfillment win volume.
Competitive dynamics are shifting: Zillow’s move to cover full FHA minimum down payments for eligible borrowers will pressure pure-rate plays and elevate advice-led selling. Operationally, UAD 3.6 is live—lenders need updated appraisal review policies now to avoid suspenses and repurchase risk. Housing activity remains rate-sensitive: October contract signings hit a record October low, with buyers balking at payment levels even as for-sale inventory edges higher.
Asking prices have softened at the margin, cancellations are stable, and builders continue to deploy incentives and buydowns to clear standing spec. Expect seasonality and affordability to keep purchase volume subdued near term, with any sustained relief hinging on clearer disinflation and steadier rates into year‑end.
**Locking vs Floating**
Momentum is constructive but fragile; after a sharp rally, markets face event risk from CPI and refunding.
Use morning strength to capture targets on near‑term closings, especially for floaters exposed to renegotiation risk. If tech volatility calms or inflation surprises, yields could re-test tops of the new range. Conversely, a soft CPI can extend gains, but don’t be complacent—basis liquidity remains patchy, and headlines can flip the tape.
Bias: lock inside 15 days; consider cautious floats beyond that with defined triggers.
**Today’s Events**
– Wholesale Inventories (Sep)
– U.S. Treasury 3‑Year Note Auction
– Chicago Fed President Goolsbee speaks (10:00 a.m.
ET)
– NY Fed Survey of Consumer Inflation Expectations (11:00 a.m. ET)
– Treasury bill auctions (6‑week, 3‑month, 6‑month)
Subscribe free for daily market intel at WellThatMakesSense.com.