**WTMS Blog Today = What’s up in Mortgage Today (PM) – 11/09/2026**
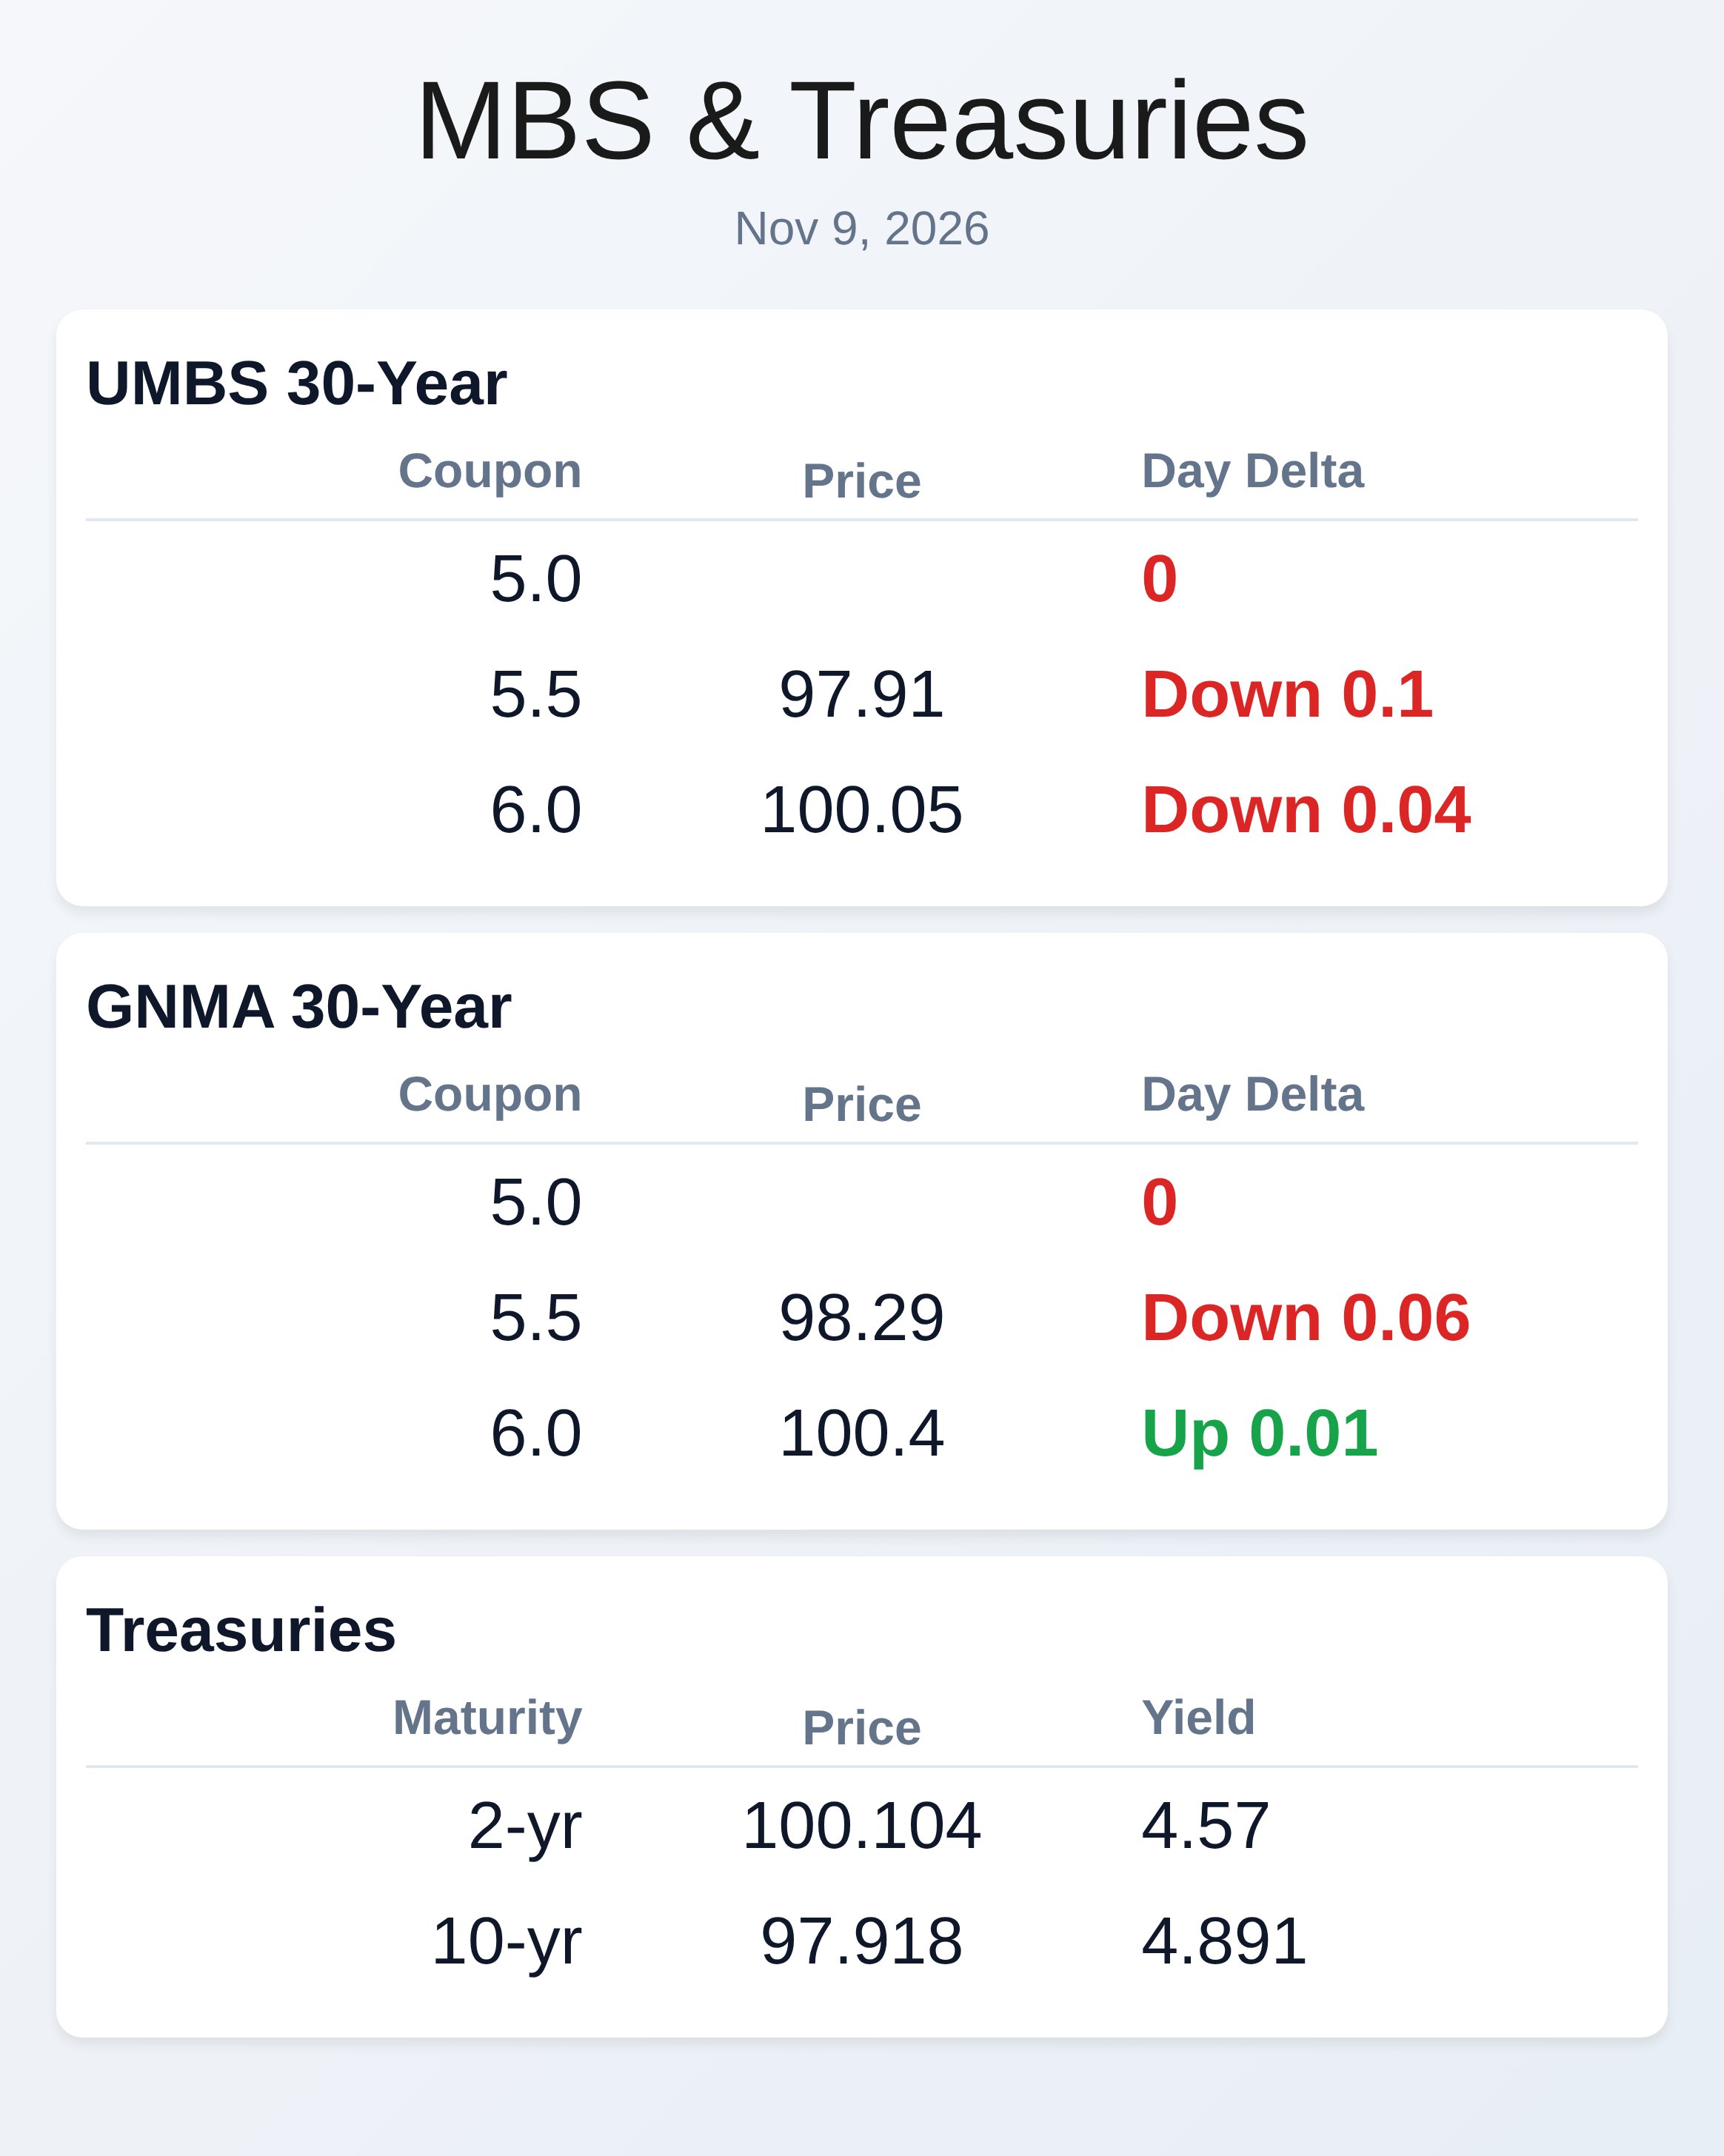
Bonds held their ground despite a stock rebound, with UMBS 6.0 near 100.09 (-0.01) and the 10-year Treasury up modestly to 4.88%. After last week’s rally, trading suggests rates are getting comfortable at these levels. MBS price changes were small and orderly through the session.
Lenders saw only limited negative reprice risk intraday. CPI now moves to center stage. The recent bond rally has been most sensitive to “neocloud”/AI tech jitters; today’s equity bounce didn’t meaningfully unwind that support.
Softer oil prices provided an additional tailwind. Post‑election volatility cooled, and markets refocused on data. Treasury supply remains a background factor, but not a primary driver today.
Net effect: consolidation, not capitulation. Near-term catalysts arrive quickly: Tuesday’s CPI and later-week PPI can shift the rate path. Treasury auctions and corporate supply may add cross‑currents.
A benign inflation print could extend the rally; a hot one risks a push back toward 4.93–5.00% in 10s. Until then, price action implies “wait-and-see” over wholesale repositioning. Keep intraday equity swings on the radar.
In coupons, 30‑year UMBS 6.0 slipped a tick while 6.5s added a hair, reflecting a steady curve and manageable convexity. GNMA 6.0 lagged slightly, down 0.04. Mortgage spreads were broadly stable as desks marked minor moves rather than trends.
Primary mortgage rates remain in the low‑7s on average, with lender‑level dispersion tied to coupon mix and hedging. Liquidity was decent for a Monday. On the origination side, equity is the story: homeowners hold a record ~$17.5T, and cash‑out is now the bulk of refi locks.
Servicer retention on refis fell to 27%, meaning most cash‑out borrowers are leaving their current lender. That’s an opening for proactive outreach and HELOC/second‑lien options. ARM share continues to tick higher as buyers hunt payment relief.
Housing remains mixed: inventory is improving and buyers have more leverage, yet payments rose ~13% YoY with flat headline prices as rates did the heavy lifting. Expect slower pendings into year‑end and a cautious start to 2027 without clearer rate relief. For now, focus on payment‑centric structures, buydowns, and equity‑based solutions to keep deals live.
**Locking vs Floating**
With CPI tomorrow, near‑term risk skews to volatility rather than trend change. Risk‑averse pipelines should favor locking on workable quotes, especially for closings inside two weeks. Risk‑tolerant borrowers can float cautiously, using clear triggers near 10‑year yield resistance at ~4.93–5.00% and locking on adverse breaks.
Expect whipsaws around the print; keep repricing thresholds tight, particularly on lower‑liquidity coupons. Bigger, sustained gains still likely require renewed tech/AI sector stress or cooler inflation.
**Today’s Events**
– 1:00 PM ET: 3-Year Treasury Note Auction (indicative award 4.932%)
– Tomorrow: CPI (key market catalyst)
– Roll Date – UMBS 30YR (Tuesday)
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |