**WTMS Blog Today = What’s up in Mortgage Today (AM) – 11/10/2026**
Hotter CPI slammed bonds this morning, with core +0.3% m/m (vs. 0.2% est) and headline +0.4% (vs. 0.3% est) pushing the 10-year back toward 4.90–4.95%.
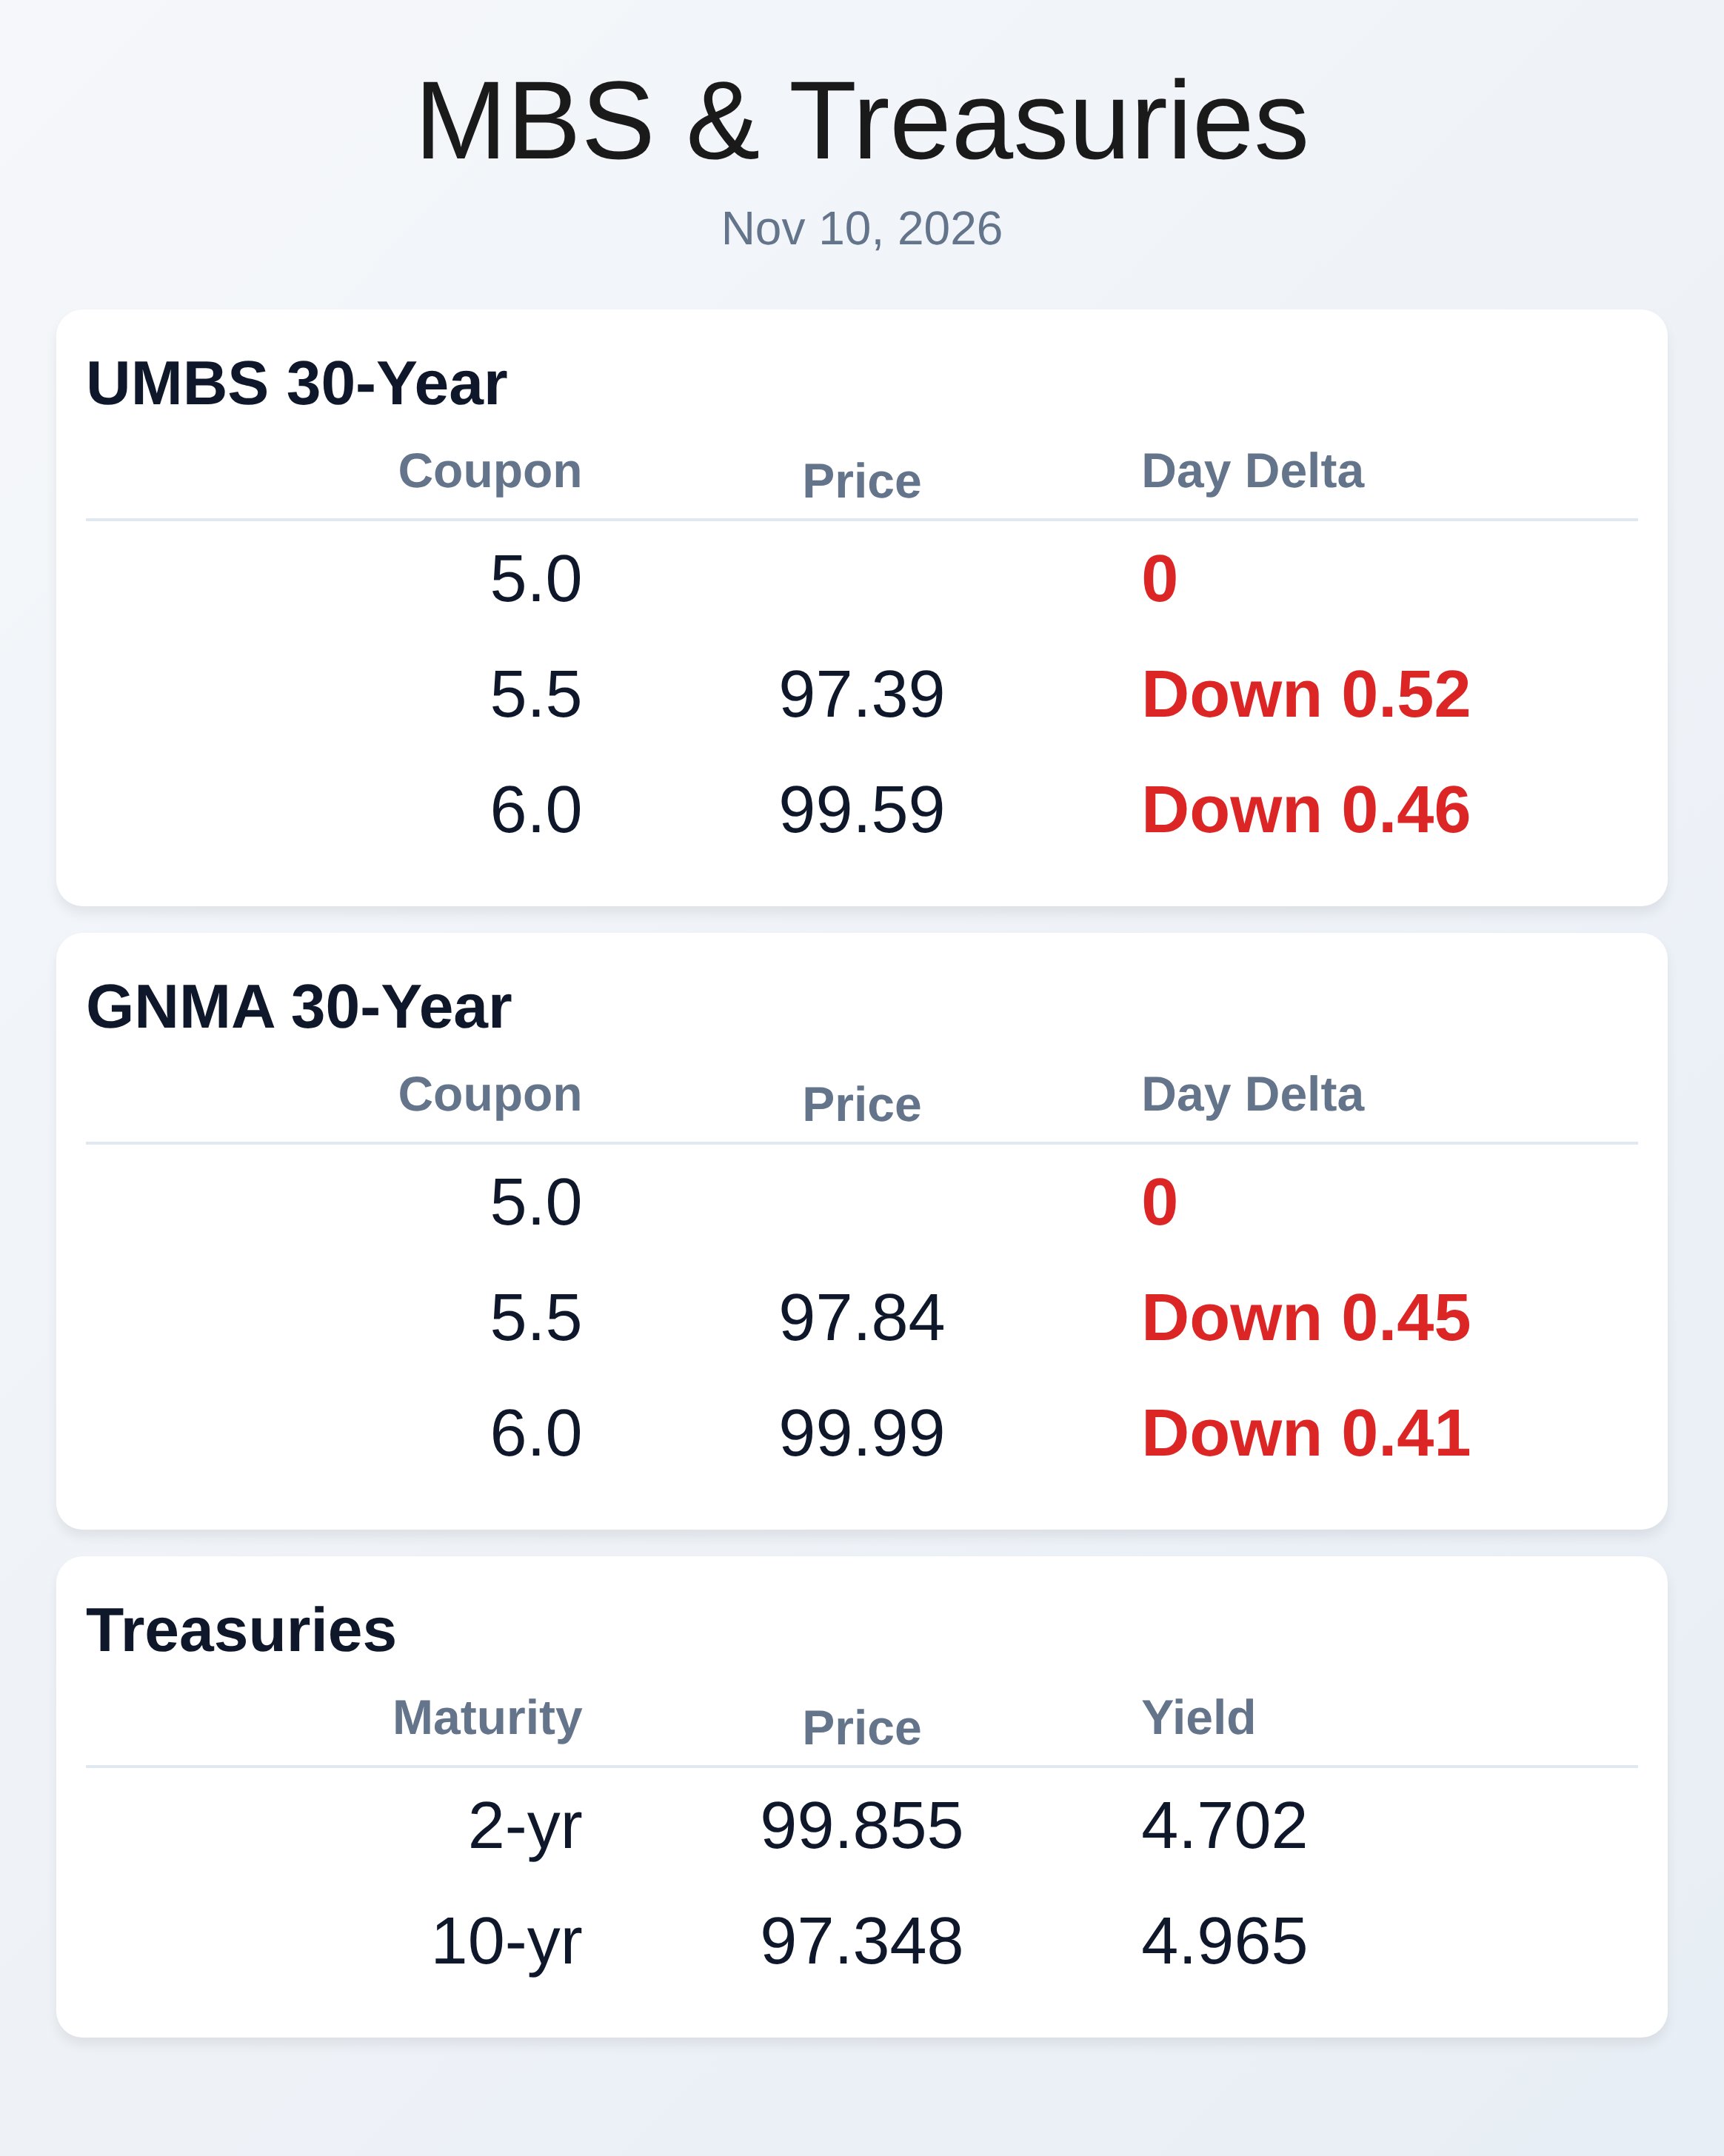
UMBS prices slipped on the print as Fed Governor Waller backed a December hike and said he’d support a larger move if inflation re-accelerates. Rate sheets face renewed pressure after last week’s relief. Markets now lean more decisively toward a December move while watching how much of today’s weakness passes through to primary mortgage pricing.
Expect intraday volatility around the 10-year auction. The backdrop remains whipsaw volatility: an AI-led equity selloff and a sharp oil drop briefly rekindled a flight-to-quality, pulling the 10-year below 5.0% late last week. That rally stalled as tech stabilized and policy hawks reasserted the inflation fight, leaving MBS lagging Treasuries on spread.
With convexity still a headwind, production coupons haven’t fully captured the Treasury rally. For secondary teams, that means two‑sided risk into auctions and data. On the mortgage tape, prepayments slowed in October (Ginnie speeds -14.8% m/m; conventional -9.2%), and refinancing incentives remain scarce with the modeled par rate still near 7%.
ARM usage continues to climb (October locks ~17%) as borrowers hunt monthly savings. GNMA liquidity remains orderly, but mid-coupon UMBS/GNMA 5.0–6.0s offer the best relative value if volatility moderates. Expect servicing-heavy names to benefit near-term from slower speeds despite today’s rate pop.
Origination flow is mixed: MBA apps dipped last week (purchases -2% w/w; -19% y/y), though TransUnion’s Q2 showed originations +12.8% y/y with HELOCs +20.3%. Competitive dynamics are shifting—Zillow Home Loans’ FHA down-payment assistance (a 0%/no‑payment subordinate forgivable after five years) raises the bar on borrower offers, not just rates. LOs should lead with total-cost solutions (buys, ARMs, buydowns, HELOCs) and be ready to counter real-time with fully priced scenarios.
Pipeline hedgers face familiar “rally fades/risk lingers” math: a further rate rise widens MBS basis; a bond bid shortens duration and forces hedge trims. Keep lock desks nimble into supply and data, and prioritize execution where investor appetite is deepest in higher coupons. Explain rate-sheet moves proactively—especially around auction tails and CPI‑driven reprices—to reduce concession creep.
Housing demand is still constrained: October contract signings fell 17% y/y to a record low for the month, even as active listings rose 7.4% and median asking prices eased 2.2%. Cancellations were steady at 7.8%, but fewer fresh listings (-7.5% y/y) limit true inventory churn. Translation: tighter pipelines, longer cycle times, and more rate sensitivity per file.
Focus on turn-times, lock discipline, and cost-to-manufacture.
**Locking vs Floating**
With the CPI miss and a 10-year auction on deck, bias tilts toward locking on day-of-closing and short-horizon loans; float only if you have cushion, time, and a defined stop. The 10-year’s 5.00% area remains a key pivot—failed rallies there have reversed quickly.
Recent bond strength was tech/oil driven, not a fundamental disinflation shift; treat rate dips as tactical. Be ready for headline whipsaws and negative reprices through the auction window. Take wins early if pricing meets borrower goals.
**Today’s Events**
– October CPI: headline +0.4% m/m; core +0.3% m/m
– U.S. 10-year Treasury auction (1:00 PM ET)
– Fed speakers: Waller, Logan, Schmid
– NFIB Small Business Optimism (AM)
– Wholesale Inventories (PM)
Subscribe free for daily brevity at WellThatMakesSense.com.