**WTMS Blog Today = What’s up in Mortgage Today (AM) – 11/13/2026**
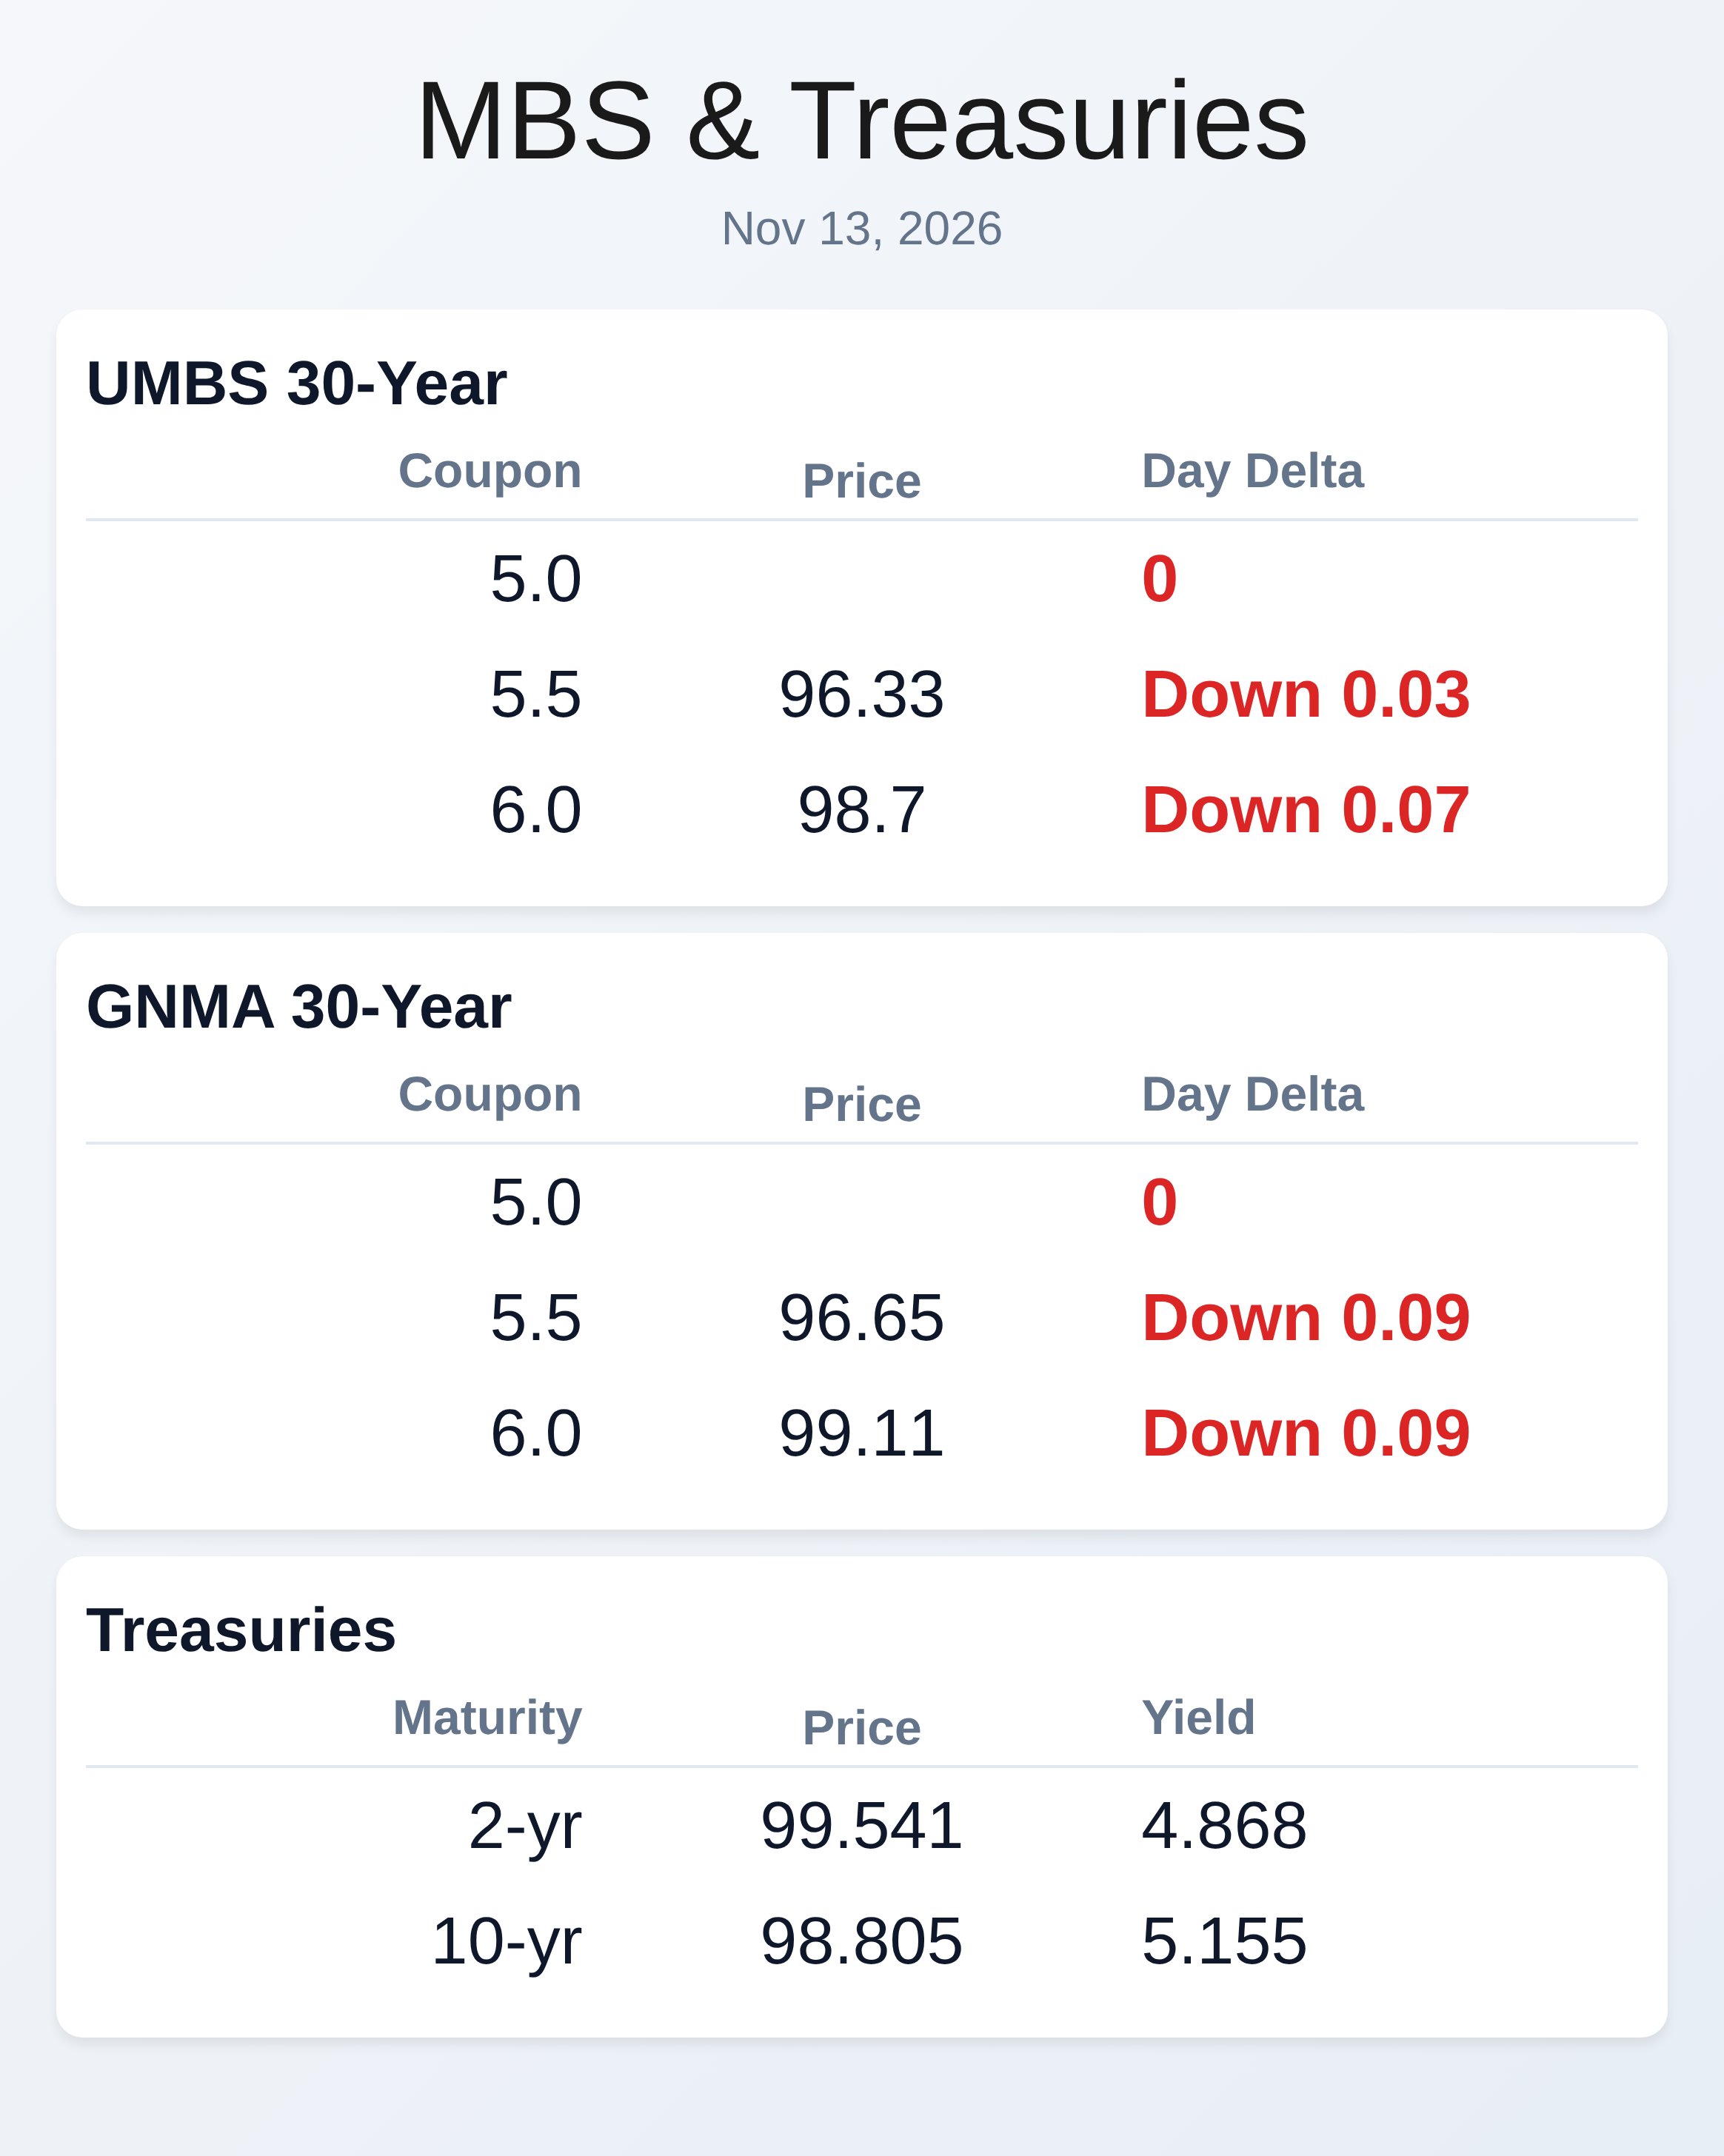
Rates are back on the defensive after this week’s hotter CPI and a still-firm PPI, with the 10-year yield hovering near 5.1 percent and UMBS production coupons giving back part of the early‑November rally. The market is now leaning toward a December Fed hike and even entertaining odds of another move early next year. Expect intraday volatility around auctions and any oil headlines, which have increasingly swayed duration.
For lenders, that translates to choppier best‑ex and higher negative‑reprice risk as bid/ask widens into year‑end. Keep an eye on convexity grabs if stocks wobble again. Ginnie Mae continues to carry more of the production load: it accounted for roughly 47 percent of October agency issuance and ~42 percent year‑to‑date, as more borrowers qualify through FHA/VA.
Prepayments slowed broadly in October, with FN and GNMA speeds both lower, reflecting elevated rates, seasonal cooling, and scarcer refi incentives. That mix shift matters: GNMA pools tend to run lower‑credit, higher DQ sensitivity, and different servicer advance dynamics, which feeds back into spec payups, liquidity, and MSR marks. Positioning around mid‑coupon, seasoned GNMA remains a pricing lever.
But credit dispersion will stay front and center into 2027. Origination showed a brief pulse: MBA apps rose 6.2 percent week over week, helped by the recent dip in rates, though purchase remains down ~18 percent year over year and refi down ~57 percent. Lock mix reflects affordability triage: ARM share climbed toward cycle highs, FHA share is firm, and lenders are leaning into buydowns and second‑lien equity solutions where first‑lien refis make little sense.
Operationally, lenders are prioritizing fast eligibility decisions, clean pricing/LLPA explanations, and investor appetite for higher coupons. Expect more interest in HELOC/CES and DSCR, but execution risk rises as volumes fragment. Housing activity is soft into the holidays.
Existing home sales fell 5.5 percent in October to a 3.75 million annual pace, the weakest since 2010, while several trackers flagged record‑low October contract signings. Inventory is edging higher and price gains are flattening in more metros, giving buyers slightly better leverage on concessions even as monthly payments bite. Cancellations remain contained, suggesting most contracts that get to mutual acceptance still close.
Builders continue to rely on incentives and rate buydowns to clear backlog, which helps new‑home share but pressures gross margins. Credit policy is in flux. Some investors are piloting VantageScore 4.0 acceptance alongside Classic FICO, but adoption is uneven and price grids are not uniform; lenders that cherry‑pick scores risk downstream execution surprises.
At the same time, the CFPB has pulled back on some supervisory activity but is reviewing ATR/QM and Reg X servicing rules—governance, model risk, and fair‑lending documentation still need to be airtight. Net: price and eligibility choice is expanding, not simplifying, so secondary policy should be explicit about acceptable score models by product, channel, and take‑out. Tactically, treat rallies as opportunities to lock and reduce pipeline basis risk, not as a green light to float.
Production coupons remain headline‑sensitive, and auctions plus Fed‑speak can flip tone quickly. For borrower strategy, emphasize total cost of funds: points, permanent/temporary buydowns, ARM vs fixed break‑evens, and second‑lien equity versus cash‑out. FHA/VA remain powerful tools for payment relief and eligibility—close cleanly, reduce repurchase risk, and preserve MSR value.
Keep LO desks primed with fast‑turn scenario answers as bid/ask and overlays shift intraday.
**Locking vs Floating**
The recent rally was driven more by tech‑sector angst and short‑covering than by a durable shift in inflation, and bonds have since stalled near major resistance. With CPI/PPI out and auctions still ahead, risk is two‑sided but skewed toward volatility; don’t be complacent about a quick give‑back.
Lock on lender‑friendly bounces, especially for short turn times and thinner margins. Floating only makes sense on longer lead files with cushion and clear reprice triggers. In all cases, have a plan for negative reprice risk if yields push decisively back above 5 percent.
**Today’s Events**
October PPI and Core PPI were released this morning, both up 0.3 percent month over month. Several Fed officials speak today, including Collins, Logan, Bowman, Daly, and Jefferson; markets will parse remarks for December hike signals. Subscribe free for daily mortgage intel at WellThatMakesSense.com.