**WTMS Blog Today = What’s up in Mortgage Today (PM) – 11/11/2026**
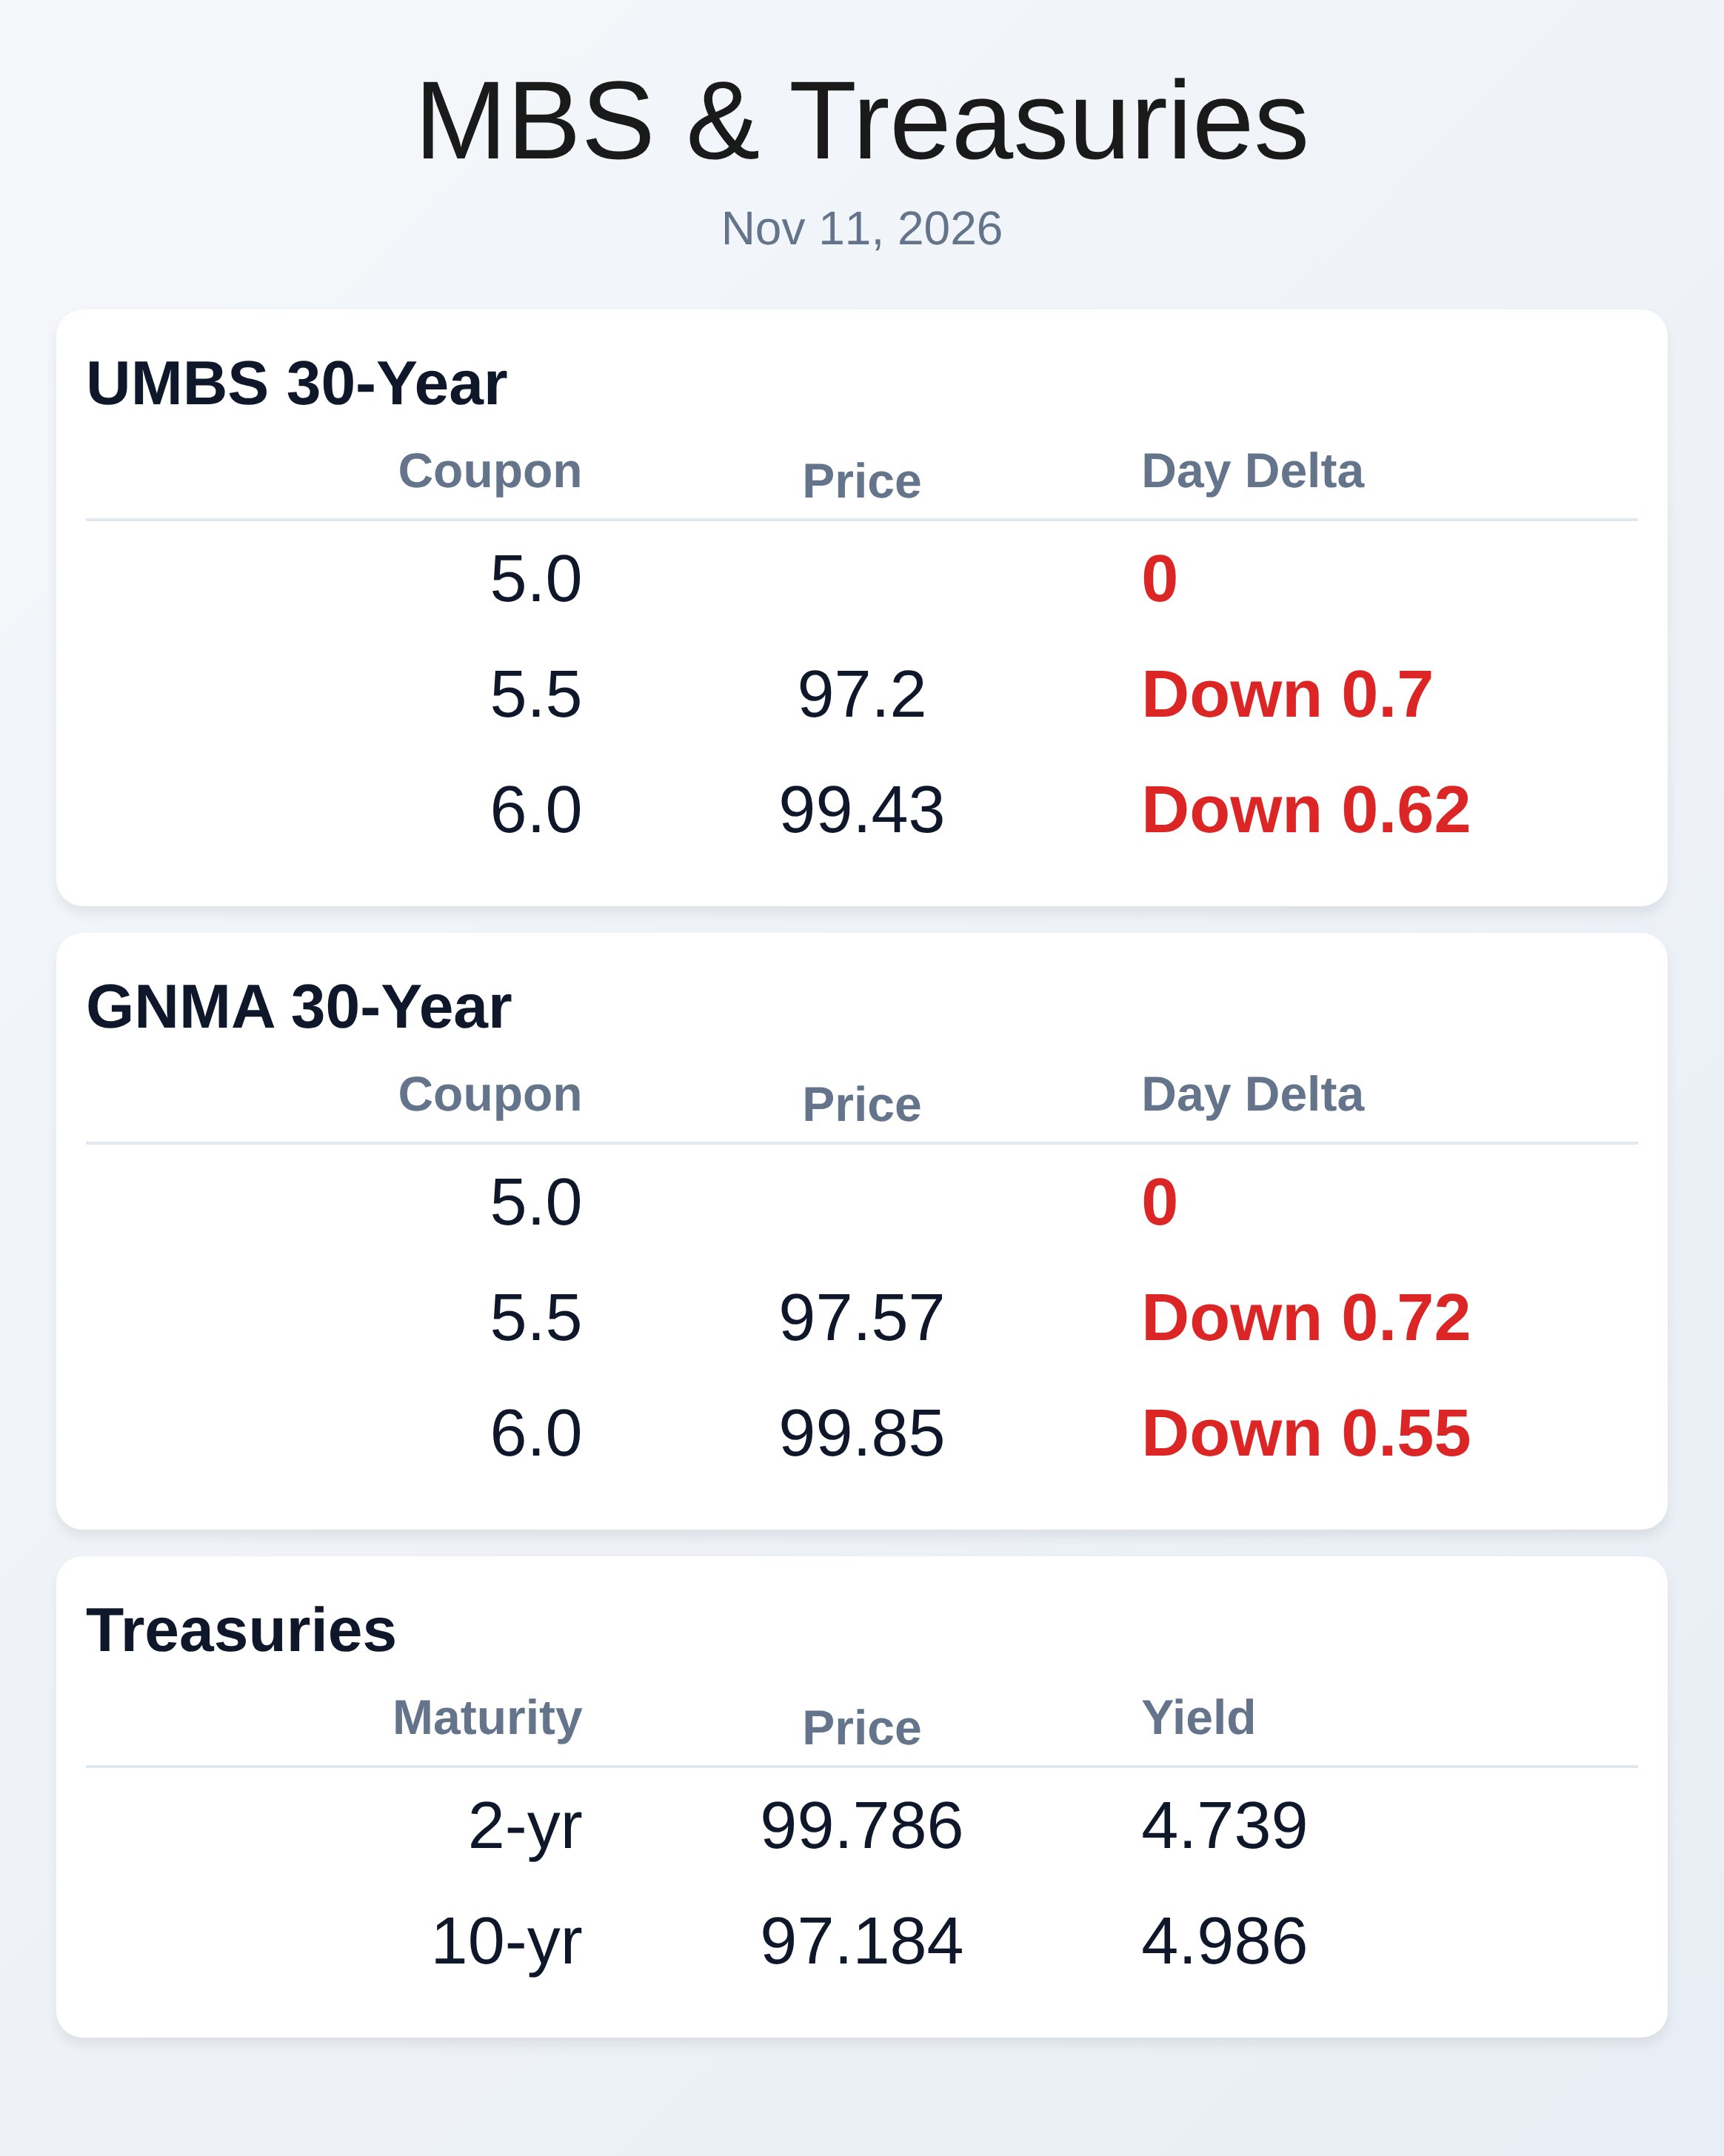
Hotter CPI slammed bonds Tuesday, delivering the biggest selloff since September and knocking UMBS prices sharply lower while pushing yields higher. UMBS 6.0 fell roughly 5/8ths and the 10-year Treasury jumped about 10 bps to near 4.98%. There weren’t any “yeah, but” nuances in the report—core ran hot and Fed-dated pricing shifted toward more tightening risk.
Shorter maturities led the weakness, but the damage reached the long end and mortgages. With markets closed today for Veterans Day, Thursday becomes the first test of whether rates can stabilize. The selloff interrupts a two‑week rally that had been fueled by tech/AI credit jitters and falling oil, which drove safe‑haven bids into Treasuries and MBS.
Earlier this week, “neocloud” weakness lined up well with bond gains, helping nudge rates to the best levels in a month. Even so, bonds had already been reluctant to extend the rally as stocks bounced and oil wobbled. CPI now puts the burden back on data and tech sentiment to keep rates improving.
Without fresh fuel, the friendly trend is at risk. Ginnie Mae performance echoed conventionals, with GNMA 6.0 down about 0.59 on CPI day after catching a bid during last week’s equity slide. Spreads versus Treasuries have been choppy as mortgage convexity and rate‑lock flows amplify swings.
The good news: despite CPI, mortgages didn’t underperform disastrously versus the long end. The bad news: renewed volatility can widen spreads and dent primary rate improvements. Watch how MBS track the 10‑year on the next risk‑off day.
Technically, the 10‑year has been oscillating between support near 4.82–4.88 and resistance at 4.93–5.00–5.07. Tuesday’s break back above 4.93 and toward 5.00 argues for caution until yields convincingly reenter the lower zone. Near‑term direction likely hinges on whether tech jitters re‑intensify and oil remains subdued.
A decisive move back below 4.93 would reopen the door to October’s gains. A sustained hold above 5.00 would keep sellers in control. On the origination front, margins and volume remain tight, pushing lenders to compete on pricing and process.
UWM swung to a profit with cost cuts and MSR tactics, and it’s dangling a 40 bps incentive tied to broker tech adoption, while Rocket’s Quick Counter aims to help brokers salvage refis against rival offers. Retention is the pressure point: ICE says servicers kept only 27% of refi borrowers, with cash‑outs driving most runoff. Translation: cash‑out equity taps are up for grabs if you get there first.
Demand remains soft even after a modest rate pullback before CPI. MBA reported applications slipping again, and Zillow says typical payments are up 12.8% year over year despite flat home prices, keeping affordability strained. Inventory is improving and leverage is shifting toward buyers, but not enough to spark a sales rebound yet.
ARMs are inching higher as payment relief becomes paramount, and VA remains an underused channel with meaningful room for growth. Expect “price versus payment” to dominate borrower decisions into year‑end.
**Locking vs Floating**
The CPI surprise puts the recent rally on notice, with rates vulnerable if yields hold above 4.93–5.00% on the 10‑year.
Risk‑tolerant borrowers can float only if tech/AI credit jitters re‑accelerate or data cools; otherwise, use intraday strength to lock. Holiday closures can exaggerate swings, so be mindful of headline‑driven gaps. For tactical triggers, treat 4.93% and 5.00% as lock thresholds and 4.88%/4.82% as floors that would need reclaiming to restore momentum.
Until new, bond‑friendly catalysts appear, the bias tilts defensive. Subscribe free for daily briefs at WellThatMakesSense.com.