**WTMS Blog Today = What’s up in Mortgage Today (PM) – 09/21/2026**
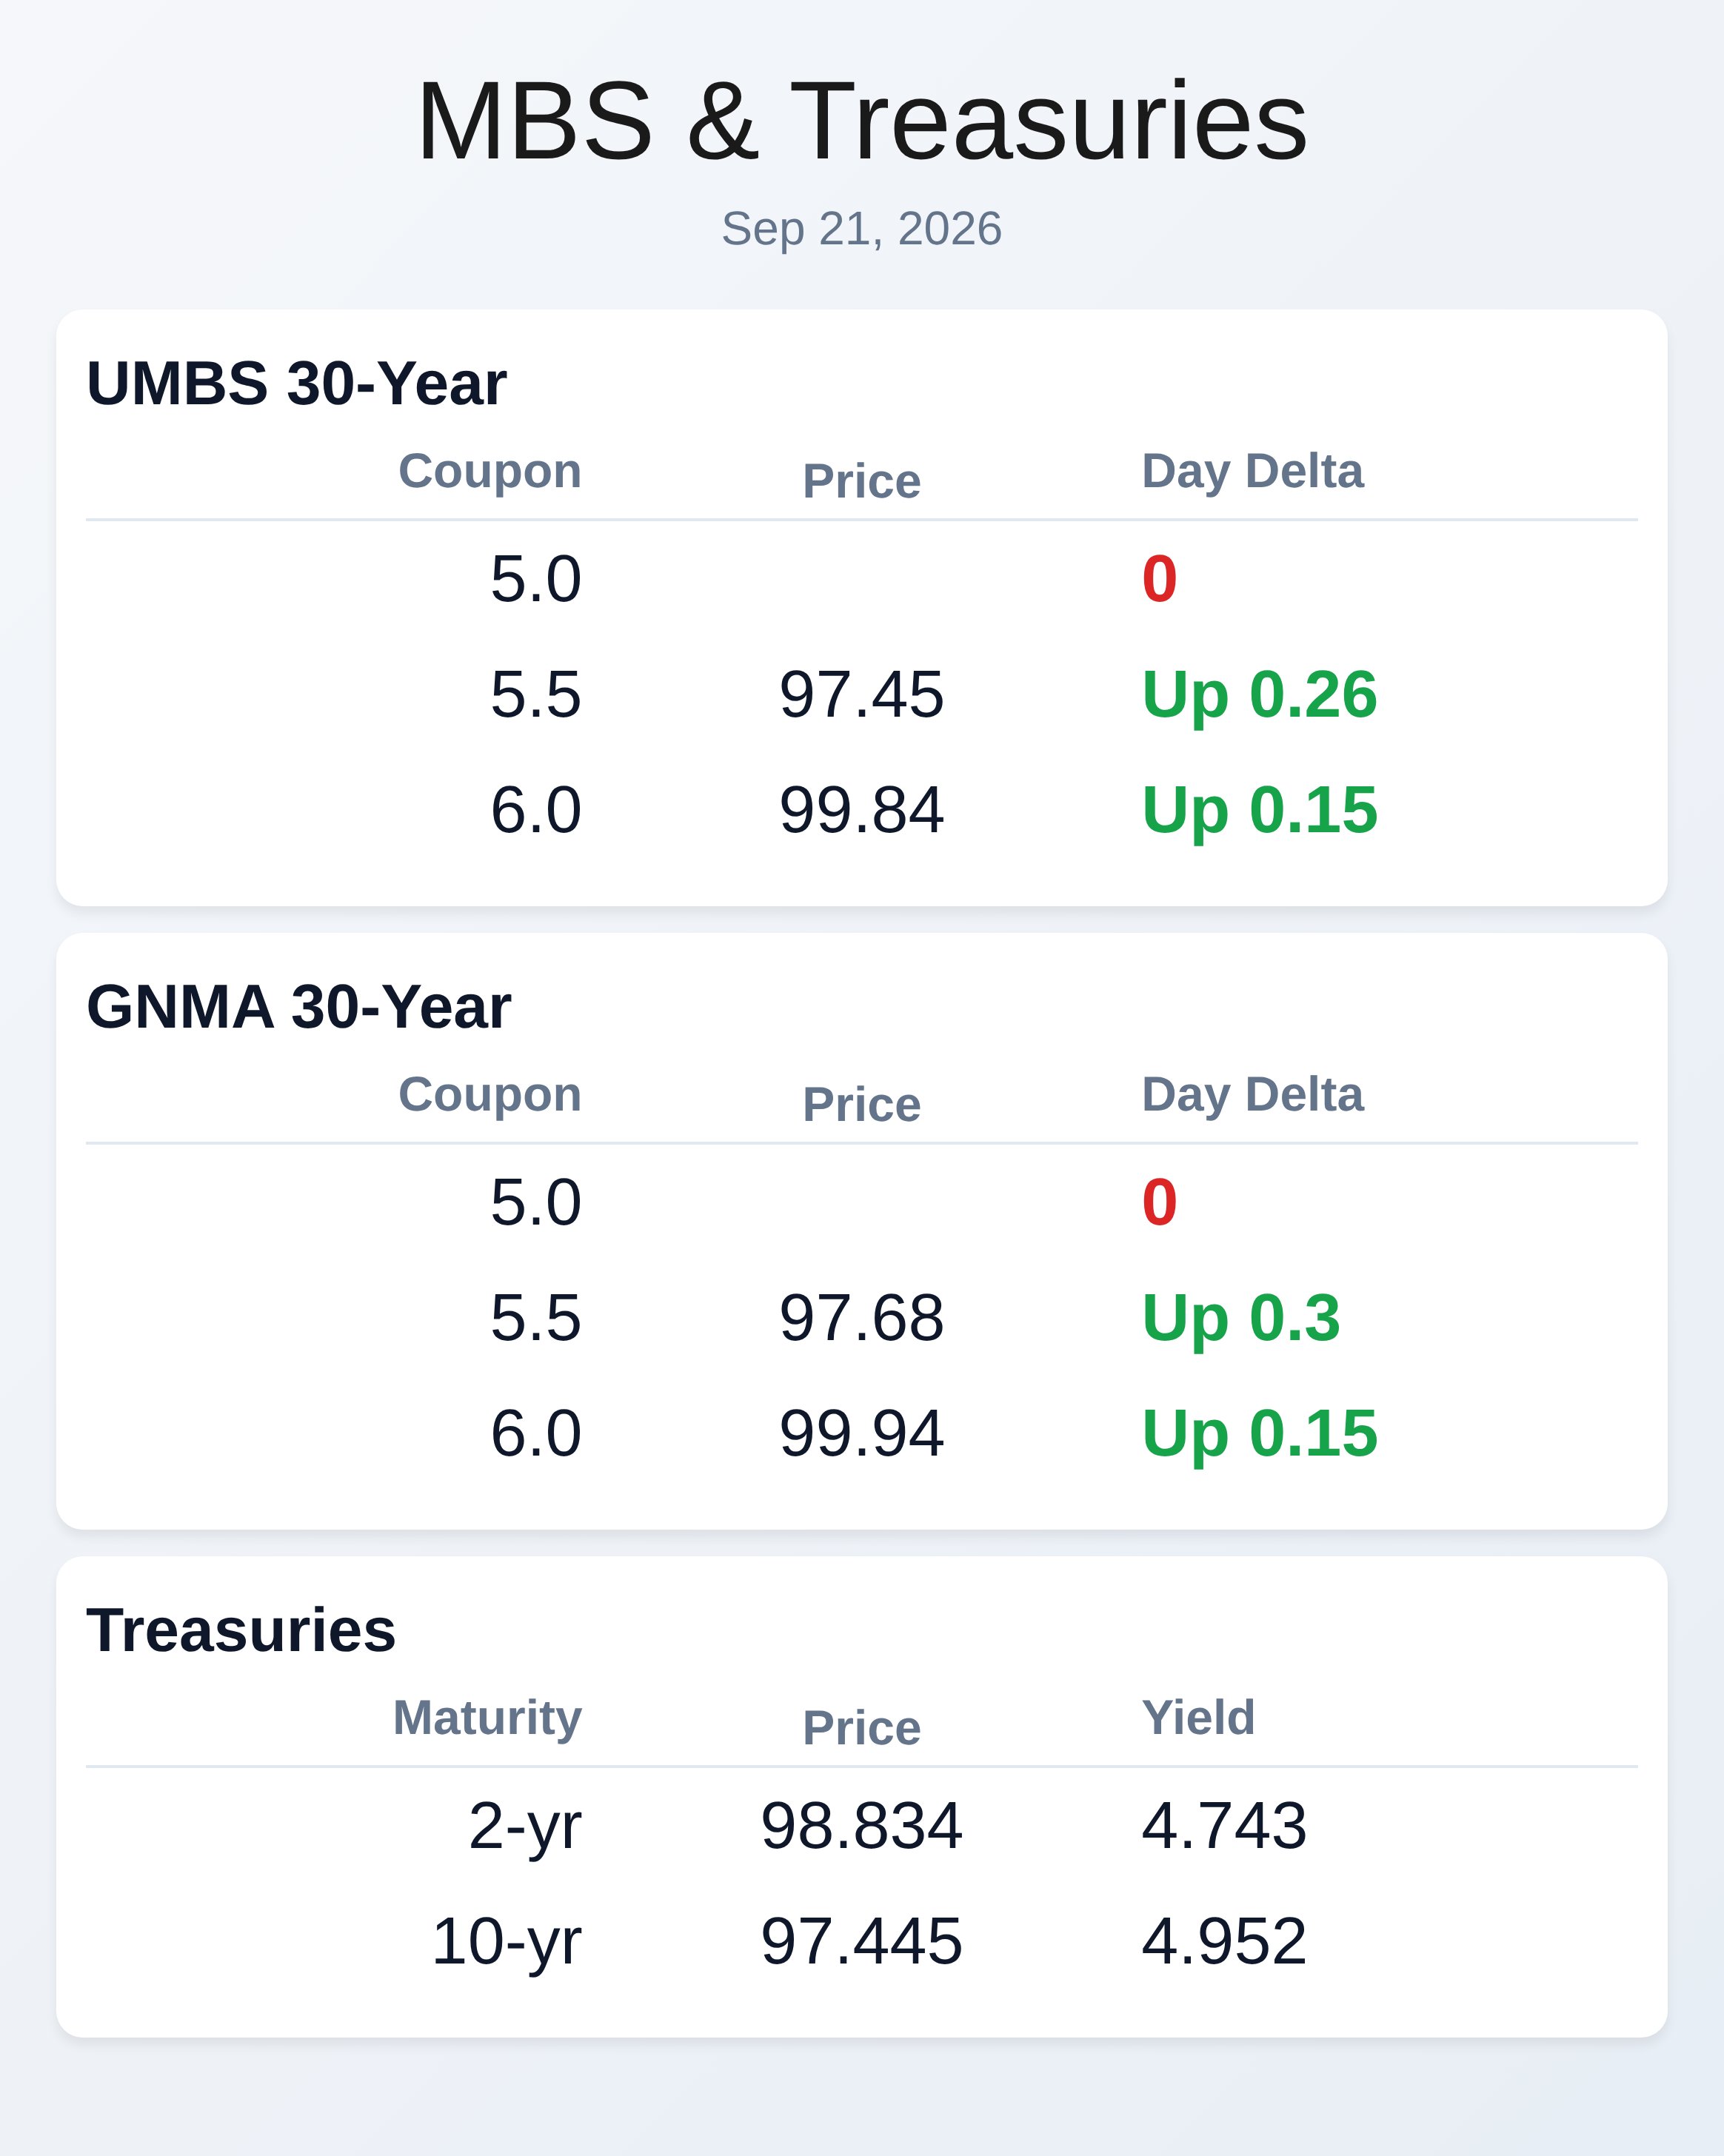
Bond markets finished sideways with a slight bid after an uneventful trading day in narrow ranges. The 10-year Treasury retreated 4.8 basis points to close near 4.95%, testing but failing to break the critical 4.94% technical level that would signal a meaningful rally ahead. UMBS 6.0 coupons gained 13 basis points to 99.82, while GNMA 6.0 coupons moved up 13 basis points to 99.91, suggesting modest security appetite despite persistent uncertainty about the Fed’s remaining rate path.
Mortgage origination forecasts are being cut sharply across the industry as rates have climbed and volumes decline. The Mortgage Bankers Association trimmed its 2027 forecast to $2.101 trillion from $2.144 trillion, with most analysts now expecting rates to settle near 6.7% through year-end. PennyMac’s preliminary third-quarter data shows only $16.6 billion funded in July and August combined, pointing to roughly a 28% drop from second-quarter’s monthly pace.
Argus Research estimates volumes could fall at least 5% in the third quarter compared to the second quarter if rate levels persist. Better’s internal corporate meltdown is shaping up as one of the year’s most dramatic founder-versus-board conflicts. Vishal Garg and investor Daniel Lewis exchanged thousands of messages over roughly a year, bonding over corporate finance and distressed debt trading before Lewis joined the board in late July and orchestrated Garg’s ouster within eight days.
Garg is now attempting to remove Lewis and four other directors while Better has sued Garg for waging a “scorched-earth campaign,” with both sides weaponizing private communications that paint a troubling picture of management philosophy at the troubled lender. Mutual of Omaha is exploring a strategic sale of its mortgage division after hiring Houlihan Lokey to assess options. The division operates 954 loan officers, produced $11.2 billion in volume over the past 12 months, and maintains 158 branches nationwide, making it one of the larger mortgage M&A opportunities this year.
The reverse mortgage footprint alone is significant—Mutual of Omaha held the second-largest HECM position in 2026 with 3,343 endorsements through August, trailing only Finance of America, after leading the market in 2025 with 5,740 endorsements. A hidden opportunity exists in the September 27 through October 3 window when Realtor.com data shows buyers encounter more listings, less competition, and asking prices roughly $14,000 below summer peaks. However, last week’s 19-basis-point rate increase adds approximately $42 to monthly payments on an average $332,800 loan, consuming more than half of the price benefit and pressuring buyers with older preapprovals.
Loan officers should proactively contact borrowers who stepped away to refresh numbers and explore whether seller concessions or temporary buydown structures could make deals viable. AmeriTrust Mortgage is pursuing a $14.1 million lawsuit against investors, brokers, appraisers, and title companies over an alleged Baltimore-area DSCR fraud scheme involving roughly 90 investment-property loans. The complaint alleges properties purchased for $40,000 to $50,000 were quickly resold to affiliated entities for approximately $200,000, with financing based on inflated values that triggered immediate defaults and repurchase demands.
This case underscores escalating industry warnings about DSCR loans featuring weak property valuations, questionable rental income, and inadequate counterparty verification that warehouse lenders and Wall Street have grown increasingly nervous about.
**Locking vs Floating**
Technical support and resistance levels remain crucial for lock-float decisions. The 4.94% level in 10-year yields represents important resistance; breaking below it could signal an early rally confirmation.
The 5.00% ceiling must remain intact to avoid further upward pressure. Until yields definitively shift below 4.94%, the market stance favors conservative positioning in both lock and float recommendations rather than aggressive betting on substantial rate declines.
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
**GNMA 30yr**
| Coupon | Price | Intra-Day Change |
|—:|—:|—:|
| 5.5 | 97.68 | 0.3 |
| 6.0 | 99.94 | 0.15 |
| 6.5 | 101.67 | 0.07 |
**US Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
|—|—:|—:|—:|
| 2 yr | 4.743 | 98.834 | -0.012 |
| 3 yr | 4.813 | 98.791 | -0.025 |
| 5 yr | 4.827 | 98.013 | -0.035 |
| 7 yr | 4.882 | 97.76 | -0.047 |
| 10 yr | 4.952 | 97.445 | -0.048 |
| 30 yr | 5.284 | 97.619 | -0.043 |
Subscribe free to WTMS Blog at WellThatMakesSense.com to receive daily market insights for mortgage originators.