Loading...
HOME2023-01-22T13:43:33-07:00

“Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (PM) - 10/30/26 {{catlist}}
October 30, 2026
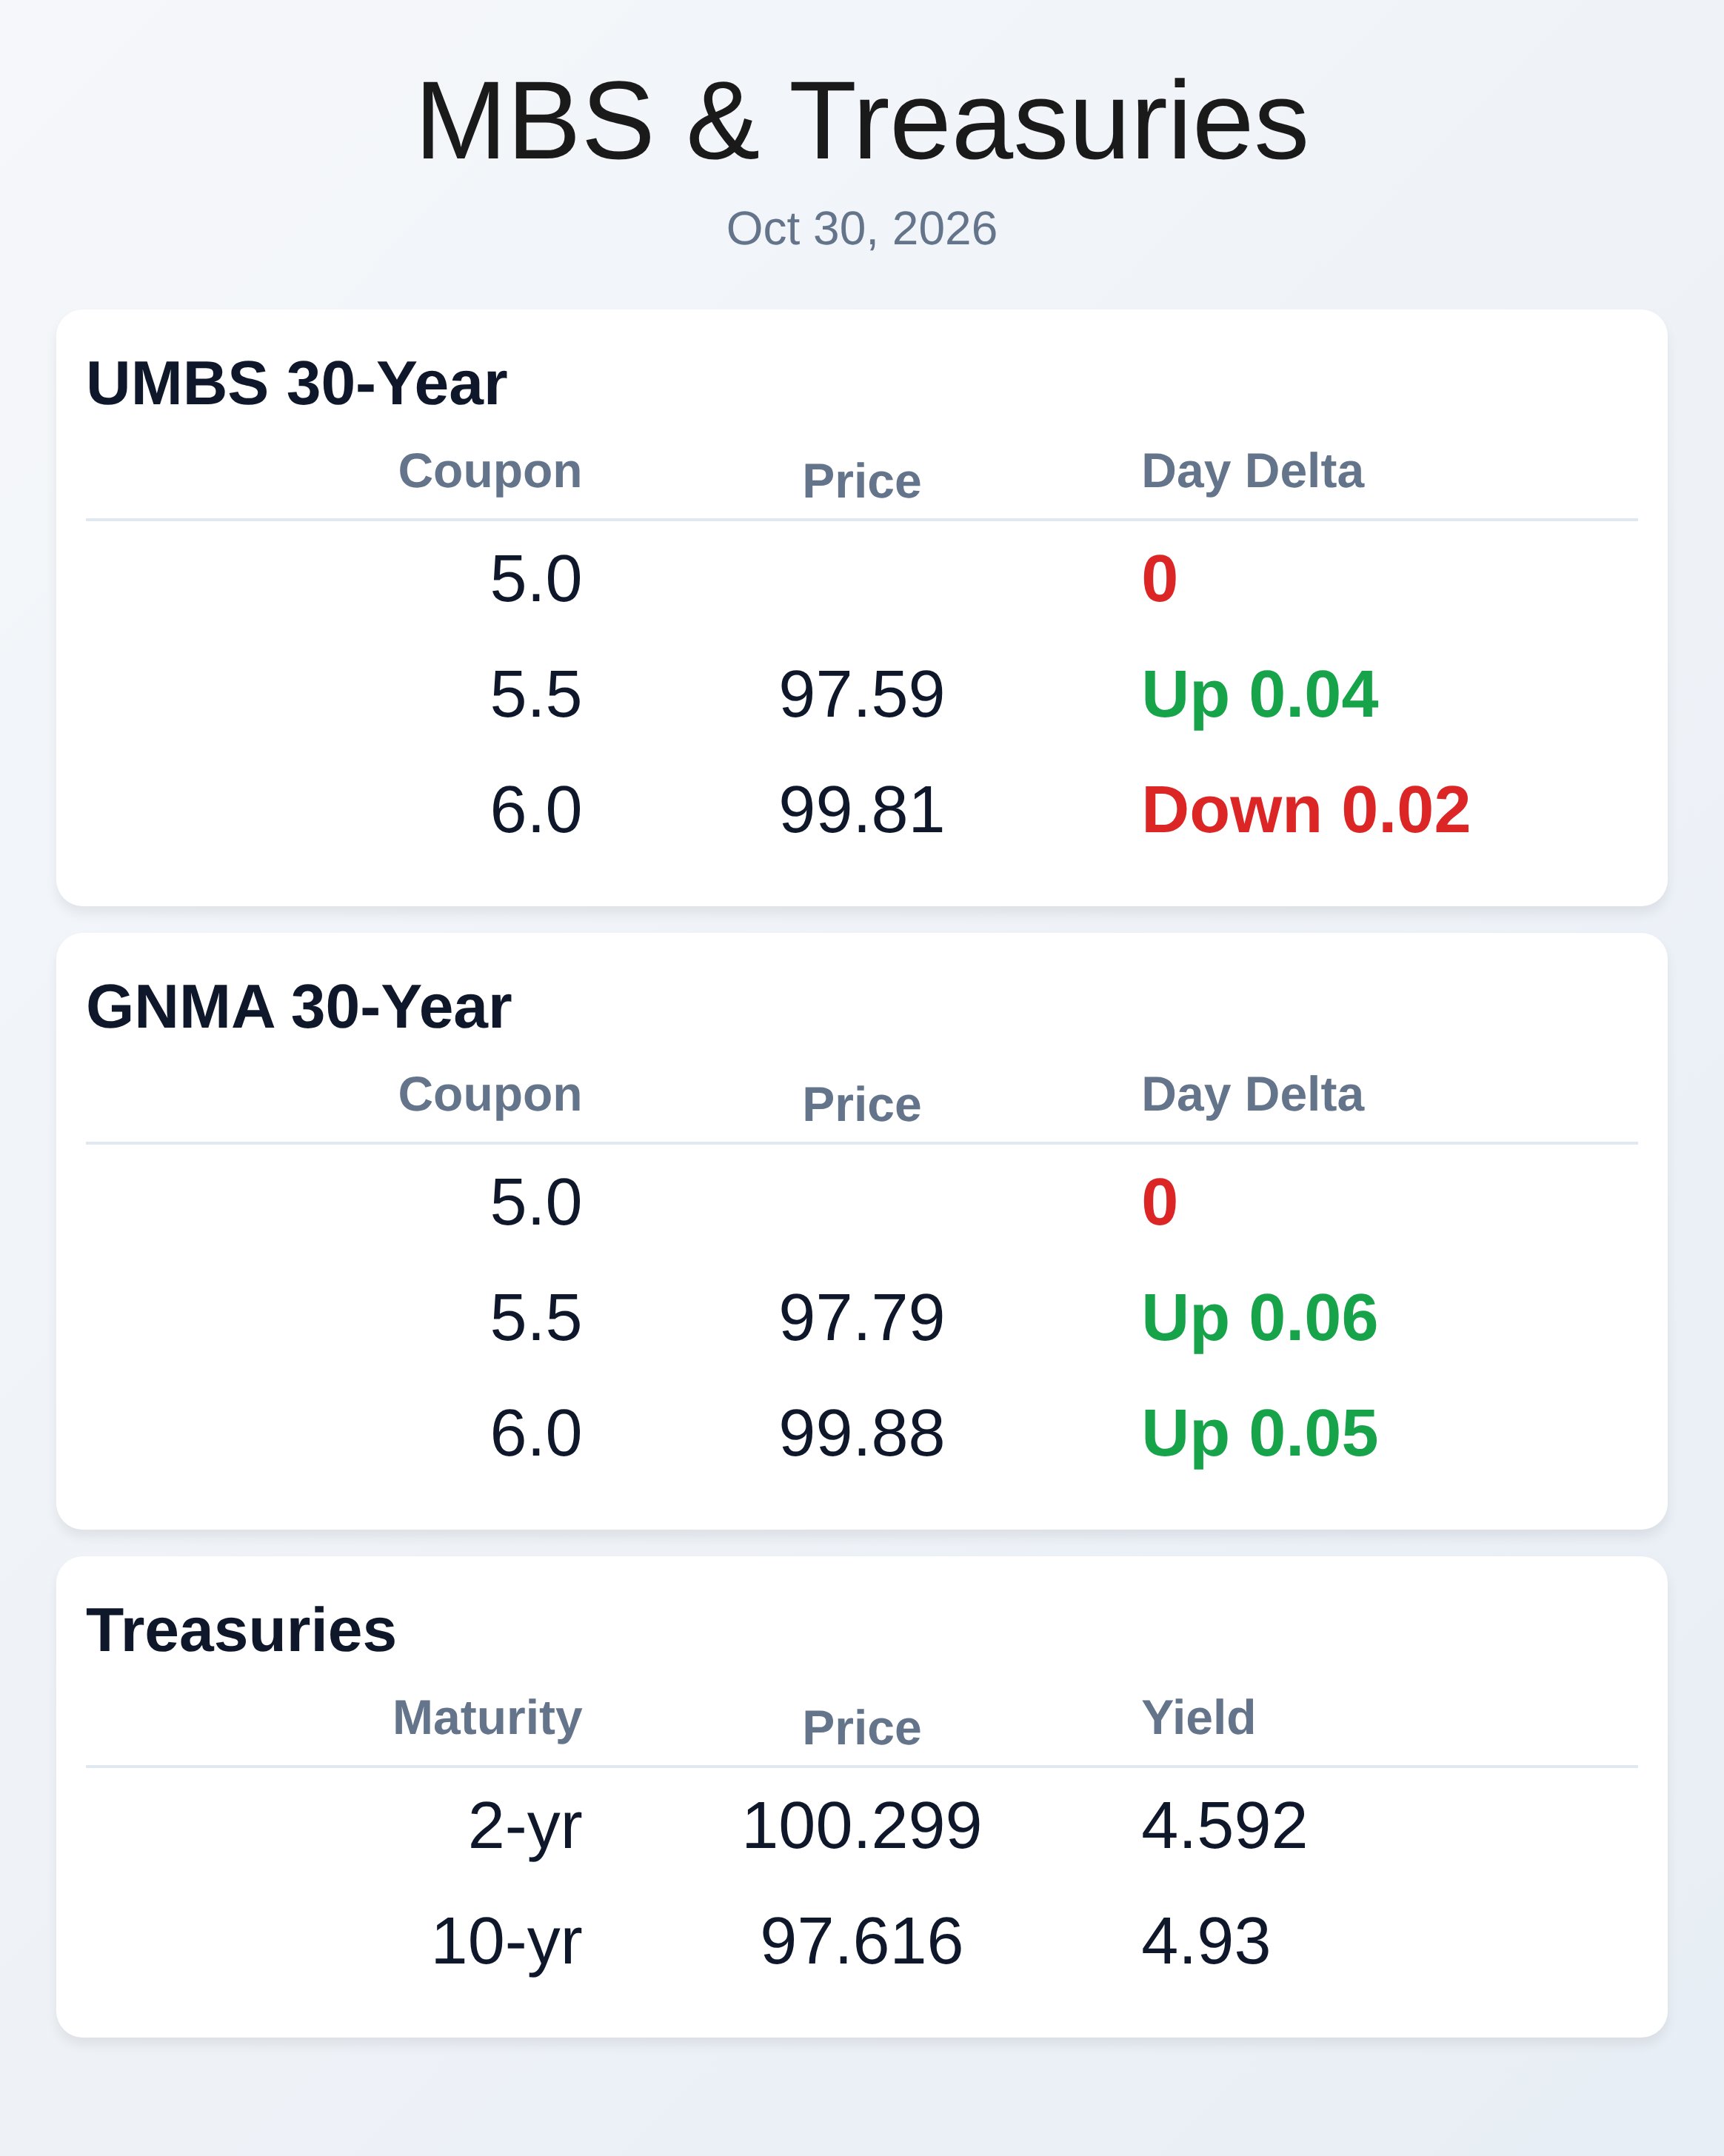
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 10/30/2026** UMBS rallied into the close Thursday and held steady Friday as tech-stock jitters kept safe‑haven bids alive. The 30‑year UMBS 6.0 traded around 99.8 late Thursday, up roughly 5/8ths on the day, while the 10‑year Treasury yield dipped back below 5%. Price action has been driven less by data and more by risk-off flows tied to AI/data‑center credit headlines. Even so, the rally has paused at familiar levels near 5.00% in the 10‑year. Intraday volatility remains elevated. Ginnie Mae coupons participated in the move. GNMA 6.0s finished Thursday near 99.8, up roughly 0.3, with FHA/VA rate sheets improving modestly. Conventional stacks outperformed earlier in the week, but GNMA caught up as buyers leaned into liquidity. Spreads versus Treasuries remain wider than normal, keeping primary/secondary spreads sticky. Pipeline hedgers should mind coupon selection as carry and liquidity diverge. Macro inputs were mixed. The Fed held rates unchanged and signaled a wait‑and‑see stance, and September core PCE printed 0.3% m/m and 3.1% y/y alongside a 3.4% Q3 GDP pace. The front end of the curve rallied on the Fed tone while long rates treaded water, reinforcing a flatter bias. Net‑net, the data didn’t derail the MBS bid, but it didn’t confirm a bigger downshift in inflation either. Translation: momentum is still headline‑ and tech‑driven. On the desk, earnings underscore the split between production and servicing. Rocket posted sharply higher profits and market‑share gains on a $43.6B quarter, aided by a large MSR platform and strong recapture, while Pennymac leaned on servicing income, announced $29B of MSR sales to reduce debt, and outlined cost cuts as production margins compressed. UWM gave brokers price relief by waiving FHA/VA credit‑score hits through year‑end. CrossCountry said VantageScore 4.0 lifted borrower pricing by about 62 bps in LLPA on average for eligible loans. Competitive execution is increasingly about which scorecard and fee stack you can use for a given borrower. At the policy level, the Administration’s new order pushes cheaper refis via permanent title‑acceptance pilots, potential LLPA relief on qualifying rate‑reduction refis, and borrower‑visible savings. The mortgage‑insurance piece moved to a pilot that applies prospectively, with proactive PMI cancellation based on current values limited to new originations. Net effect: potential refi friction falls if agencies follow through, but operational and documentation standards will decide how fast savings reach consumers. Lenders should prepare disclosures and workflows that pass through any fee reductions cleanly. Watch FHFA guidance for scope and timing. Housing demand remains fragile even as rates eased this week. MBA applications ticked up, ARMs gained share, and multiple metros are now skirting buyer’s‑market territory, yet affordability still binds and buyers are choosier. Programs that lower cash‑to‑close, including DPA and seller concessions, are doing more heavy lifting than price cuts. Use the dip to refresh pre‑approvals, price permanent buydowns versus ARM alternatives, and re‑quote edge files that stalled at last week’s highs. Speed matters when intraday reprices are in play. **Locking vs Floating** The near‑term rate path is being set by “tech jitters” more than data, so rallies can extend or reverse quickly on headlines. With 10‑year yields stalling near 5.00% and resistance below at ~4.93%, close‑in pipelines should favor locking on morning strength to avoid negative reprices. Files with time and tolerance for volatility can float tactically, but only with firm triggers and fast lock execution. Next week’s jobs data can reset momentum; until then, expect choppy, headline‑driven sessions. Coupon selection and hedge discipline matter more than usual. **Today's Events** Core PCE (m/m) Sep: 0.3%; Core PCE (y/y) Sep: 3.1%. GDP Q3: 3.4% annualized. Initial Jobless Claims (week of Oct 24): 194,000. Subscribe free for daily clarity at WellThatMakesSense.com.

Market Data
Mortgage Today (AM) - 10/30/26 {{catlist}}
October 30, 2026
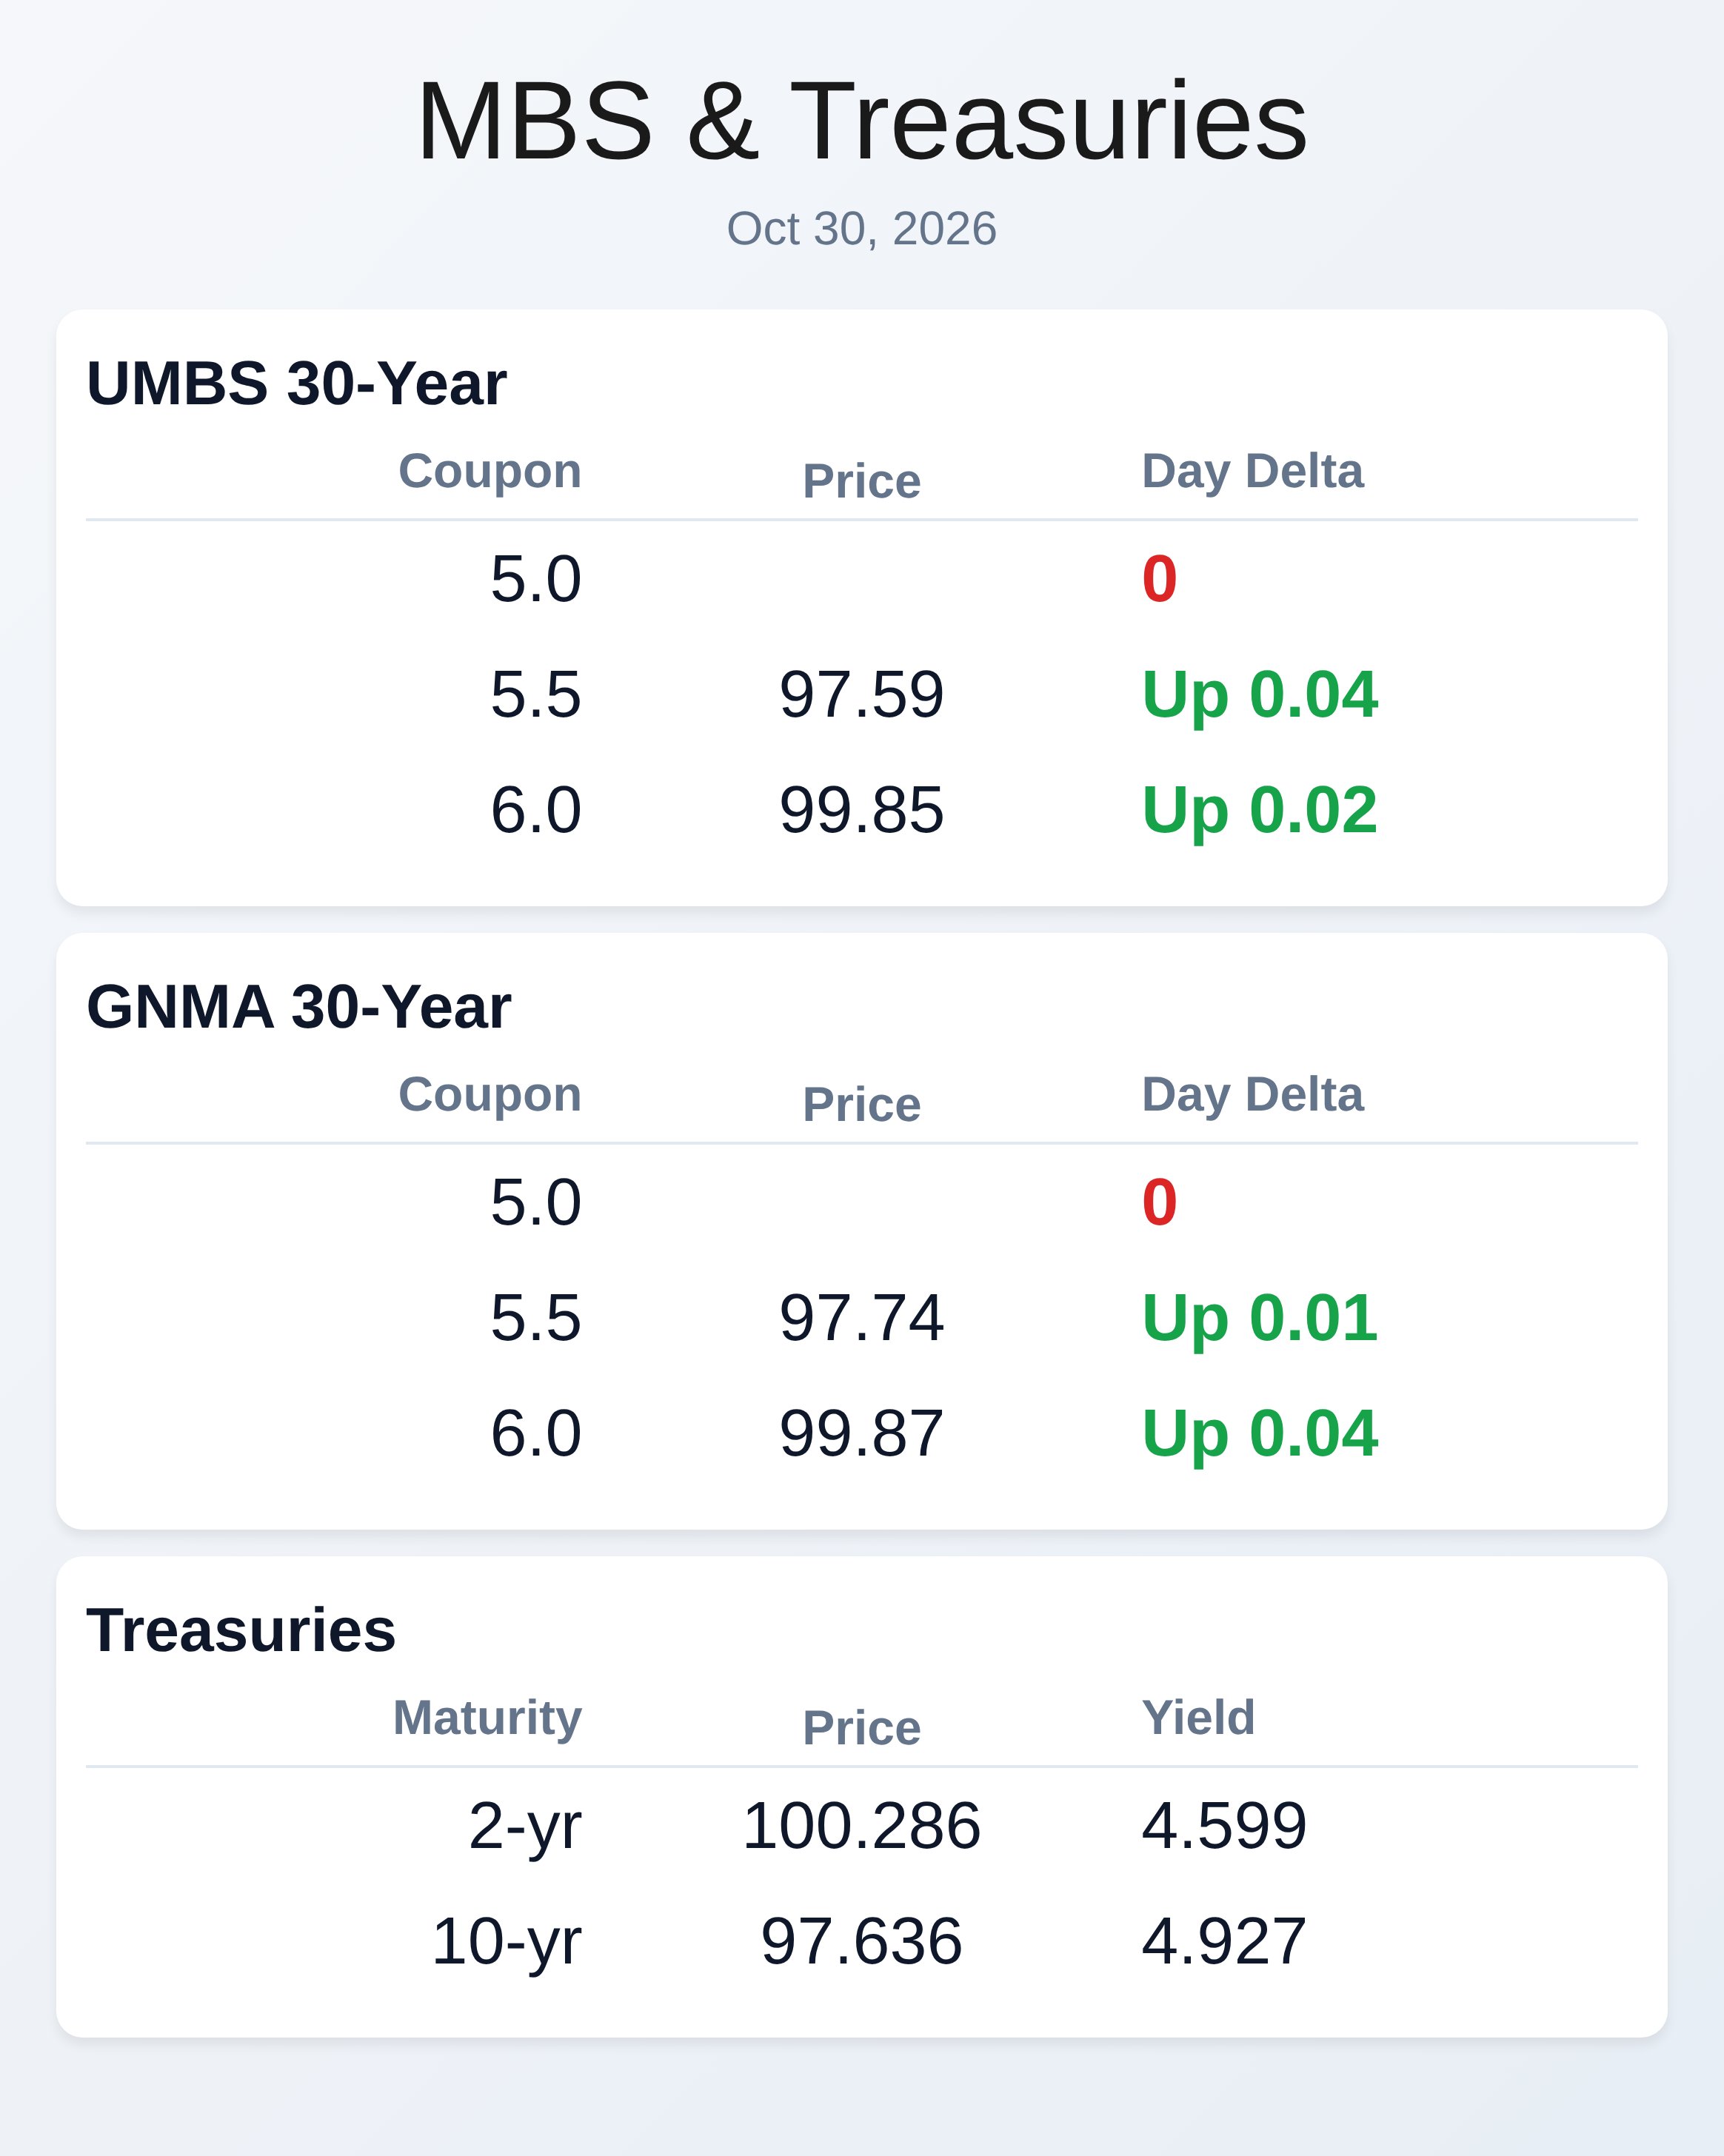
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 10/30/2026** Mortgage rates stumbled lower this week as Treasury yields declined and the Federal Reserve held rates steady, with 10-year Treasuries ending near 4.92 percent by Friday morning. The Fed voted 10-2 to maintain its benchmark rate at 3.75–4.00 percent, signaling patience while acknowledging persistently elevated inflation and resilient economic activity. Chair Kevin Warsh's cautious messaging and announcement that the Fed will conduct only six policy meetings annually instead of eight tamped down near-term rate-hike expectations. Core PCE inflation cooled to 2.5 percent on an annualized basis, offering some relief to fixed-income markets, though headline inflation remains elevated at 3.6 percent year-over-year. Despite three consecutive weeks of rate declines, purchase applications remain 18 percent below year-ago levels and refinancing is down 61 percent, signaling the housing market remains frozen by affordability constraints. Loan officers across the country report that buyers are sitting on the fence longer than in years, using higher ARMs and seeking seller concessions to make deals work. Non-QM production continues to grow, with lenders offering full non-QM suites including bank statements, 1099 income, and DSCR products to capture borrowers outside traditional guidelines. Fannie Mae reported third-quarter net income of $4.2 billion with net worth near $120 billion, while Freddie Mac posted $3.2 billion in earnings, both signaling the GSEs remain well-capitalized despite market headwinds. Optimal Blue's September data showed non-QM volume climbing 8 percent month-over-month and ARM usage reaching 14 percent of locks—the highest since 2019. The mortgage industry continues consolidating, with several mergers announced as lenders pursue scale to offset margin compression and volume decline. **Locking vs Floating** Ground-holding continues as lenders and borrowers assess whether recent rate declines signal a sustainable trend or a temporary reprieve. Technical analysis suggests 10-year yields could test 4.83 percent on the downside, but oil prices above $101 per barrel and persistent geopolitical tensions support an inflation case for higher rates. Lock activity has picked up modestly on the week's rate improvement, but borrower behavior remains hesitant—many are waiting for further evidence that affordability conditions are genuinely improving before committing. **Today's Events** October Chicago PMI and remarks from San Francisco Fed President Daly are scheduled for later today. Q3 Employment Cost Index data released this morning showed +0.8 percent growth, consistent with a resilient labor market despite higher borrowing costs. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change |

Market Data
Mortgage Today (PM) - 10/29/26 {{catlist}}
October 29, 2026
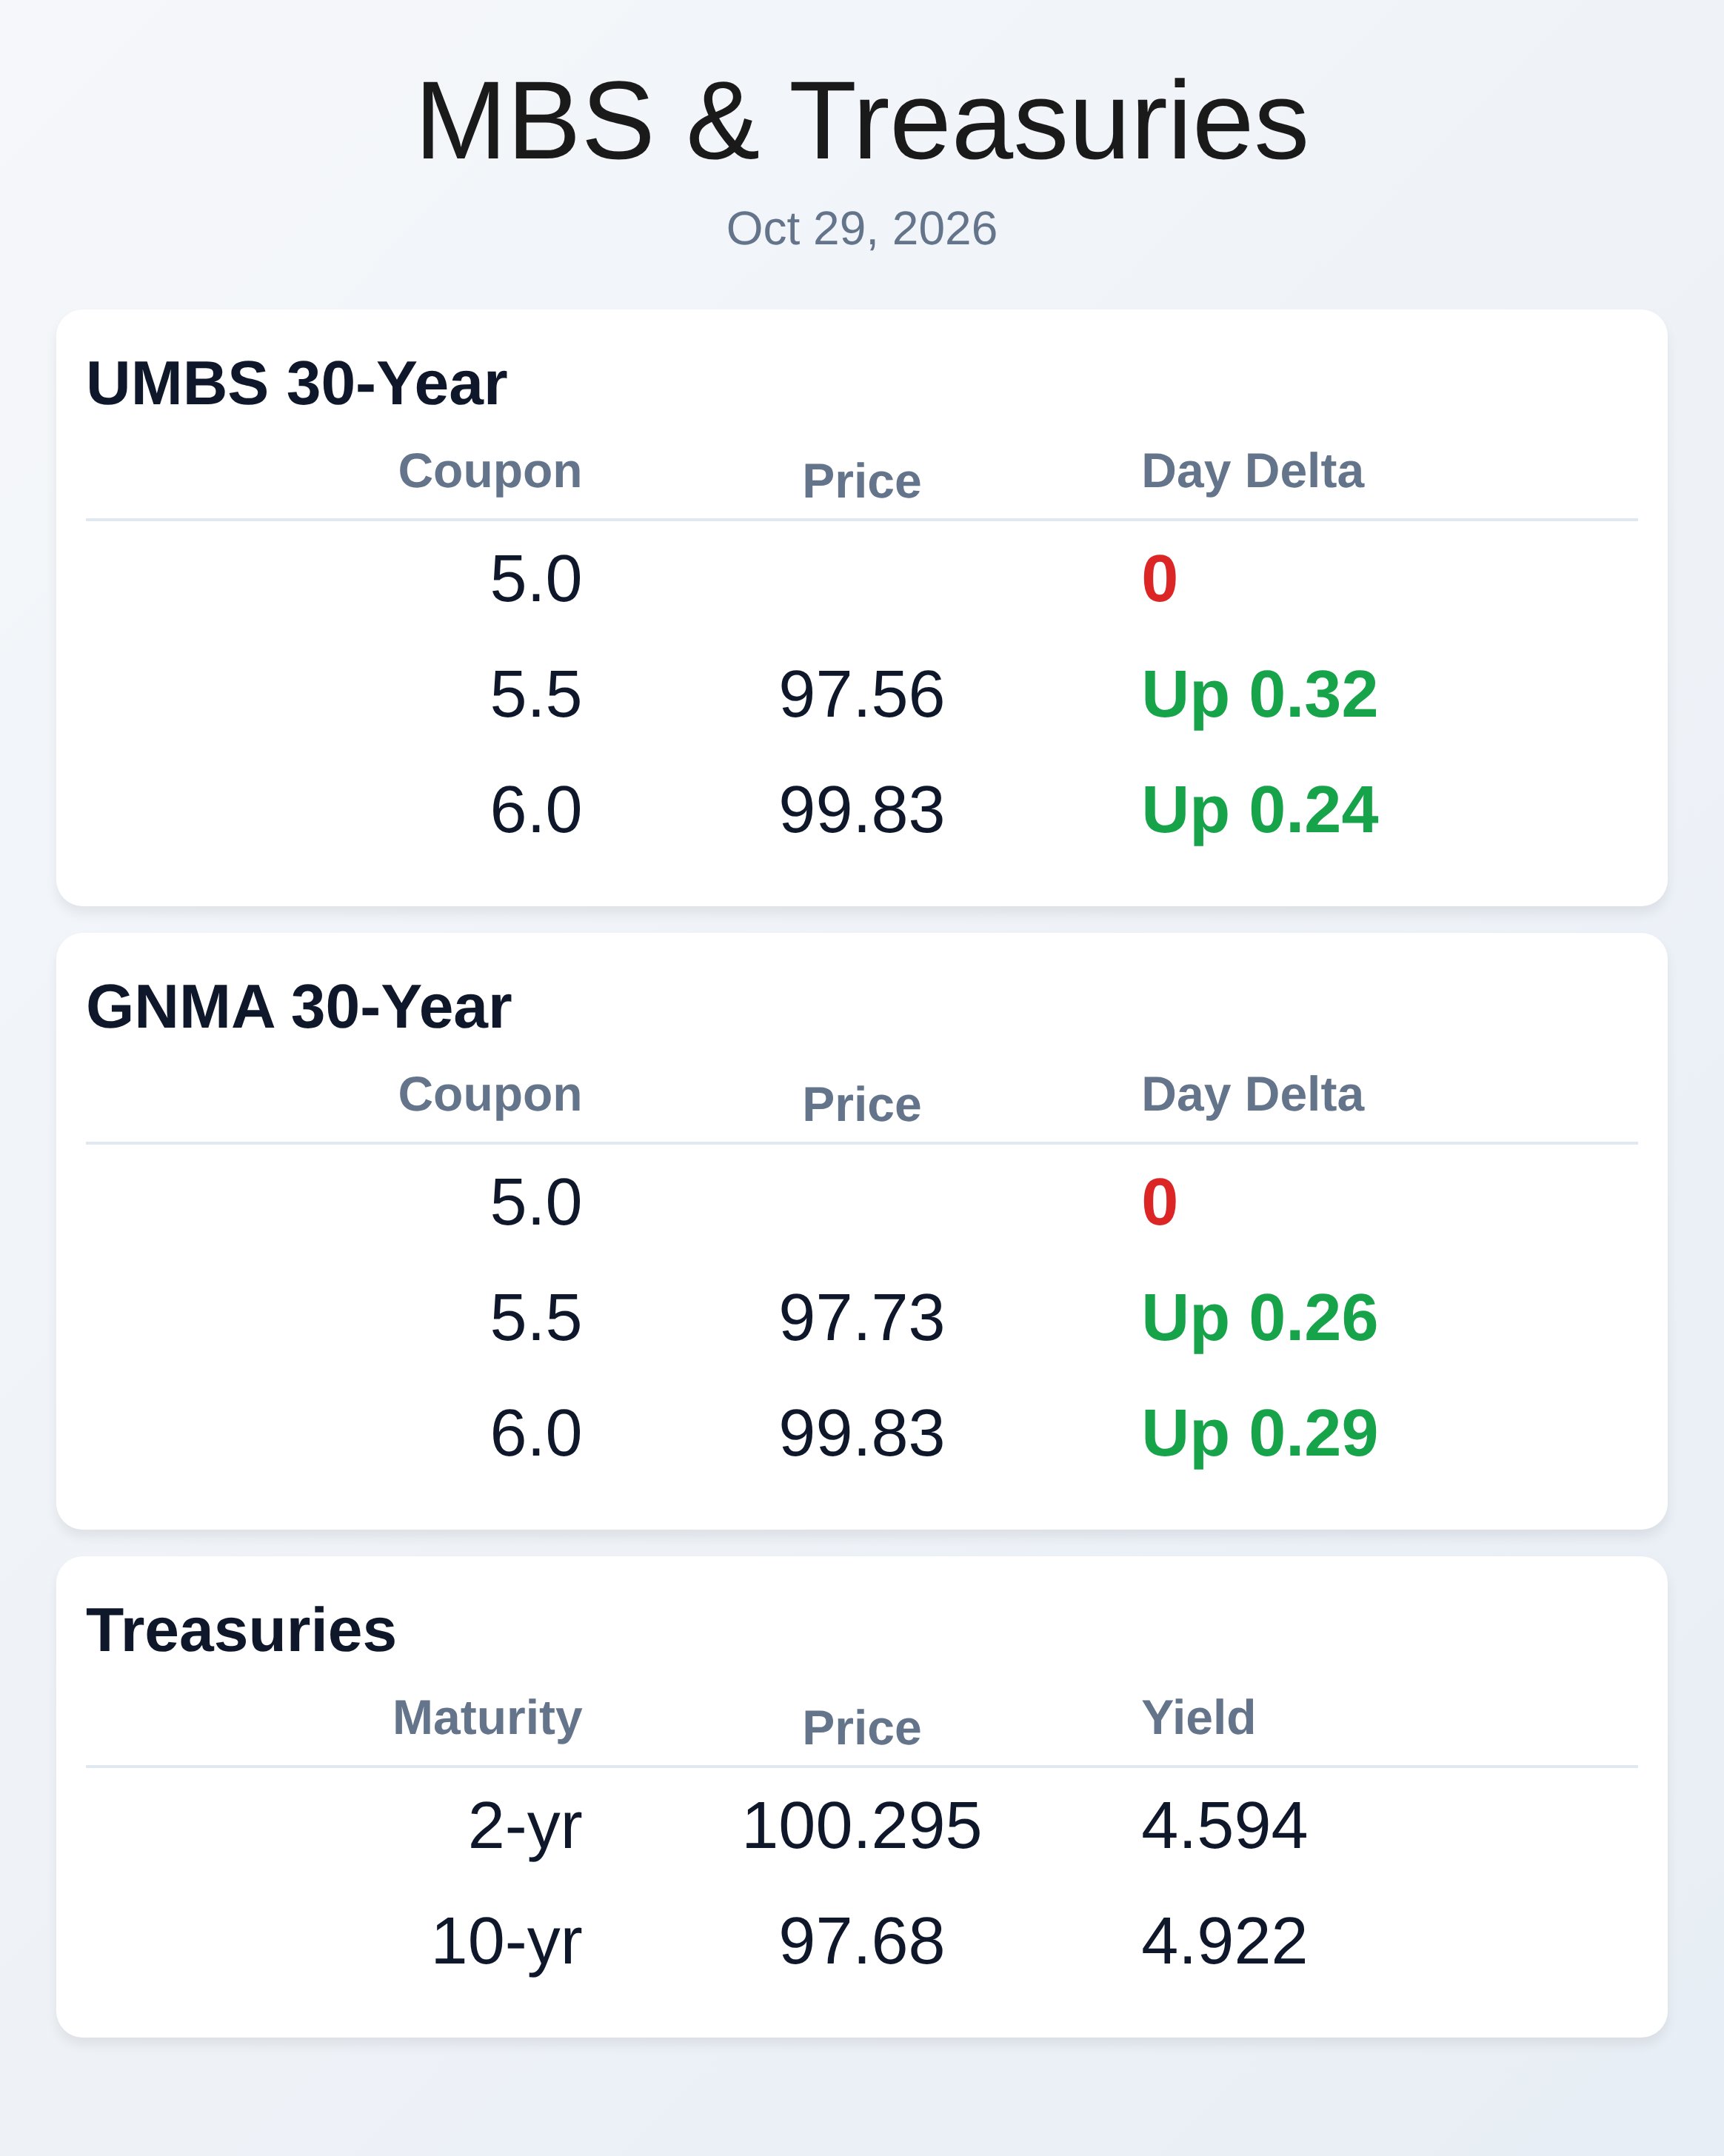
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 10/29/2026** Tech stocks are cratering again, and it's lifting Treasury yields off their lows—a sign that fear of artificial intelligence losses is temporarily overwhelming hawkish Fed rhetoric. The 10-year yield pulled back from 4.92% as Amazon and Google reported disappointing results Thursday morning, triggering another flight to safety in bonds. Agency MBS gained 25 basis points on the week as persistent concerns about tech sector leverage keep investors buying Treasuries over equities. Mortgage applications climbed 3.4% week-over-week after two consecutive weeks of rate declines, though purchase and refi volume remain sharply below year-ago levels. The ARM share of new applications hit 11.3%—the highest in over a year—as borrowers desperate for savings gravitate toward adjustable-rate mortgages. The Federal Reserve held rates steady Wednesday at 3.75% to 4%, offering little relief but also no new hikes despite two officials voting to tighten. Fed Chair Kevin Warsh's comments suggested patience rather than urgency for future moves, and markets reduced rate-hike bets to single digits through year-end. Third-quarter GDP came in hot at 3.4%, beating expectations and reinforcing the economy's underlying resilience despite higher borrowing costs. Core PCE inflation matched forecasts at 0.3% month-over-month, suggesting price pressures may be leveling off, though year-over-year core inflation remains elevated at 3.1%. The mixed signals leave mortgage lenders caught between persistent inflation concerns and growing anxiety about a potential economic slowdown from tech sector weakness. Mortgage originators face brutal economics as volumes decline and pricing pressure mounts. United Wholesale Mortgage is selling $70 billion to $80 billion in mortgage servicing rights to reduce debt, shrinking its $270 billion servicing portfolio and signaling stress across the industry. Enterprise Bank & Trust exited mortgage origination entirely this week, citing lack of scale—another casualty of higher rates and razor-thin margins. Smaller players are consolidating or disappearing entirely as cost structures become unsustainable without sufficient loan volume. The gap between top-performing loan officers and bottom performers has widened dramatically, with education and relationships now separating winners from those leaving the business. CrossCountry Mortgage reported that borrowers using VantageScore 4.0 saw average loan-level pricing adjustments drop 62 basis points, translating to roughly $2,500 in savings over the first 60 days of implementation. The lender removed its 80% loan-to-value cap for conventional loans using the alternative score, expanding eligibility and giving borrowers more options to improve pricing. The shift toward VantageScore continues as Fannie Mae and Freddie Mac diverge on artificial intelligence governance standards, complicating compliance for lenders selling to both enterprises. Fannie's new Section 4 tightens AI model governance, while Freddie focuses on audits and executive approvals—forcing lenders to double down on policy updates and vendor agreements. The credit scoring battlefield is heating up as competition between FICO and VantageScore intensifies, with real financial consequences for borrowers hunting better rates. Home equity lending is emerging as a survival strategy for originators as cash-out refinancing remains dead despite $11.6 trillion in rate-locked equity. With roughly half of mortgages carrying sub-4% rates, the refi incentive has evaporated, leaving HELOCs and home equity lines as the only path to tap equity. Buyers are absorbing higher rates by shifting to adjustable-rate mortgages and pushing sellers for concessions rather than price cuts—evidence of the market's desperation to transact in an affordability crisis. Zillow is packaging down payment assistance aggressively through its lending operation, leveraging its real estate platform to capture purchase loans and deepen customer relationships. New home sales fell 0.6% in September as the median price dropped 3.9% year-over-year, yet inventory remains tight and affordability gaps persist despite modest price relief. Mortgage rates are holding near 7.3% following the Fed's pause, but near-term direction hinges entirely on whether tech sector weakness deepens or stabilizes. A sustained sell-off in growth stocks could push Treasury yields lower and provide temporary relief to originators facing margin compression. Conversely, if market sentiment stabilizes and inflation concerns resurface, the 10-year yield could break back above 5.0%—devastating news for purchase pipelines. Loan officers must prepare clients for volatility and lock in rates aggressively when the opportunity presents itself. The next 30 days will determine whether the tech-driven bond rally is act one of a broader correction or a brief intermission before yields resume climbing. **Locking vs Floating** Tech jitters remain the primary driver of near-term rate direction rather than economic data or Fed policy. Bond markets are responding to fears of artificial intelligence investment losses compressing future corporate earnings, creating temporary safe-haven demand. Lenders should treat this rally opportunistically—it could reverse quickly if tech stocks stabilize or if inflation data reignites hawkish Fed expectations. Lock decisions should account for the possibility that this is a tactical bounce, not the start of a sustained trend lower. **Today's Events** Q3 GDP (release completed): 3.4% vs 3.2% forecast October 24 Jobless Claims (release completed): 194K vs 199K forecast September Core PCE m/m (release completed): 0.3% vs 0.3% forecast September Core PCE y/y (release completed): 3.1% vs 3.1% forecast 7-Year Note Auction (release completed): 5.085% **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change |

Market Data
LATEST ARTICLES

RECENT ARTICLES

Article Archive

What’s up in Mortgage Today – 2.21.23

February 21st, 2023|0 Comments

Monday - February 20, 2023 - Presidents Day from “Discipline Equals Freedom” by Jocko Willink This isn’t punch the clock and go home for the day. You don’t get weekends off. NO. Here there’s no [...]

Learn to Write Sales Copy 7

February 21st, 2023|0 Comments

In writing copy for an advertisement, often you get your reader in an emotional frame of mind as a result of the environment you have created, and logic becomes less important. If you can [...]

Jocko Monday 5

February 20th, 2023|0 Comments

Your Life is Every Day. This isn't a part-time gig. This isn't punch the clock and go home for the day. You don't get weekends off. NO. [...]

What’s up in Mortgage Today – 2.17.23

February 17th, 2023|0 Comments

Friday - February 17, 2023 Aaaand to finish the week off right, MBS down 16 on the open - again Slightly weaker out of the gate in Asia with additional weakness in Europe, [...]

What’s up in Mortgage Today – 2.16.23

February 16th, 2023|0 Comments

Thursday - February 16, 2023 Another tough open for bonds. Down almost a quarter early. Treasuries up 4 bps. Bonds were sideways in quiet trading overnight. The big jump in producer prices and [...]

Learn to Write Sales Copy 6

February 16th, 2023|0 Comments

The Copy Writing Emotion Principles: Emotion Principle 1: Every word has an emotion associated with it and tells a story. Emotion Principle 2: Every good ad is an emotional outpouring of words, feelings and [...]

Subscribe

Send me some brain food

Go to Top