Loading...
HOME2023-01-22T13:43:33-07:00

Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (AM) - 09/17/26 {{catlist}}
September 17, 2026
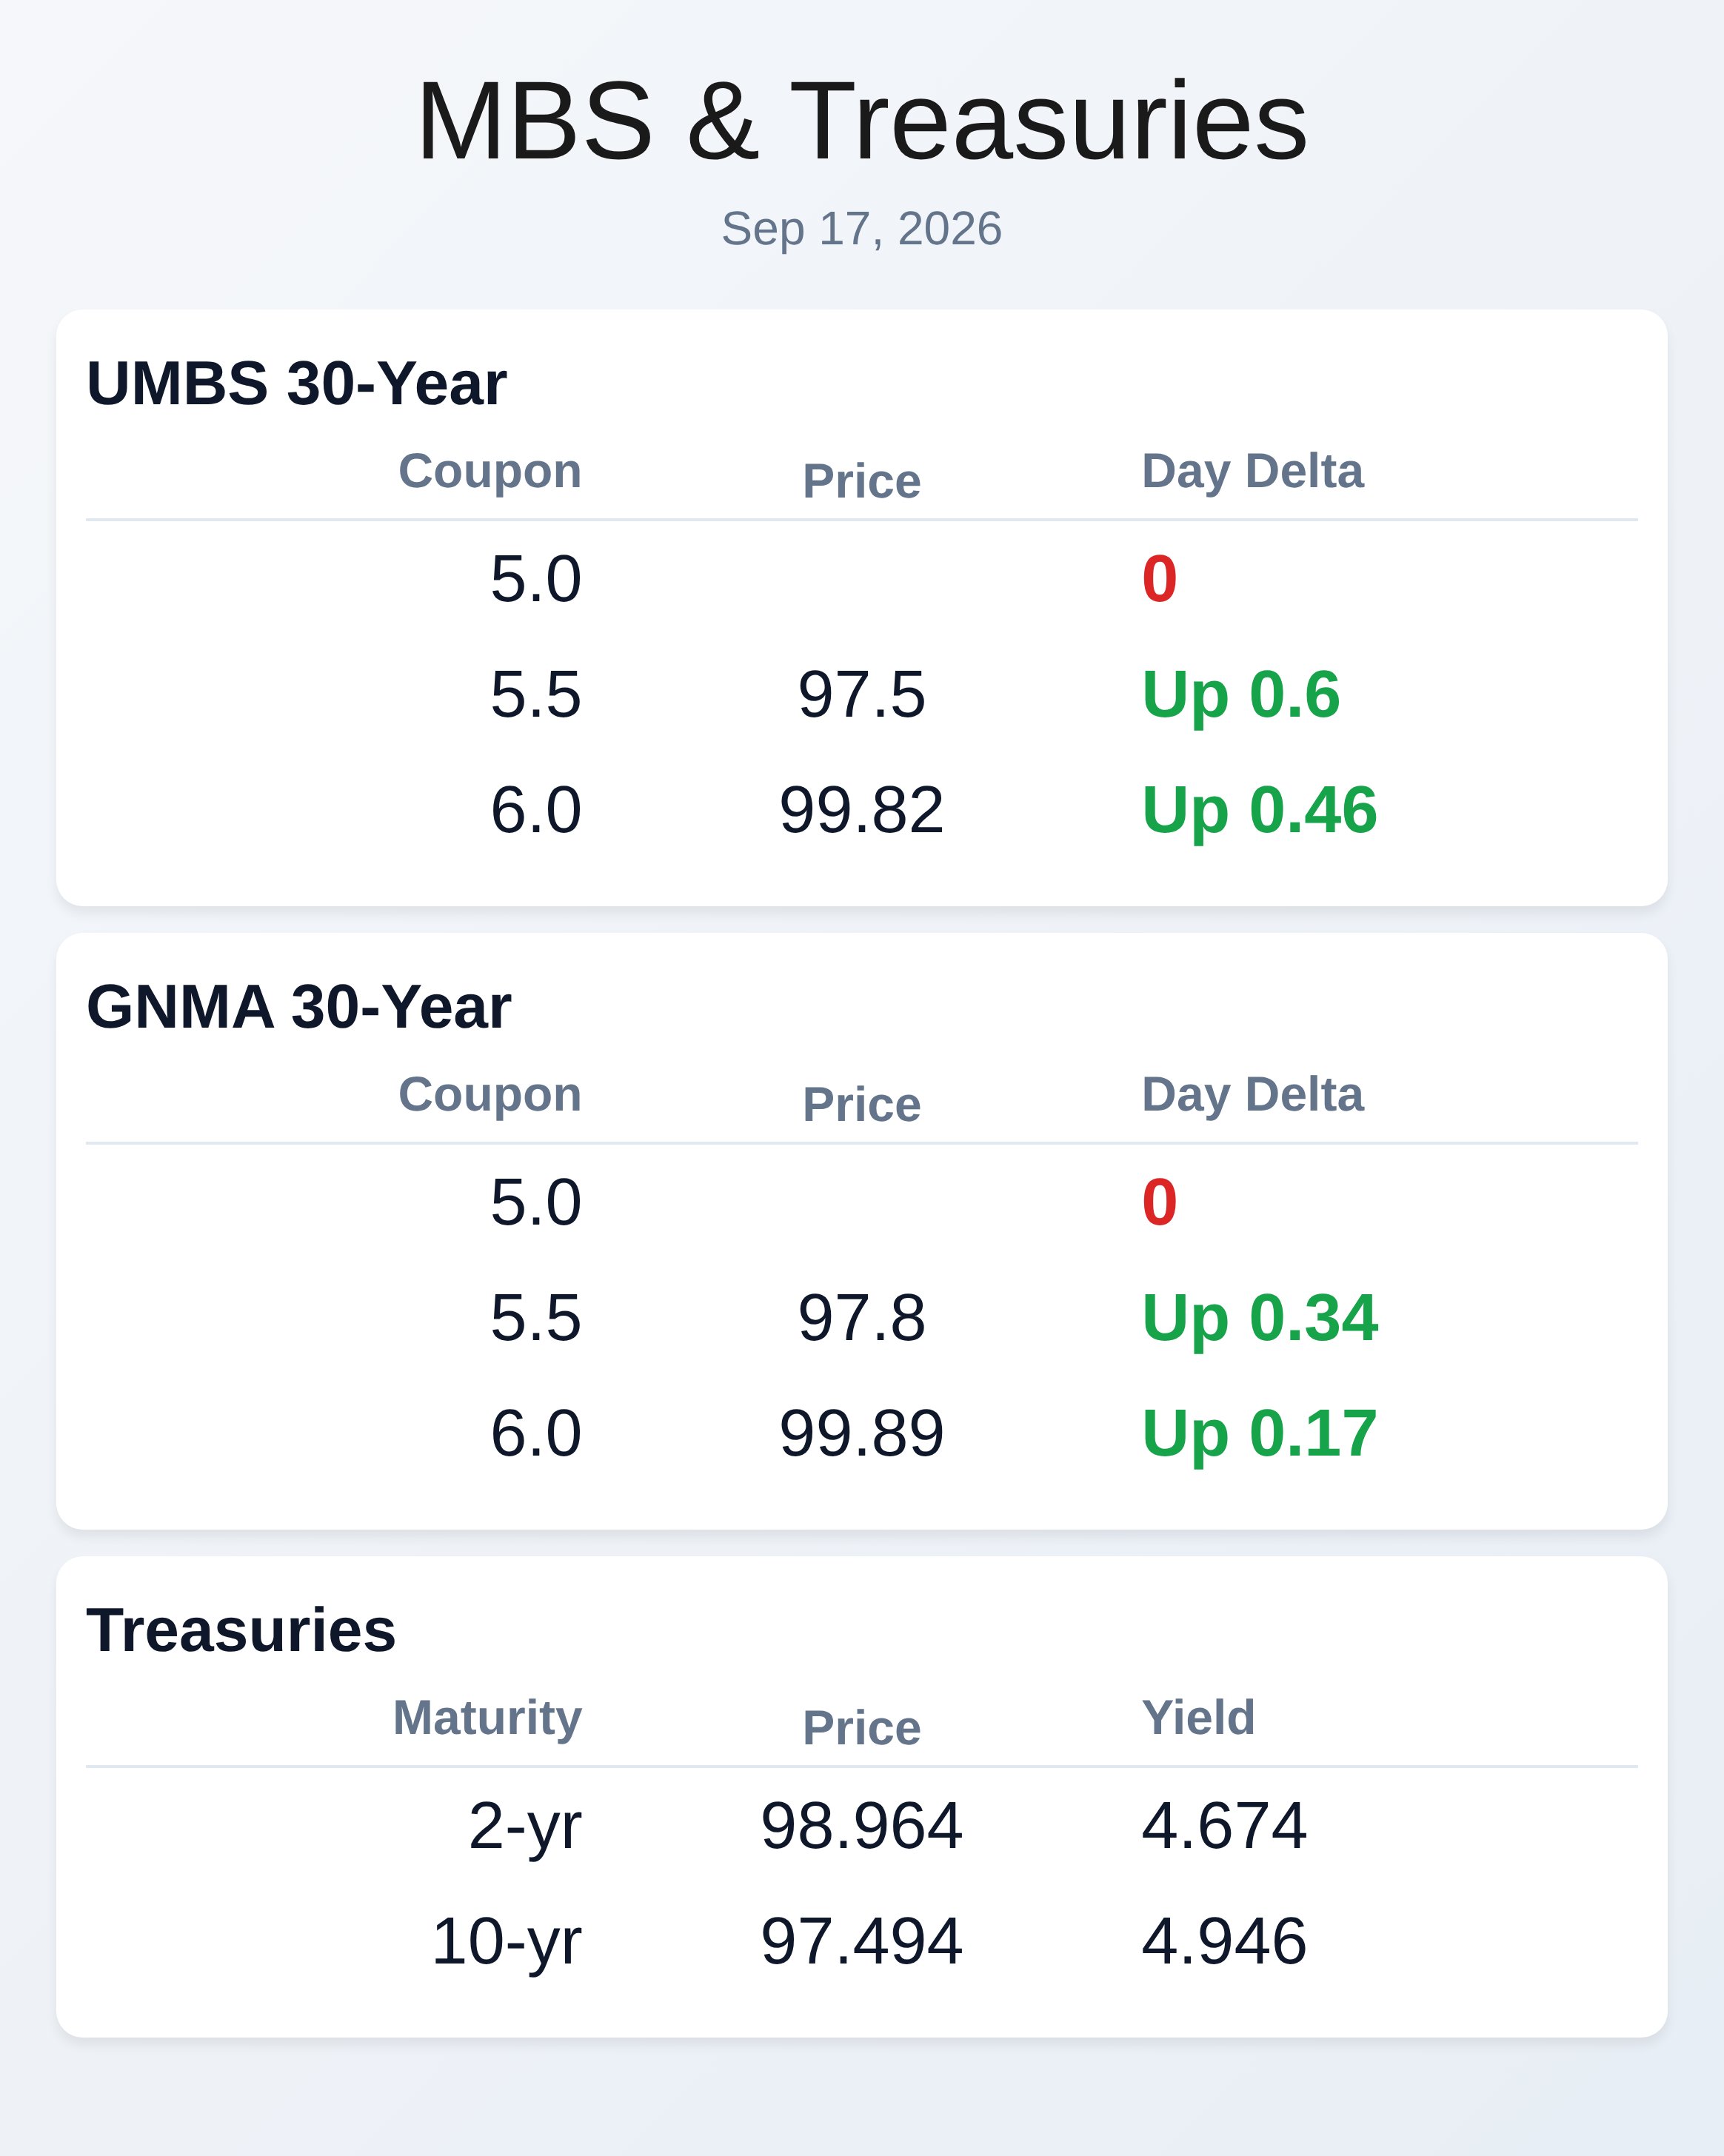
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/17/2026** The Federal Reserve's quarter-point rate hike to 4.00 percent sent mixed signals through bond markets yesterday, with Treasury yields rallying back this morning even as policymakers signaled more tightening ahead. Agency MBS prices rebounded modestly overnight, with UMBS 6.0s holding at 99.82, suggesting some stabilization after the initial volatility. The hawkish tone from Fed policymakers—16 of 18 officials now see at least one more hike in 2026—continues to create uncertainty for lenders trying to lock or float rate locks. Jobless claims came in stronger than expected at 196,000 versus forecasts of 207,000, adding to the mixed economic picture. The 10-year Treasury yield opened this morning at 4.97 percent, down nearly 5 basis points from yesterday's close at 5.01 percent. The week's economic data painted a picture of an economy resilient on employment but fragile on housing. August housing starts fell short at 1.275 million versus expectations of 1.31 million, marking continued weakness in new construction. Building permits also disappointed at 1.394 million, though continuing claims declined to 1.730 million from 1.774 million the prior week. The Philly Fed Business Index dropped to 37.8 from 47.4, signaling a noticeable pullback in regional manufacturing sentiment. These crosscurrents leave originators navigating an environment where robust labor markets contrast sharply with deteriorating housing demand. GNMA 30-year securities showed less volatility than UMBS in overnight trading, with the 6.0 coupon priced at 99.89 after gaining just 17 basis points intraday. The 6.5 coupon held at 102.03, suggesting investors are rotating into higher coupons as rate expectations stabilize. GNMA's more stable performance reflects the government guarantee and continued demand from portfolio managers seeking yield in a higher-for-longer rate environment. Treasury curve positioning shows the 2-year yielding 4.67 percent and the 30-year at 5.30 percent, indicating markets are pricing in eventual rate cuts but not expecting them anytime soon. The spread dynamics between shorter and longer maturities remain the key lens for tracking duration bets across fixed-income desks. Originators face a critical decision point as secondary desks have already repriced locks following the Fed's move. Some lenders held back repricing yesterday afternoon, likely setting themselves up for adjustments this morning, which increases float risk for brokers still holding paper. The consensus among trading desks is cautious: higher Fed funds rates should ultimately help mortgage rates by fighting inflation, but the near-term noise from Fed decisions makes it impossible to confirm that benefit immediately. Floating on lenders who haven't repriced introduces execution risk, while those who repriced for the worse still leave room for tactical positioning before a clear trend emerges. The defensive strategy of waiting for momentum confirmation remains the prudent choice given the elevated uncertainty in rate direction. Mortgage application data from the Mortgage Bankers Association revealed that builder applications for new home purchases fell 5.5 percent year-over-year and declined 6 percent month-over-month in August. This marks the fifth consecutive month of declining applications and represents 2026's lowest monthly total for new construction purchases. Retail sales proved stronger than anticipated at 1.2 percent month-over-month, with core sales up 1.4 percent, showing consumers remain willing to spend even at elevated borrowing costs. The tension between consumer spending power and housing affordability continues to define market dynamics as mortgage rates remain elevated despite yesterday's Treasury rally. The Fed's updated projections now show a median year-end fed funds rate of 4.125 percent, implying one to two additional rate moves before year-end depending on inflation data. Treasury yields have stabilized this morning after moving lower on expectations that the aggressive tightening cycle may finally be plateauing, though any signs of sticky inflation could trigger another leg higher. Oil prices fell 2.5 percent overnight to $99.90 per barrel, easing some of the near-term inflation concerns that had pushed yields to multi-decade highs. The combination of cooling commodity prices, resilient labor markets, and weaker housing activity creates a complex backdrop where mortgage originators must balance rate lock strategy with pipeline management. Markets will closely watch the October and December Fed meetings and any revisions to the neutral rate before committing to a clear directional view on 2027 rates. **Locking vs Floating** Yesterday's Fed hike created an extremely difficult environment for lock-versus-float decisions. Several lenders did not reprice yesterday afternoon, meaning brokers holding loans with those lenders face repricing risk this morning when the lender adjusts. Floating strategy works best when lenders who repriced for worse leave room for positive adjustments, but even then the prudent approach is to wait for clear momentum before abandoning defensive positioning. Treasury support has returned near yesterday's levels, confirming some stability, but the bigger picture question remains unanswered: will higher Fed funds rates ultimately help or hurt mortgage rates? The safest path is to hold defensive floats while monitoring for a strong directional shift rather than trying to catch tops or bottoms during Fed weeks. **Today's Events** Building Permits (Aug): 1.394M vs 1.41M forecast, 1.433M prior Continued Claims (Sep/05): 1.730M vs 1.780K forecast, 1.774K prior Housing Starts (Aug): 1.275M vs 1.31M forecast, 1.239M prior Jobless Claims (Sep/12): 196K vs 208K forecast, 206K prior Philly Fed Business Index (Sep): 37.8 vs 30.5 forecast, 47.4 prior Philly Fed Prices Paid (Sep): 48.60 vs no forecast, 40.90 prior **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.5 | 97.5 | 0.6 | | 6.0 | 99.82 | 0.46 | | 5.5 | 97.8 | 0.34 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2 yr | 4.674 | 98.964 | -0.06 | | 3 yr | 4.745 | 98.976 | -0.08 | | 5 yr | 4.791 | 98.17 | -0.089 | | 7 yr | 4.863 | 97.869 | -0.088 | | 10 yr | 4.946 | 97.494 | -0.073 | | 30 yr | 5.304 | 97.323 | -0.059 | Market Data
Mortgage Today (PM) - 09/16/26 {{catlist}}
September 17, 2026
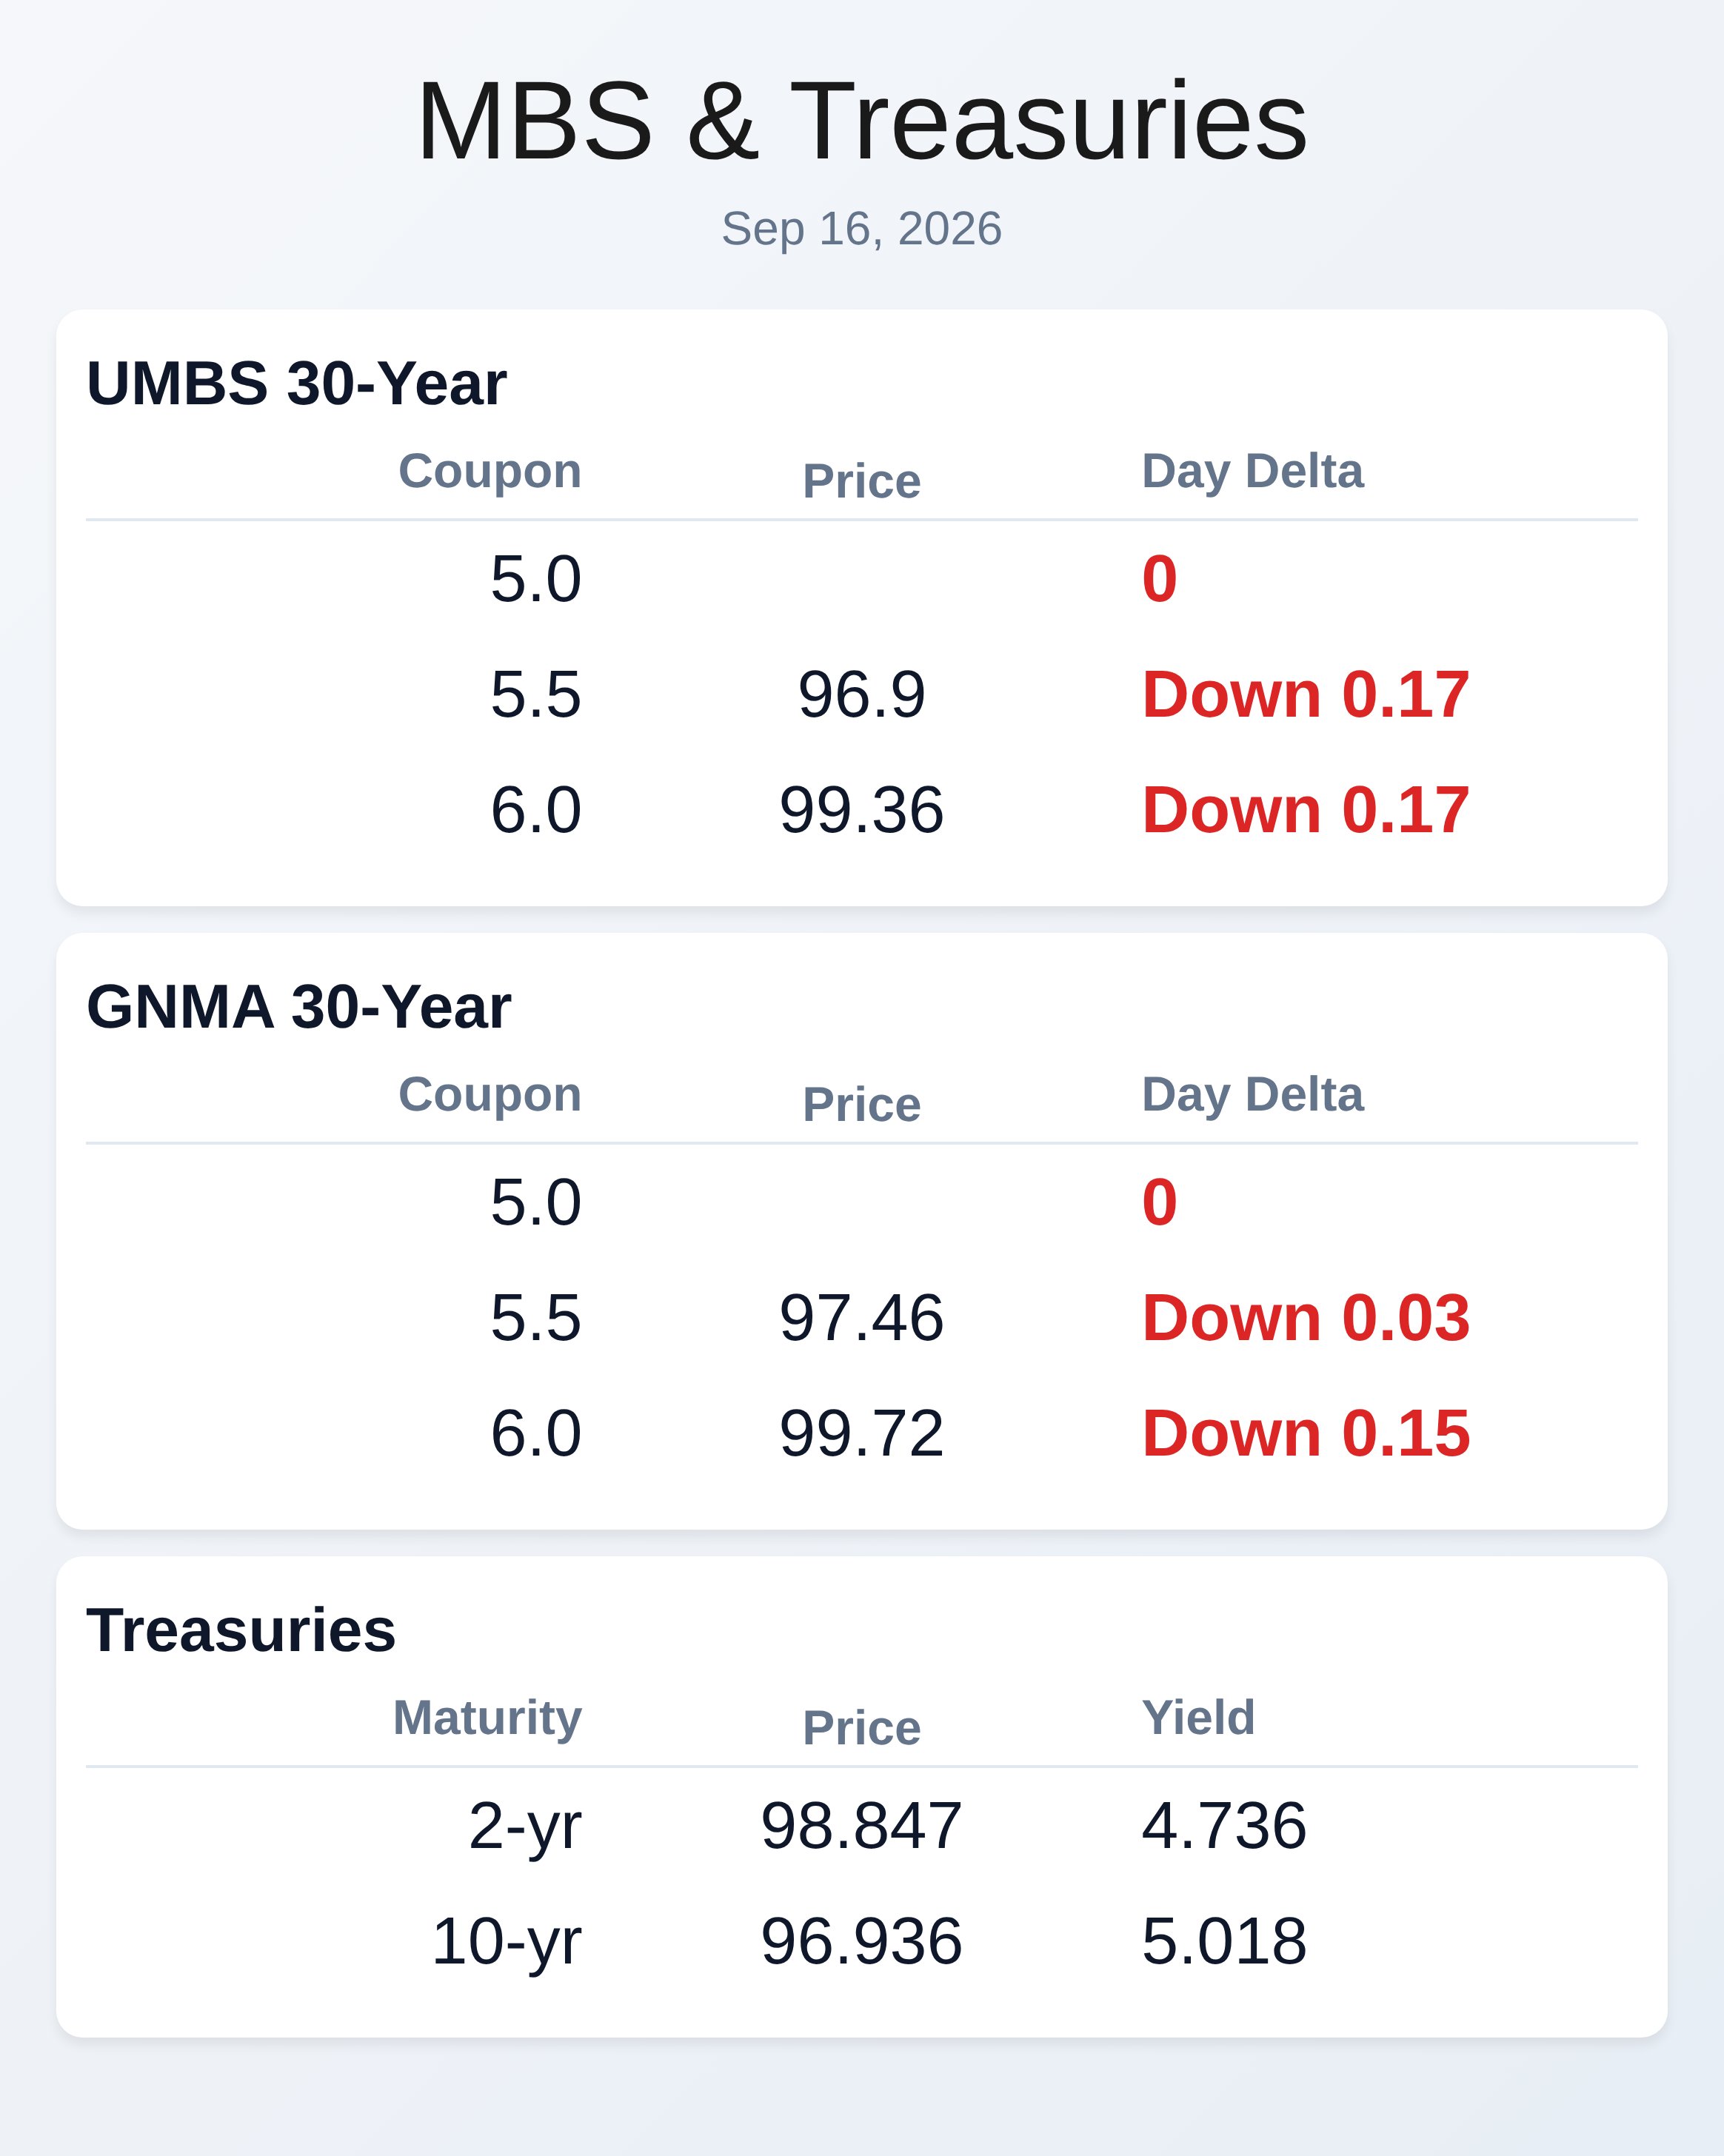
READ MORE I'll proceed with writing the blog post based on the email content provided, as the article fetches are encountering technical issues. **WTMS Blog Today = What's up in Mortgage Today (PM) - 09/16/2026** The Federal Reserve hiked rates by 25 basis points to a 3.75-4% target range today, the first increase since 2023, sending mortgage markets into a day of whipsaws and uncertainty. Fed officials signaled at least one more hike could come before year-end, with some policymakers expecting two additional increases to combat persistent inflation. The 10-year Treasury cracked 5% early this week and settled around 5% by day's end, creating modest headwinds for MBS prices that finished down roughly an eighth of a point despite initial intraday strength. Bank of America strategists project the 10-year could eventually settle around 4.5%, which would put conventional mortgage rates somewhere in the 6.5%-7% range—painfully high for borrowers who already face the tightest lending standards in decades. Purchase demand has collapsed, with application volume down 19% year over year as rates surged from 6.97% to 7.22% in just six days. Negative reprice risk spiked Wednesday afternoon as MBS fell an eighth of a point from many lenders' morning rate sheet prints, forcing originators to make critical lock-or-float decisions for pending loans. The volatility around Fed Chair Kevin Warsh's post-announcement remarks moved bonds lower again, creating uncertainty about whether lenders would need to adjust rates downward overnight or hold their positions through Thursday morning. Several large lenders did not immediately reprice the afternoon, creating additional risk that they would face adjustments at tomorrow's open when wholesale pricing potentially moves their direction. MBS traders are watching the Fed's communications closely for any hints about the pace of future rate increases, as the trajectory of Treasury yields will ultimately determine whether mortgage rates stabilize or drift higher through year-end. Lenders holding unpriced pipelines face the toughest environment in months, with rate locks becoming increasingly expensive for originators as the cost to produce a mortgage climbs closer to $11,000 per loan. Pennymac raised its conforming loan limit to $850,000—$17,250 above the current $832,750 baseline—in a calculated move to capture higher-balance borrowers before the official FHFA announcement arrives. This early increase gives Pennymac's TPO partners and correspondent lenders a competitive edge in a purchase market where every qualified borrower counts, allowing them to keep higher-balance loans in conventional territory rather than pushing them into expensive jumbo programs. The broader competitive message is clear: lenders are once again racing ahead of regulatory limits to secure market share and strengthen partner relationships before the official 2027 limit is set. This strategy has become table stakes in the origination business, with larger players using higher limits as a customer-acquisition and pipeline-building tool. For smaller originators and brokers, the move signals that access to higher-balance conventional borrowers now depends on partnering with lenders willing to move fast and early. Title and deed fraud continues to accelerate in the mortgage ecosystem, with First American extending its property-monitoring service to independent title agents nationwide to help homeowners receive alerts about suspicious filings. The expansion reflects an industrywide crisis of growing sophistication in fraud schemes targeting home equity and mortgage documents. Meanwhile, a $14 million DSCR fraud scheme in Baltimore involving shell LLCs, fraudulent appraisals, and coordinated title-company participation has resulted in RICO claims and highlights the vulnerability of emerging lending channels to organized fraud. Ameritrust's lawsuit alleges roughly 90 loans defaulted immediately, many without a single payment, in what mirrors a broader Baltimore DSCR fraud wave identified last year. These cases underscore that as new loan products and investor demand grow, so does organized fraud targeting those programs, requiring stronger underwriting and documentation discipline across all channel partnerships. Fed Fund futures now price in additional rate hikes through year-end, with several strategists expecting at least one more increase in October or December despite political pressure from the Trump administration to cut. The conflict between inflation reality and administration messaging has created headwinds for Fed Chair Kevin Warsh, who faces demands to prioritize rate cuts while underlying inflation signals persist. Bank of America's rate team sees little room for mortgage rate improvement unless Treasury yields reverse course significantly, and they project mortgages settling in the 6.5%-7% range under their base-case scenarios. Originators should assume rates stay elevated through the remainder of 2026, making pipeline management, lock discipline, and cost control paramount to survive compressed margins. Borrowers closing soon should lock rather than float, given the elevated volatility and hawkish Fed trajectory now baked into market pricing. **Locking vs Floating** MBS Live strategists advise caution on floating positions given the negative reprice risk rising after this afternoon's market moves. Lenders who repriced early hold more flexibility, while those delaying adjustments face potential pressure at tomorrow's open. The consensus is defensive—lock pending loans unless the borrower has significant rate lock cushion and genuine appetite for the downside volatility risk. **Today's Events** Import prices mm (Aug): 0.7% vs 0.4% forecast, -0.4% previous Retail Sales (Aug): 1.2% vs 0.8% forecast, -0.6% previous Retail Sales Control Group MoM (Aug): 1.4% vs 0.4% forecast, -0.4% previous Headline CPI y/y (Aug): 3.4% vs 3.4% forecast, 3.4% previous **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2 yr | 4.736 | 98.847 | 0.065 | | 3 yr | 4.825 | 98.756 | 0.057 | | 5 yr | 4.88 | 97.785 | 0.044 | | 7 yr | 4.951 | 97.359 | 0.035 | | 10 yr | 5.018 | 96.936 | 0.013 | | 30 yr | 5.363 | 96.469 | -0.005 | Market Data
Mortgage Today (AM) - 09/16/26 {{catlist}}
September 16, 2026
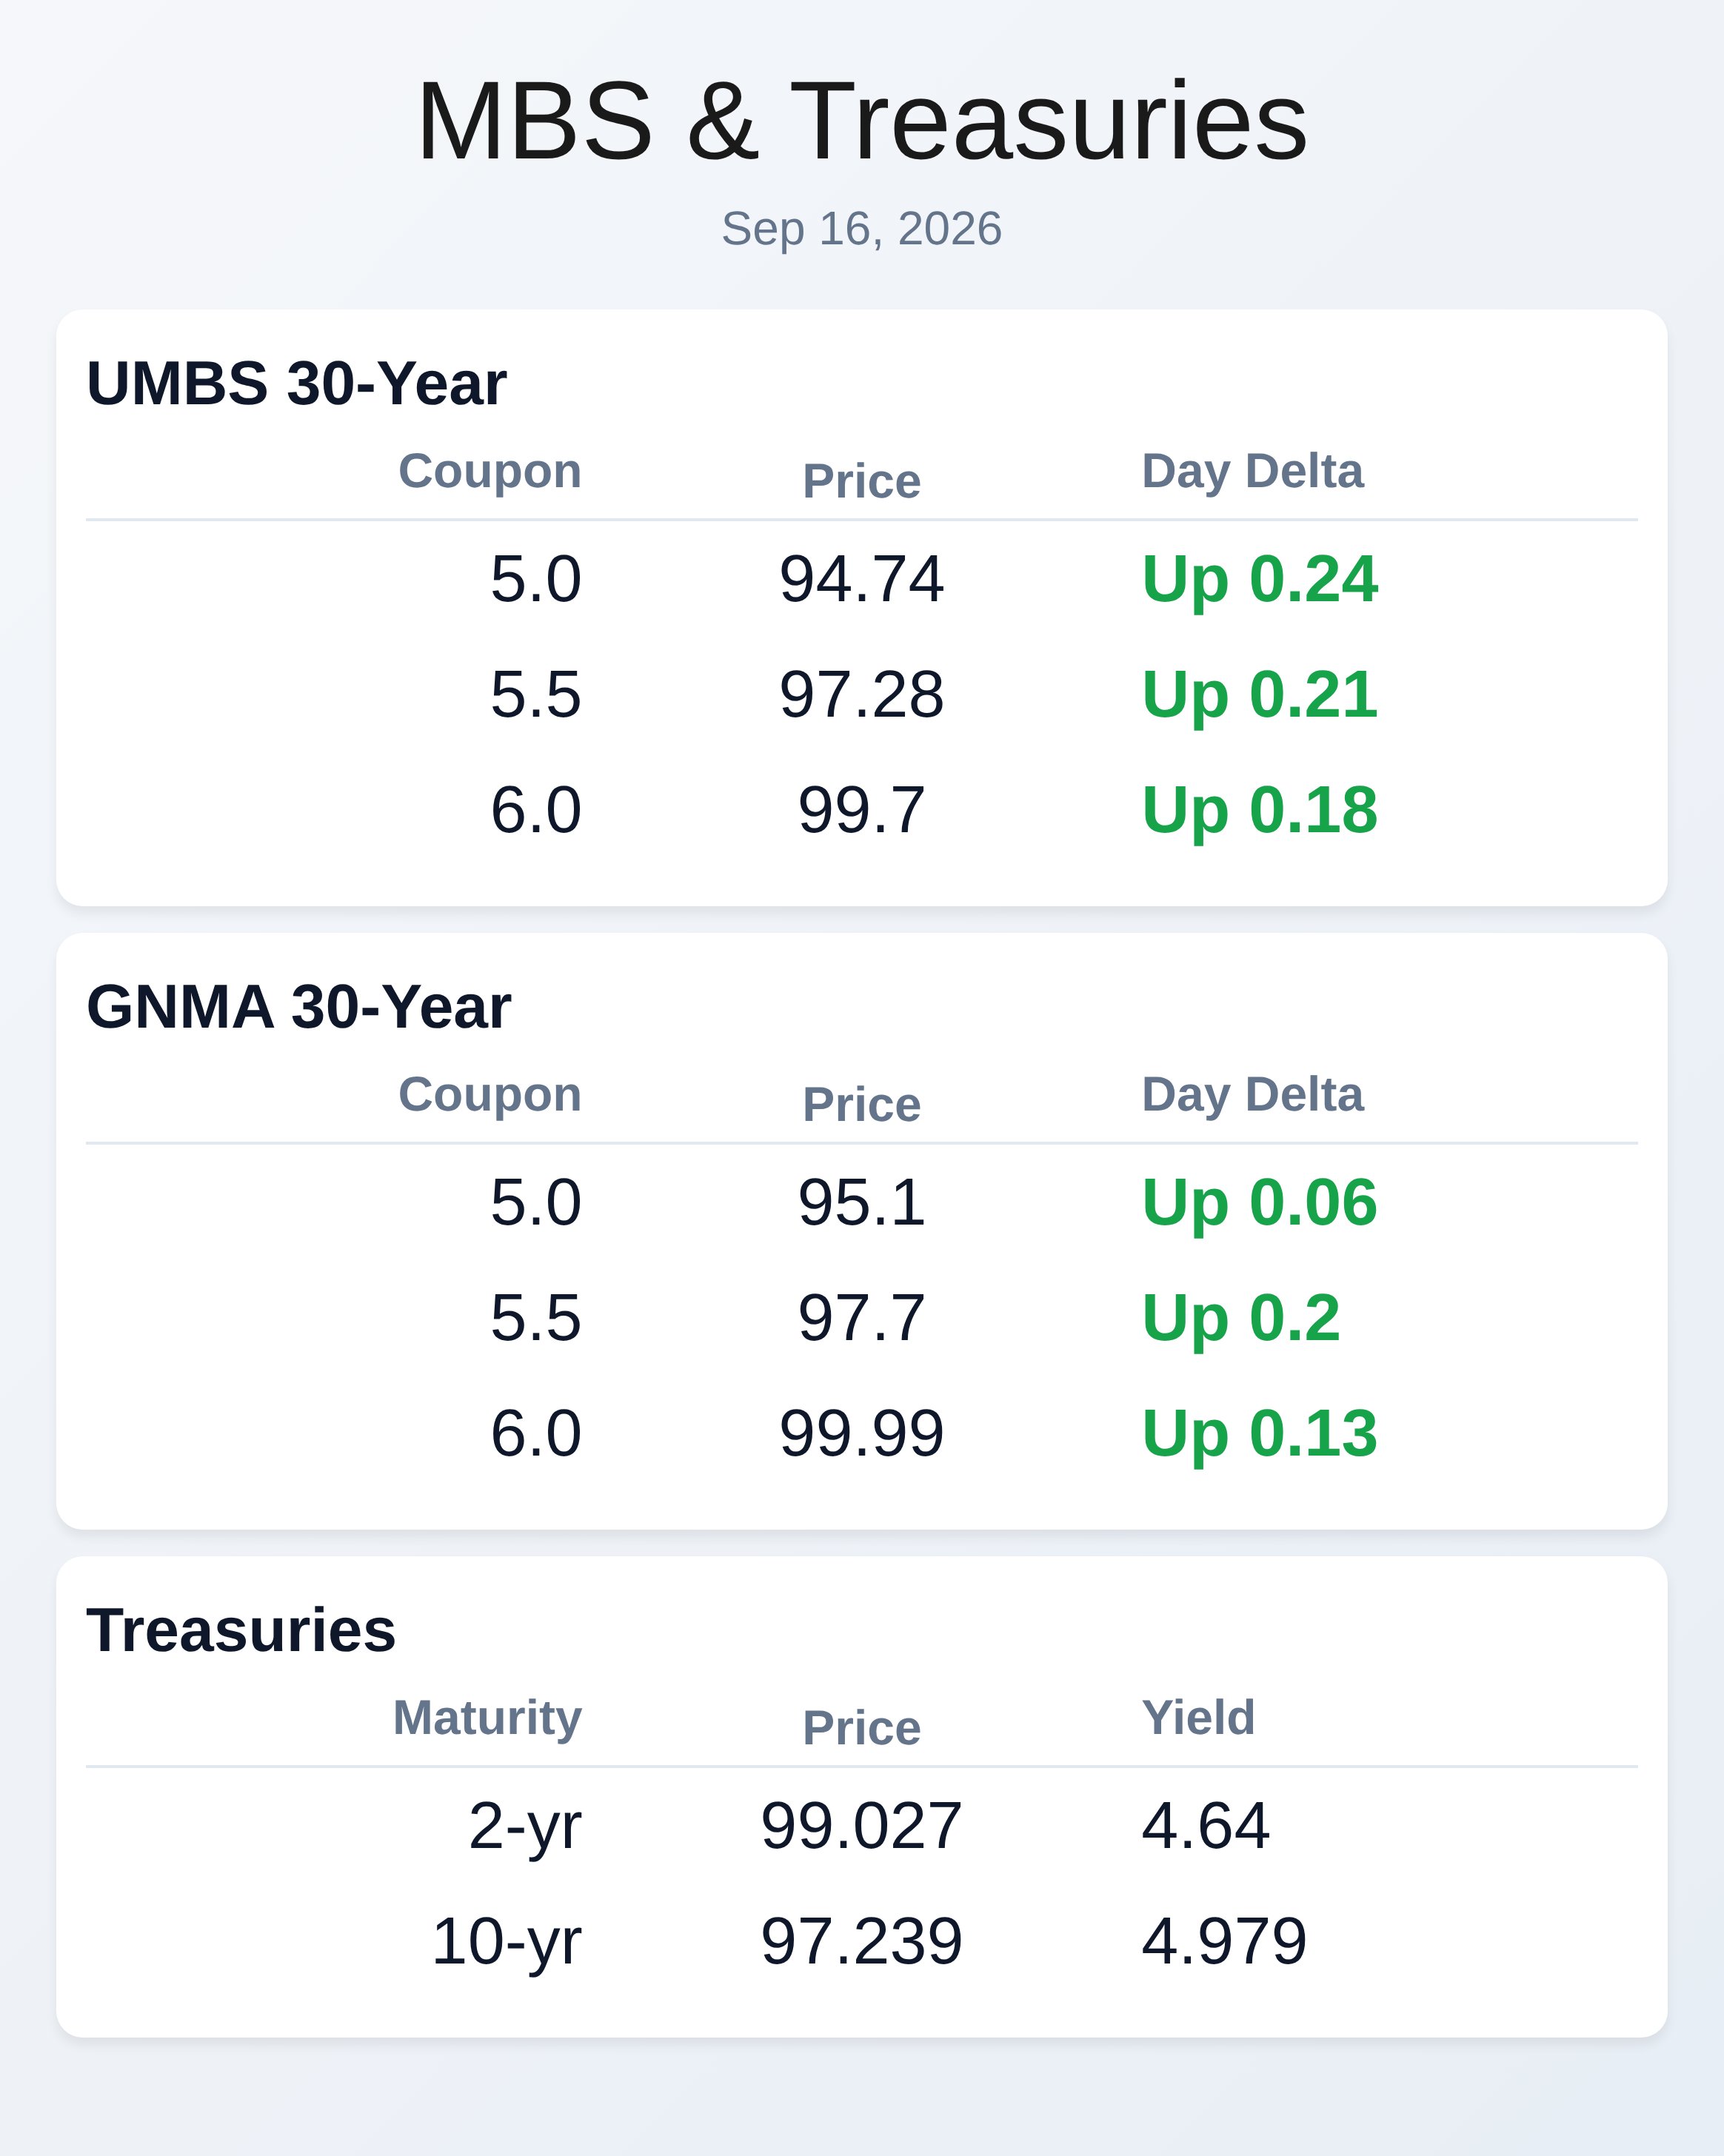
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/16/2026** The Federal Reserve faces the market's spotlight this afternoon as traders price in a 90%+ probability of the first rate hike since 2023, a move widely expected to lift borrowing costs across mortgages and refinance activity. MBA applications fell 4.1% last week as rising energy prices and Treasury yields pushed the 10-year yield toward 5%, while refinance activity plummeted 9% week-over-week and remains down 65% year-over-year. August retail sales beat expectations at 1.2% versus a 0.8% forecast, demonstrating consumer resilience despite inflation concerns that sparked this rate-hike cycle. Import prices also surprised upward at 0.7% monthly, reinforcing inflation pressures that justify the Fed's tightening stance. The tone of Fed Chair Kevin Warsh's press conference will matter more than the rate decision itself, as any hawkish messaging could trigger another leg higher in yields. Agency MBS and Treasury prices found slight relief early Wednesday as crude oil dipped below $108 per barrel and traders prepared for the central bank's announcement. UMBS 30-year coupons improved modestly, with the 6.0 coupon closing at 99.70 (up 0.18), while the 10-year Treasury yield moved to 4.97% from 4.98% overnight. Foreign demand for longer-duration Treasuries remains soft, evidenced by the weak 20-year Treasury reopening that required a 5.42% yield to clear, nearly 60 basis points higher than the prior auction. The dollar pared losses and equities positioned for a morning rally, though sentiment remains fragile. Warsh's communications strategy—whether he signals further tightening beyond today or commits to a data-dependent path—will determine bond market direction heading into year-end. Purchase mortgage applications declined 1% seasonally adjusted and sit 19% below last year's levels, underscoring persistent headwinds from higher rates and compressed affordability that shows no sign of easing. Refinance volume dropped even more sharply, signaling that borrowers with existing mortgages have largely locked in rates and view opportunities for refi as limited. Applications data released this morning revealed the human cost of Fed policy: stretched borrowers with thinner margins for error in their loan files. Each rate move ripples through origination pipelines as would-be homebuyers delay purchase decisions. Disaster declarations from FEMA (Indiana tornadoes and Hawaii earthquakes) add additional operational complexity for lenders and servicers in affected regions. The economic calendar this afternoon piles on the Fed's evidence: July Business Inventories, September NAHB Housing Market Index, and crude oil inventory levels all arrive before the 2 p.m. rate decision. These data points collectively paint a picture of an economy still firing on cylinders—strong consumption, robust job markets, and pricing power in the supply chain. Treasury yields have already climbed to multiyear highs on inflation concerns, leaving the bond market little room to rally if Warsh disappoints hawks. The combination of above-target inflation, surging energy costs, healthy employment, and solid GDP growth leaves policymakers with minimal political cover to hold steady. Mortgage originators now face the reality that rate lock periods could face pressure if Fed communication signals further tightening down the road. Private equity continues reshaping industry peripherals beyond just mortgage lending and servicers. Genstar Capital and Aksia announced a strategic growth investment in Richey May, a top 50 U.S. accounting and advisory firm, signaling continued M&A appetite among financial sponsors. The capital will fund Richey May's organic growth and acquisition strategy as it builds a national platform, though founder ownership remains materially intact. Tech transitions dominate vendor conversations as credit unions and lenders evaluate platform upgrades ahead of the November 2 Uniform Appraisal Dataset (UAD) 3.6 deadline. Floify emphasized the need for vendors to shoulder implementation heavy lifting and maintain post-go-live support, a lesson learned from prior mortgage system conversions. Jumbo lending tools like Symmetry's piggyback HELOC structure gain traction as borrowers navigate affordability challenges with bridge alternatives. Subscribe free at **WellThatMakesSense.com** for daily mortgage market updates and origination insights. **Locking vs Floating** Markets face elevated uncertainty heading into the Fed announcement, with oil prices and inflation data creating volatility in both directions. Technical support emerged in bond markets today, yet momentum remains contested and could shift dramatically on Warsh's guidance. Originators should prepare for continued rate volatility through the weekend as traders digest the policy decision and guidance on future tightening. Any signal of additional hikes beyond today will pressure purchase and refi demand further. Lock recommendations depend on pipeline composition, but defensive positioning seems warranted until a clearer reversal in bond yields takes hold. **Today's Events** Import prices (August): 0.7% vs. 0.4% forecast, -0.4% prior Retail sales (August): 1.2% vs. 0.8% forecast, -0.6% prior Retail sales control group (August): 1.4% vs. 0.4% forecast, -0.4% prior Headline CPI (August): 3.4% vs. 3.4% forecast, 3.4% prior MBA mortgage applications: Down 4.1% week-over-week; refinance down 9% w/w, -65% year-over-year; purchase applications down 1% seasonally adjusted, -19% year-over-year July business inventories (afternoon) September NAHB Housing Market Index (afternoon) Weekly crude oil inventories (afternoon) September FOMC decision and press conference (2 p.m. EDT) **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2yr | 4.64 | 99.027 | -0.023 | | 3yr | 4.736 | 99.001 | -0.028 | | 5yr | 4.804 | 98.114 | -0.024 | | 7yr | 4.889 | 97.72 | -0.020 | | 10yr | 4.979 | 97.239 | -0.023 | | 30yr | 5.351 | 96.641 | -0.017 | Market Data
LATEST ARTICLES

RECENT ARTICLES

Mortgage Today (AM) – 02/04/26

February 4th, 2026|Week In Review|

WTMS Blog Today = What's up in Mortgage Today (AM) - 02/04/2026 Government shutdown drama finally ends as the House reached a deal to reopen federal operations, heading to Trump's desk for signature today. The [...]

Mortgage Today (PM) – 02/03/26

February 3rd, 2026|Week In Review|

WTMS Blog Today = What's up in Mortgage Today (PM) - 02/03/2026 President Trump's housing policy stance is creating mixed signals in mortgage markets today. He declared his administration will prioritize keeping home prices high [...]

Article Archive
Getting Things Done Explained – Part 7

May 21st, 2024|0 Comments

. My reading notes for Getting Things Done, The Art of Stress Free Productivity, David Allen and James Fallows - Part 7.. The right time and place for the review. Do whatever you [...]

Getting Things Done Explained – Part 6

May 16th, 2024|0 Comments

???? My reading notes for getting things done - Part 6.. A calendar reminder can serve that purpose. Some typical decision areas in this category include Hire fire, merge acquire sell, divest, change [...]

Getting Things Done Explained – Part 5

May 14th, 2024|0 Comments

???? My reading notes for getting things done - Part 5. The Projects List is not meant to hold plans or details about your projects themselves, nor should you try to keep it [...]
Subscribe

Send me some brain food

Go to Top