Loading...
HOME2023-01-22T13:43:33-07:00

“Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

{{title}} {{catlist}}
{{date}}
READ MORE {{content}}
Mortgage Today (PM) - 10/28/26 {{catlist}}
October 28, 2026
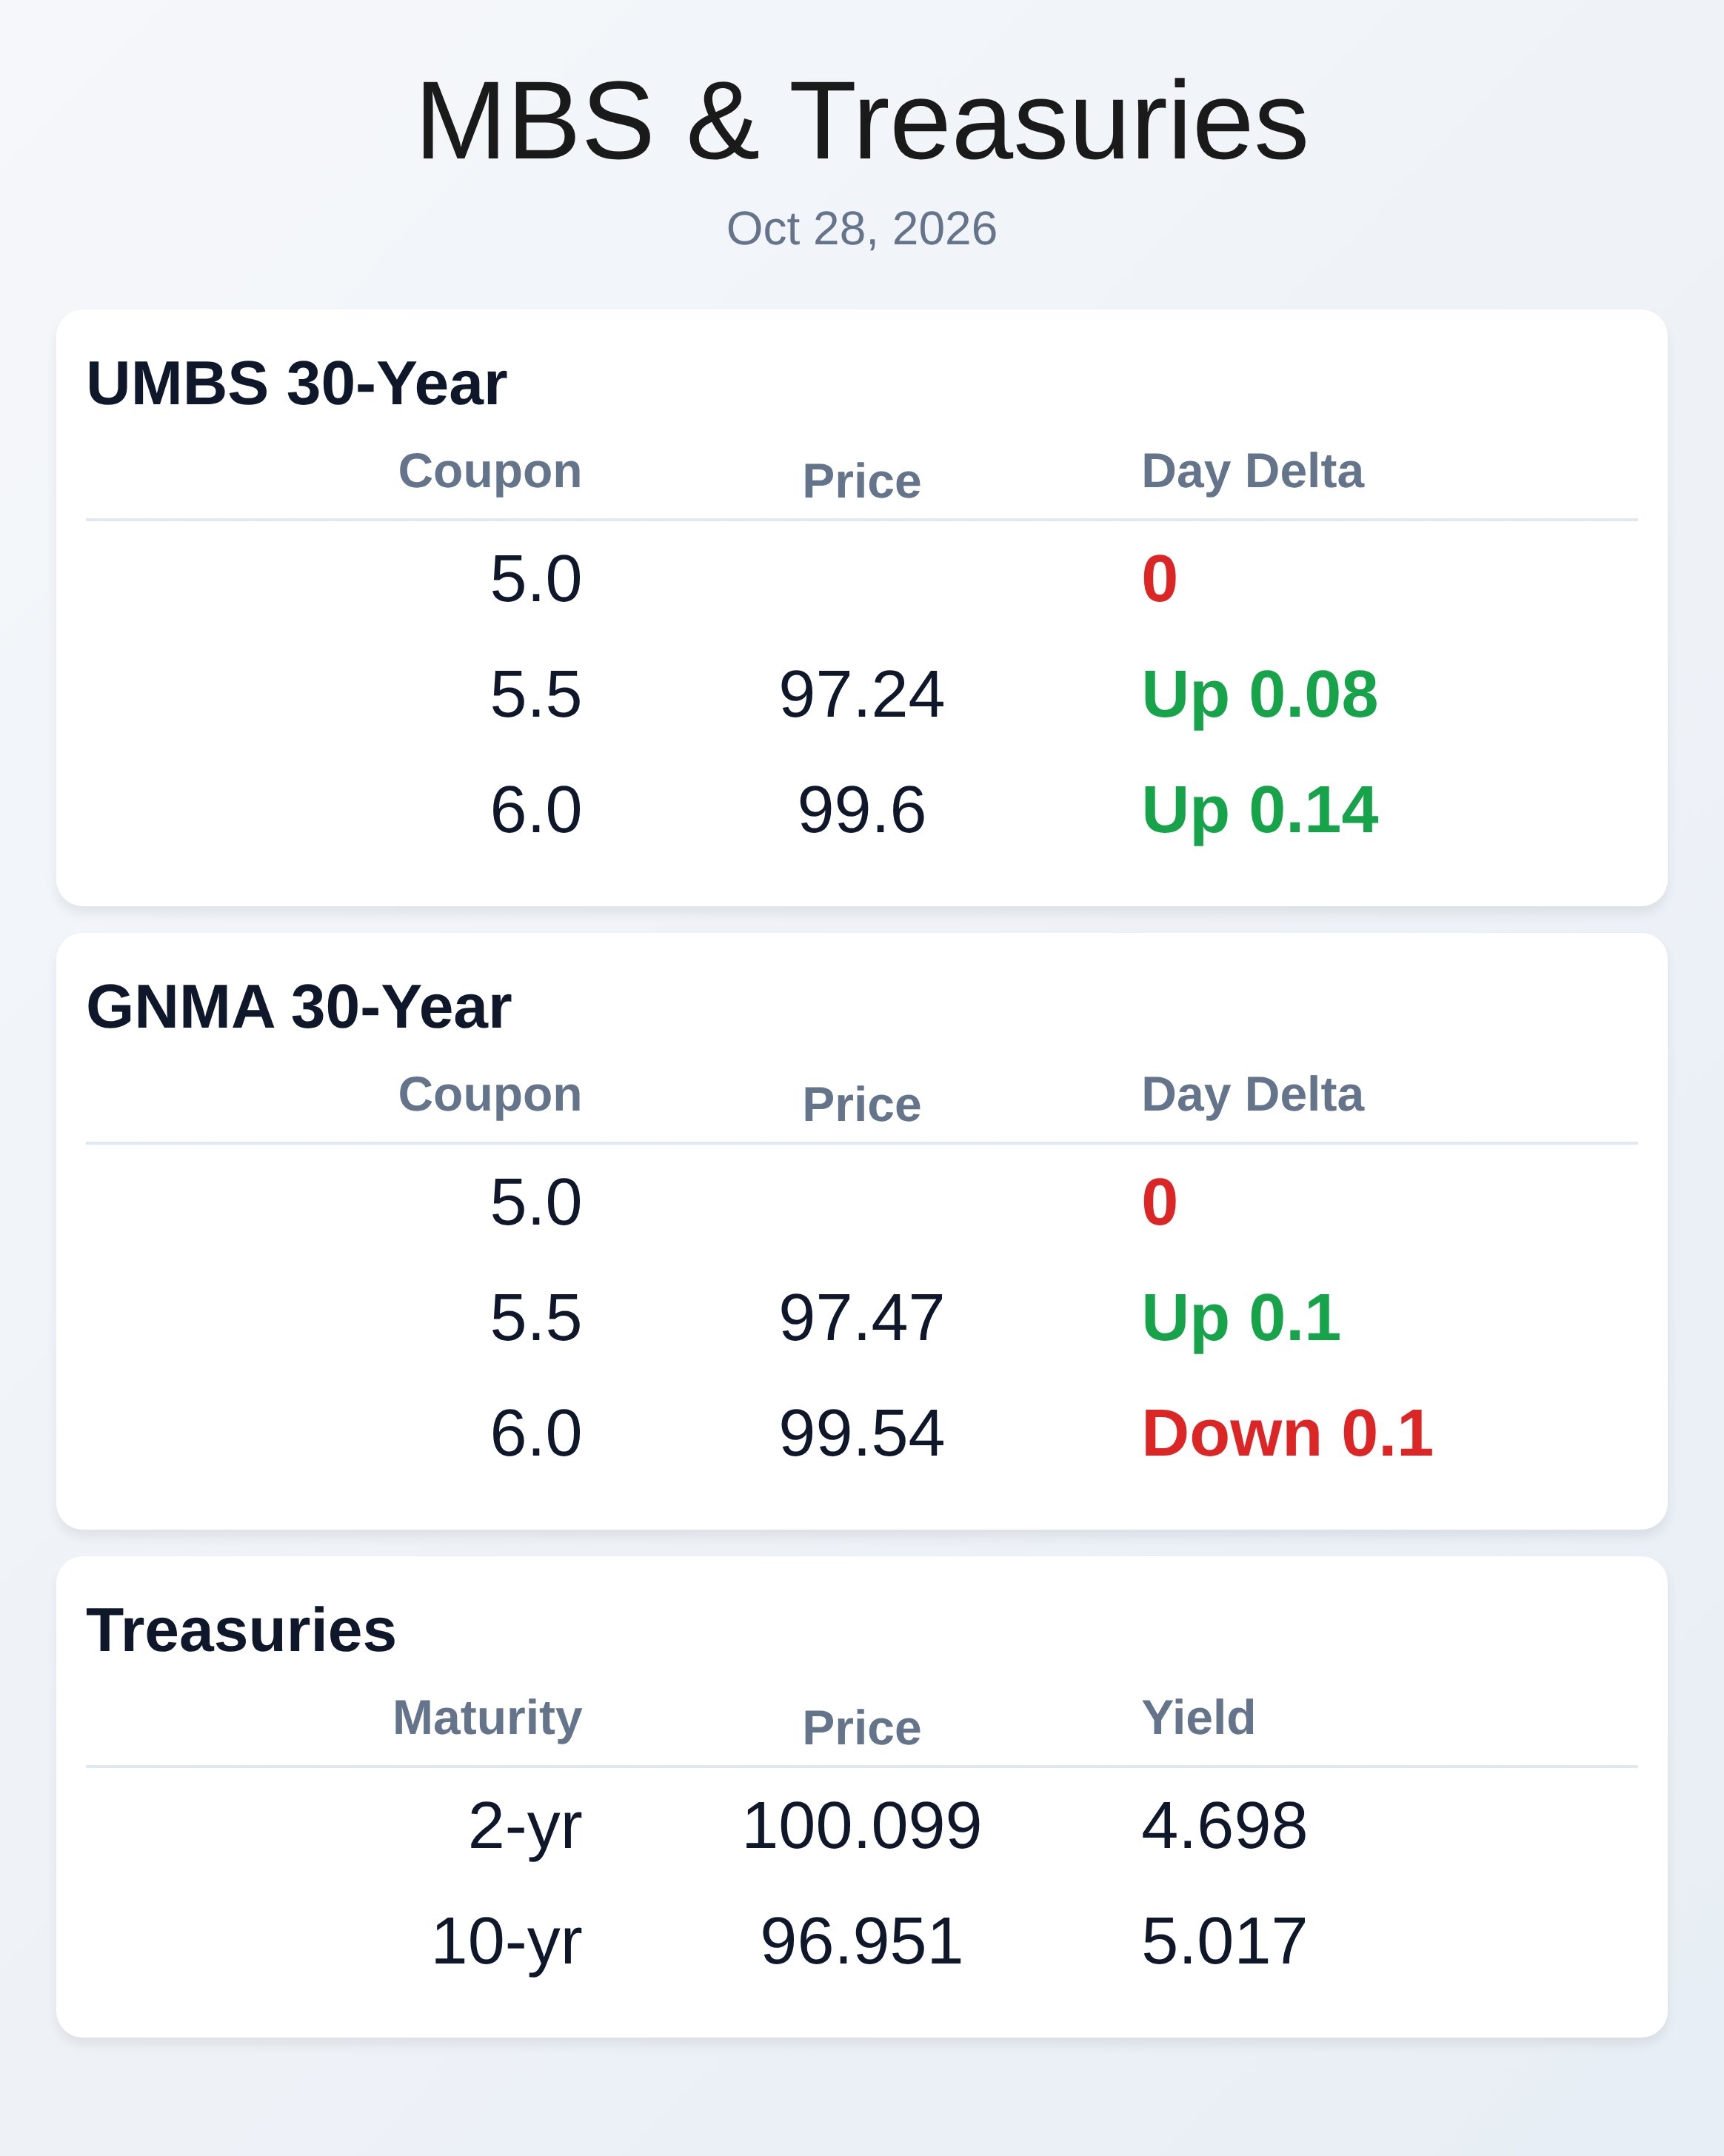
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 10/12/2026** The mortgage market is holding steady at a crossroads as bond traders wrestle with competing forces: persistent inflation worries, geopolitical tensions pushing oil higher, and growing anxiety about AI-driven debt bubbles. UMBS 6.0 closed Friday at 98.27, while the 10-year Treasury yield sits at 5.243%, after a week of volatile swings between optimism about tech weakness and concern about stubborn price pressures. MBA's economic team downgraded 2027 origination forecasts to just under $2 trillion, down 5% from 2026, signaling origination volume headwinds will persist through year-end and into spring. Sellers now outnumber buyers by 63%—a record gap since 2013—giving real estate agents unprecedented leverage in negotiations even as that market remains starved for qualified borrowers. Mortgage applications fell 4.2% week-over-week last week, and the primary-secondary spread widened to 92 basis points as lenders brace for tighter margins and more selective customer acquisition. The week ahead will test whether mid-October's bond rally holds ground or fades into another round of selling. The Consumer Confidence Index and economic data releases later this week could accelerate a rebound in Treasury yields if they signal the labor market remains too strong for the Fed to pause indefinitely. Wall Street had priced in nearly zero probability of an October rate hike going into this week, but recent inflation prints have traders reconsidering whether the Fed truly has the luxury of sitting pat through year-end. For mortgage originators, the backdrop remains challenging: purchase originations are forecast to gain just 0.8% next year to $1.42 trillion, while refinance volume craters 17% to $571 billion as existing homeowners with sub-5% rates have no rational incentive to touch their mortgages. Technology valuations and AI credit concerns continue to dominate sentiment, with brief periods of weakness in semiconductor stocks triggering sharp bond rallies as investors seek safe havens. The MBA's week in Chicago highlighted just how wide the gap has grown between mortgage banking cost structures and the revenue lenders can generate in this environment, with multiple industry voices warning that traditional retail delivery models are becoming economically unsustainable. Pending home sales hit a 12-year low as higher rates and limited inventory converge to squeeze both demand and supply, leaving brokers and loan officers fighting harder than ever to capture a smaller pool of qualified buyers. Credit remains surprisingly resilient despite affordability pressures, though FHA originations are climbing as borrowers with moderate credit profiles lean on government programs to bridge the down-payment gap. The tension between rate stability and mortgage demand will likely define the remainder of Q4, with lenders forced to optimize cost structures and technology investments to survive margins that show no sign of meaningful improvement. **Locking vs Floating** Traders continue to assess whether last week's tech-driven rally establishes a floor in yields or merely provides another tactical relief bounce before yields resume their climb. The playbook remains hazardous: lock aggressive borrowers facing imminent closings, float only those with genuine pipeline cushion and strong fallback options. **Today's Events** October Consumer Sentiment (preliminary): Forecast 47.6, Prior 48.1 University of Michigan Consumer Sentiment data may provide clues about whether rising rates and economic uncertainty are finally beginning to dent household confidence. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change |

Market Data
Mortgage Today (AM) - 10/28/26 {{catlist}}
October 28, 2026
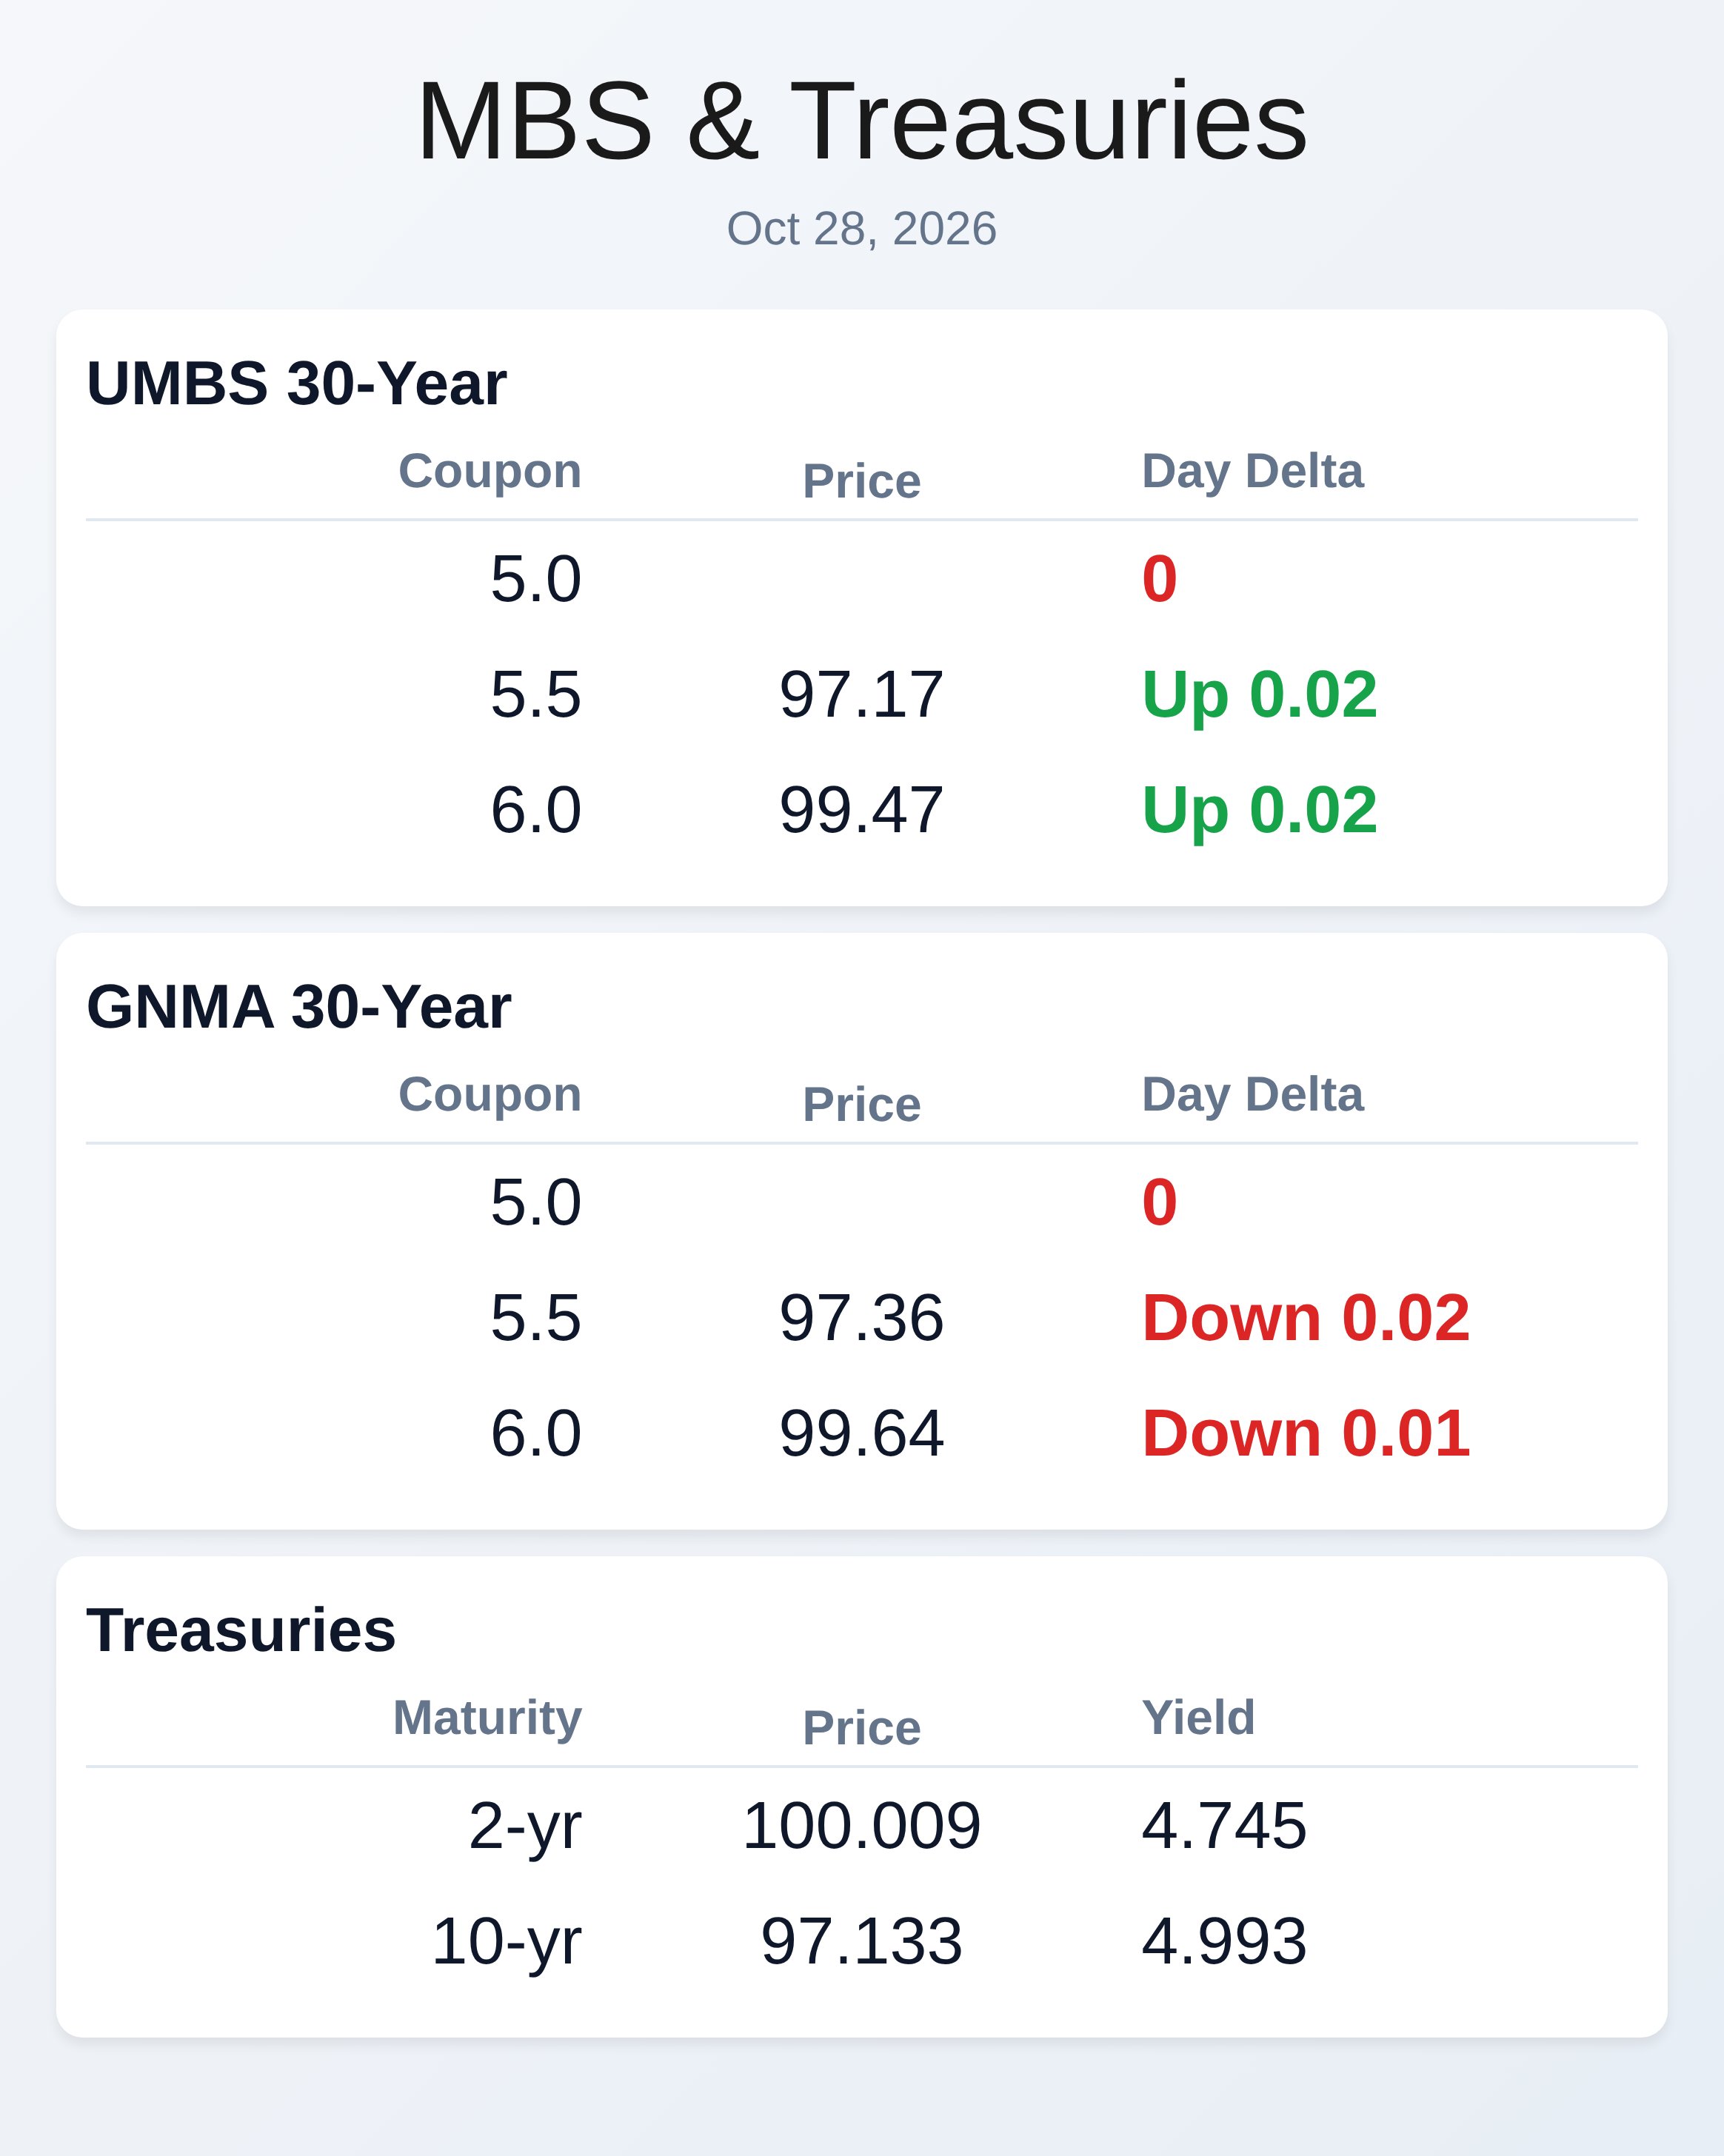
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 10/28/2026** Mortgage markets are absorbing competing pressures this week as the Federal Reserve holds rates steady while signaling hawkish resolve, oil prices surge past $115 a barrel, and housing demand continues its slide despite modest rate relief. The 10-year Treasury is trading near 5.0 percent, down from 5.32 percent in early October following safe-haven flows driven by tech sector volatility and AI valuation concerns. Fannie Mae reported $4.2 billion in third-quarter net income with a near-$120 billion net worth position, reflecting the Government-Sponsored Enterprise's recovery from the pandemic. Industry layoffs at Freddie Mac and compressed margins across independent mortgage banks signal that the 2027 production forecast—now projected below $2 trillion, down 5 percent year-over-year by the MBA—is reshaping staffing and profitability expectations. Loan officer retention has become a critical concern as many lenders reduce positions or shift originators to part-time status amid the lowest purchase application volumes since the financial crisis. Non-QM and adjustable-rate mortgage products have gained meaningful share as borrowers and lenders adapt to elevated rates and shrinking affordability. Pending home sales collapsed 7.3 percent in September while housing starts fell 5.2 percent, with builder confidence hitting its lowest level since June 2012 as rising financing costs and labor shortages squeeze margins. Home prices remain elevated despite modest appreciation of only 2.7 percent annually, forcing borrowers to choose between adjustable-rate mortgages and scaled-down home sizes. Fannie Mae's occupancy verification flags and UAD 3.6 appraisal reporting requirements launching November 2 add compliance complexity and underwriting time. Mortgage insurance repurchase activity jumped 19.5 percent in Q2 2026, with loans originated six to twelve months prior accounting for 46.5 percent of buyback volume, highlighting emerging credit and documentation concerns. Rocket Mortgage led repurchase share at 9.7 percent while Fannie Mae proved notably more aggressive than Freddie Mac on resolution rates. Treasury auction weakness, Federal Reserve runoff of Agency mortgage-backed securities portfolios, and geopolitical tensions over the Strait of Hormuz keep refinancing activity severely suppressed at 61 percent below year-ago levels. FHFA Director Bill Pulte's executive order directing proactive mortgage insurance cancellation and expanded title insurance waivers drew mixed reactions from MBA, brokers, and insurers, though implementation timelines remain uncertain and dependent on GSE guidance. The order addresses only refinancing relief and overlooks jumbo loan competition from banks and credit unions that cap origination fees and offer adjustable-rate products at more attractive pricing. Credit market stress from AI infrastructure financing concerns, combined with sticky inflation and labor-market questions, creates dual risks for lenders managing pipeline hedges and borrower lock expirations. Markets will closely monitor third-quarter GDP data, PCE inflation readings, and initial jobless claims over the coming days, as every basis point of Treasury volatility translates into lock-and-hold decisions for loan officers caught between aggressive pricing and pipeline risk. Origination profitability remains compressed even as Fannie Mae's solid capital position and reduced regulatory uncertainty provide some long-term confidence. Lenders who succeed in this environment are those investing in operational efficiency, non-Agency product diversification, and AI-assisted underwriting while maintaining disciplined credit and pricing strategies. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change |

Market Data
LATEST ARTICLES

RECENT ARTICLES

Mortgage Today (AM) – 02/24/26

February 24th, 2026|Week In Review|

WTMS Blog Today = What's up in Mortgage Today (AM) - 02/24/2026 Bonds are finding strength this morning as general risk aversion dominates trading sentiment amid trade-related uncertainty. The 10-year Treasury yield holds steady at [...]

Mortgage Today (PM) – 02/23/26

February 23rd, 2026|Week In Review|

WTMS Blog Today = What's up in Mortgage Today (PM) - 02/23/2026 General risk aversion is driving a welcome bond rally as the week begins. MBS held at their strongest levels with UMBS 5.0 coupon [...]

Article Archive

My Reading Notes of “The 5th Agreement”- 9

March 14th, 2024|0 Comments

WTMS Blog Today= ???? Elevate Your Real Estate Game with The Four Agreements ???? Attention Real Estate and Mortgage Pros! ???????? Unlock a new level of success with the timeless wisdom of "The [...]

My Reading Notes of “The 5th Agreement”- 8

March 12th, 2024|0 Comments

WTMS Blog Today= ???? Embrace Authenticity in Sales with 'The Fifth Agreement' ???? Real Estate & Mortgage Experts, Unlock Your True Potential! ????✨ Step into the transformative world of "The Fifth Agreement" and [...]

My Reading Notes of “The 5th Agreement”- 7

March 7th, 2024|0 Comments

WTMS Blog Today= ????️ Navigate Real Estate & Mortgage Sales with 'Don't Take Anything Personally' ????️ Real Estate & Mortgage Champions! ???????? Are you ready to revolutionize your approach to sales and client [...]
Subscribe

Send me some brain food

Go to Top