**WTMS Blog Today = What’s up in Mortgage Today (AM) – 11/12/2026**
Bonds are modestly weaker to start, with the 10-year Treasury hovering near 5.00 percent as front-end yields lead and long-end holds steadier. Tuesday’s hotter CPI print (core +0.3 percent m/m) and hawkish Fed chatter pushed markets to fully price a December hike. Oil volatility around Iran headlines remains a swing factor for rates.
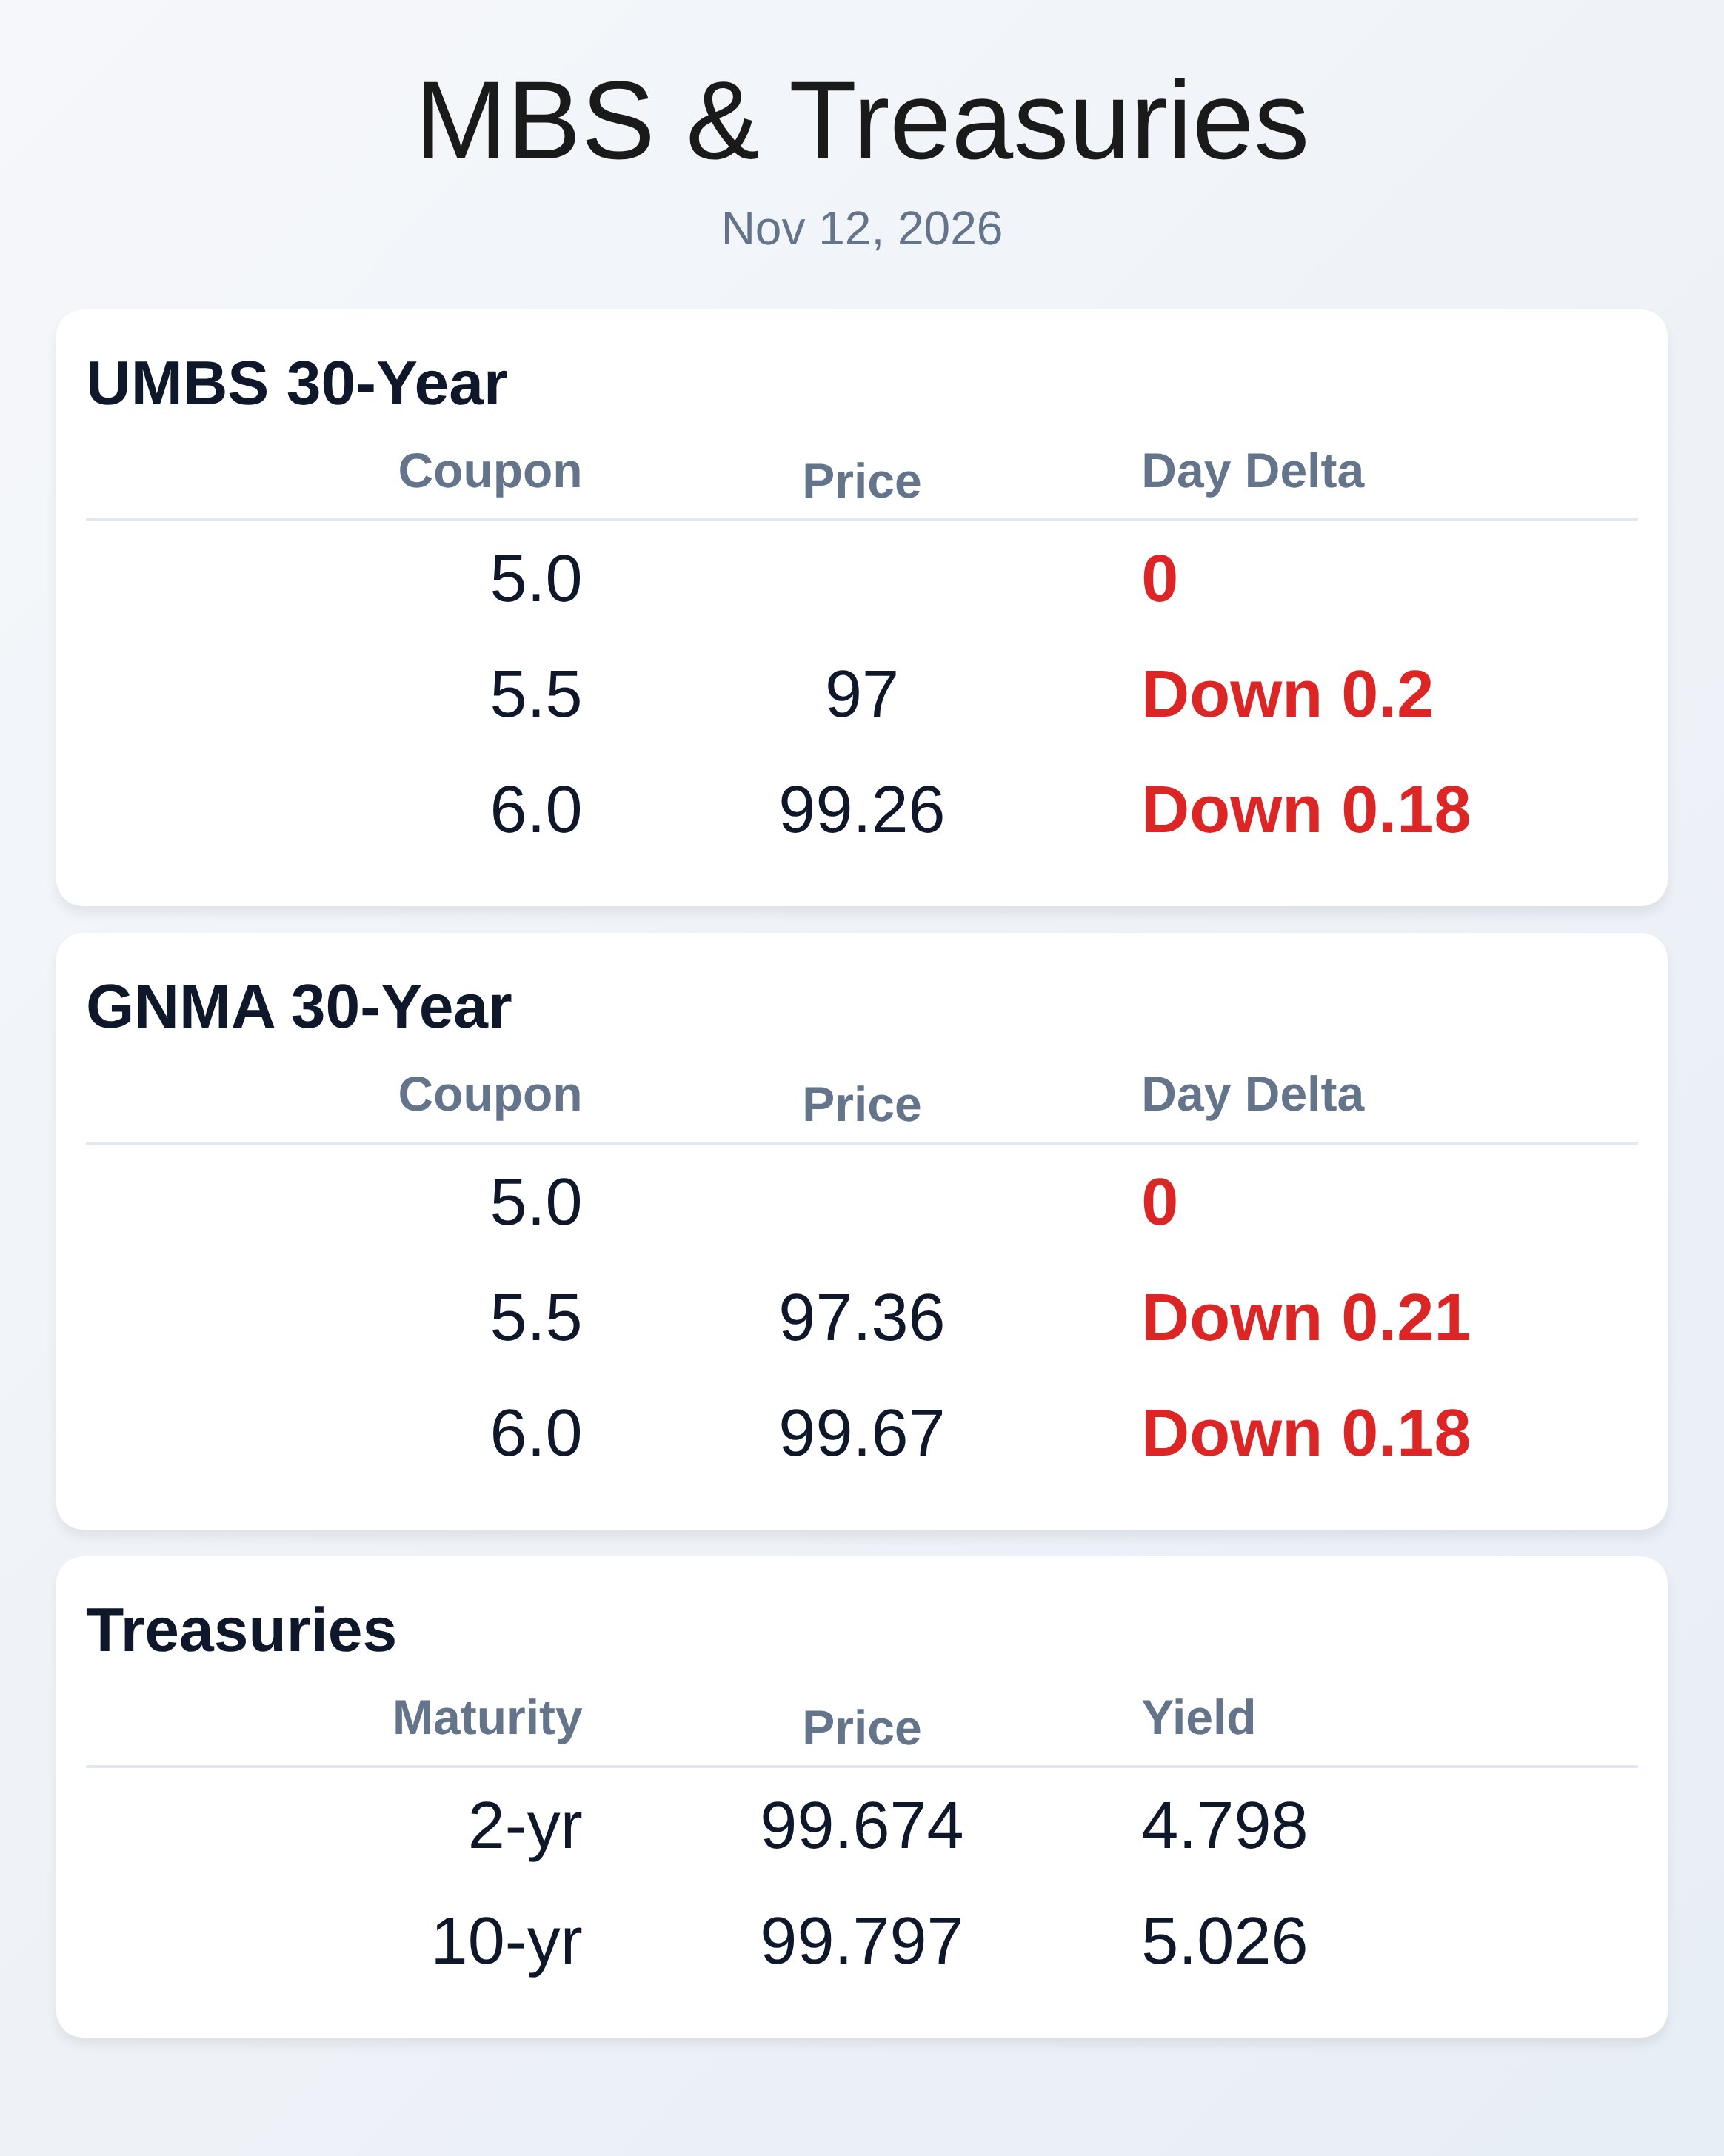
MBS are tracking the Treasury tone with slight morning weakness and mixed spreads. Today’s focus is jobless claims and the 30-year bond auction. In UMBS, last week’s rally delivered the strongest weekly excess returns since early August, led by 30-year 5.0–6.0 coupons and improving specified-pool appetite.
Prepayments slowed again in October, and wide primary–secondary spreads mean rate sheets still lag the Treasury move. The modeled par mortgage rate is back near 7 percent as current coupons sit around the low-6s. After Tuesday’s CPI surprise, production coupons are giving back a bit this morning.
Positioning remains light into year-end, amplifying intraday swings. Ginnie Mae’s share of agency issuance continues to climb, hitting about 42 percent year-to-date and 47 percent in October as more borrowers funnel through FHA/VA. Slower speeds and higher delinquency profiles versus GSE cohorts keep GNMA spreads a touch wider, but seasoned and certain spec stories still screen attractive.
With refinance incentives scarce, shorter-duration 15s and 20s keep shrinking while 30-year GNMA origination dominates. Expect issuers to lean on coupon up-in-quality stories amid rate volatility. Liquidity is thinner, but depth improves on rallies.
Rates trade the macro: CPI beat, a fully priced December hike, and a curve that flattens on front-end repricing. Markets are watching today’s 30-year auction after mixed 3s and 10s, with bidders sensitive to supply at these yield levels. Oil’s bounce on “no deal needed” comments keeps energy/inflation risk in the mix.
Fed speakers stay hawkish-biased, reinforcing a data-dependent path into year-end. Big picture: long-end yields are capped by risk aversion, while the front-end reflects a stickier Fed path. On the ground, mortgage demand improved week-over-week (+6.2 percent), but purchase apps remain 18 percent below last year and refis 57 percent lower.
ARM usage keeps rising (roughly mid‑teens share) as buyers hunt payment relief, while HELOCs gain momentum and could overtake non-QM growth into 2027. Credit remains tight; CFPB supervision has eased, but Reg Z/X rule reviews are underway. Credit-score modernization is messy near-term: Vantage 4.0 and FICO 10T may benefit some borrowers, yet investor acceptance, pricing, and “lowest score” rules can introduce execution risk.
Housing liquidity is thin: contract signings hit a record October low, new listings fell sharply, and asking prices edged lower as inventory nudged higher. Veteran affordability is strained despite VA benefits, aligning with broader cost pressures from taxes, insurance, and utilities. FEMA mapping and data gaps complicate risk pricing in several Sun Belt markets.
Builders rely more on buydowns and incentives to offset rates, but buyer traffic remains rate-level sensitive. Affordability, not weekly rate blips, is still the gating factor for volumes.
**Locking vs Floating**
Momentum is fragile after CPI, and headline risk around oil and Fed rhetoric can flip intraday bias quickly.
With the curve flatter and front-end repricing hawkishly, lenders should expect choppy, range-bound MBS, and be ready for negative reprices on weak auction outcomes. Short-term rallies remain vulnerable without softer inflation or weaker growth data. Float only with cushion and rapid lock triggers; otherwise favor tactical locking on strength, especially for near-term closings.
Don’t be complacent: the recent bond rally has covered a lot of ground and can stall without fresh disinflation signals.
**Today’s Events**
Initial Jobless Claims and Continuing Claims this morning. U.S.
Treasury auctions $25 billion in 30-year bonds at 1:00 p.m. ET. Fed speakers: Richmond’s Barkin and Dallas’ Logan.
Subscribe free at WellThatMakesSense.com for daily mortgage intel in 90 seconds.