**WTMS Blog Today = What’s up in Mortgage Today (PM) – 11/13/2026**
MBS securities weakened early Thursday following hotter-than-expected inflation data and hawkish Federal Reserve commentary, with UMBS 6.0 down over half a point by midday as negative reprices became increasingly likely for lenders with early rate sheets. Treasury yields climbed aggressively, breaching 5 percent on the 10-year as a poorly received $42 billion bond auction signaled weak investor demand, while the 2-year yield also surged amid expectations for additional Fed rate hikes. By Friday, bond losses continued at a more moderate pace with no new catalysts, as PPI data came in line with expectations and curve trading amid lighter liquidity explained much of the intraday volatility.
Core inflation dynamics remain sticky at 0.3 percent month-over-month for the third consecutive month, keeping Fed officials in a hawkish stance despite softer commodity prices. Current-coupon MBS yields climbed to 6.13 percent, reflecting persistent upward pressure on borrowing costs that weigh heavily on mortgage affordability and origination margins. Lenders remain defensive with a “wait and see” posture as bonds have clearly exited October’s rally trend, with any resumption of bullishness dependent on a return of technology sector weakness.
The mortgage industry’s consolidation train is accelerating rapidly, with STRATMOR Group forecasting 46 transactions by year-end as unprofitable lenders face harsh realities about their future. Weak profits, rising technology costs from the artificial intelligence arms race, and the dominance of vertically integrated giants are pushing owners toward the exits—some simply exhausted by the pace of change. Smaller banks with less than $5 billion in assets are re-entering the M&A market, seeing opportunities to leverage existing customer bases and expand home equity products.
Graham’s blunt assessment: “There’s only so much fixed expense you can cut before you’re burning the furniture to stay warm.” Those determined to remain independent must model realistic scenarios and avoid betting on magical refinance booms or big loan officer recruits to save their business models. A major Microsoft Outlook outage on Thursday disrupted mortgage lenders nationwide, though most companies adapted quickly using WhatsApp, Zoom, and text for communications and file handling. The incident exposed the industry’s dangerous dependency on a small number of cloud-based technology providers that interconnect LOSs, PPEs, credit reporting, income verification, document management, and servicing systems.
While a single day without email is manageable, an extended outage affecting critical lending systems would mean missed closing dates, expired rate locks, and delayed fundings. The industry’s billions in digitization spending has created efficiency gains but also multiplied points of failure across vendor ecosystems. Lenders who process clear-to-close packages days in advance weathered the disruption better, though some title companies were less accommodating with accelerated timelines.
**Locking vs Floating**
Maintain a defensive stance and wait for clarity before repositioning. Bonds have exited October’s uptrend, and bullish recovery depends on renewed technology-sector weakness that has largely been defused over the past five trading days. Short-term yields rallied even as longer-term bonds sold off, creating curve-trading opportunities in lighter market conditions.
**Today’s Events**
Core PPI m/m (Oct): 0.3% vs 0.3% forecast, 0.7% previous
Core PPI y/y (Oct): 5.0% vs 5% forecast, 5% previous
PPI m/m (Oct): 0.3% vs 0.4% forecast, 1.3% previous
PPI y/y (Oct): 6.5% vs 6.6% forecast, 6.3% previous
**Bond Pricing**
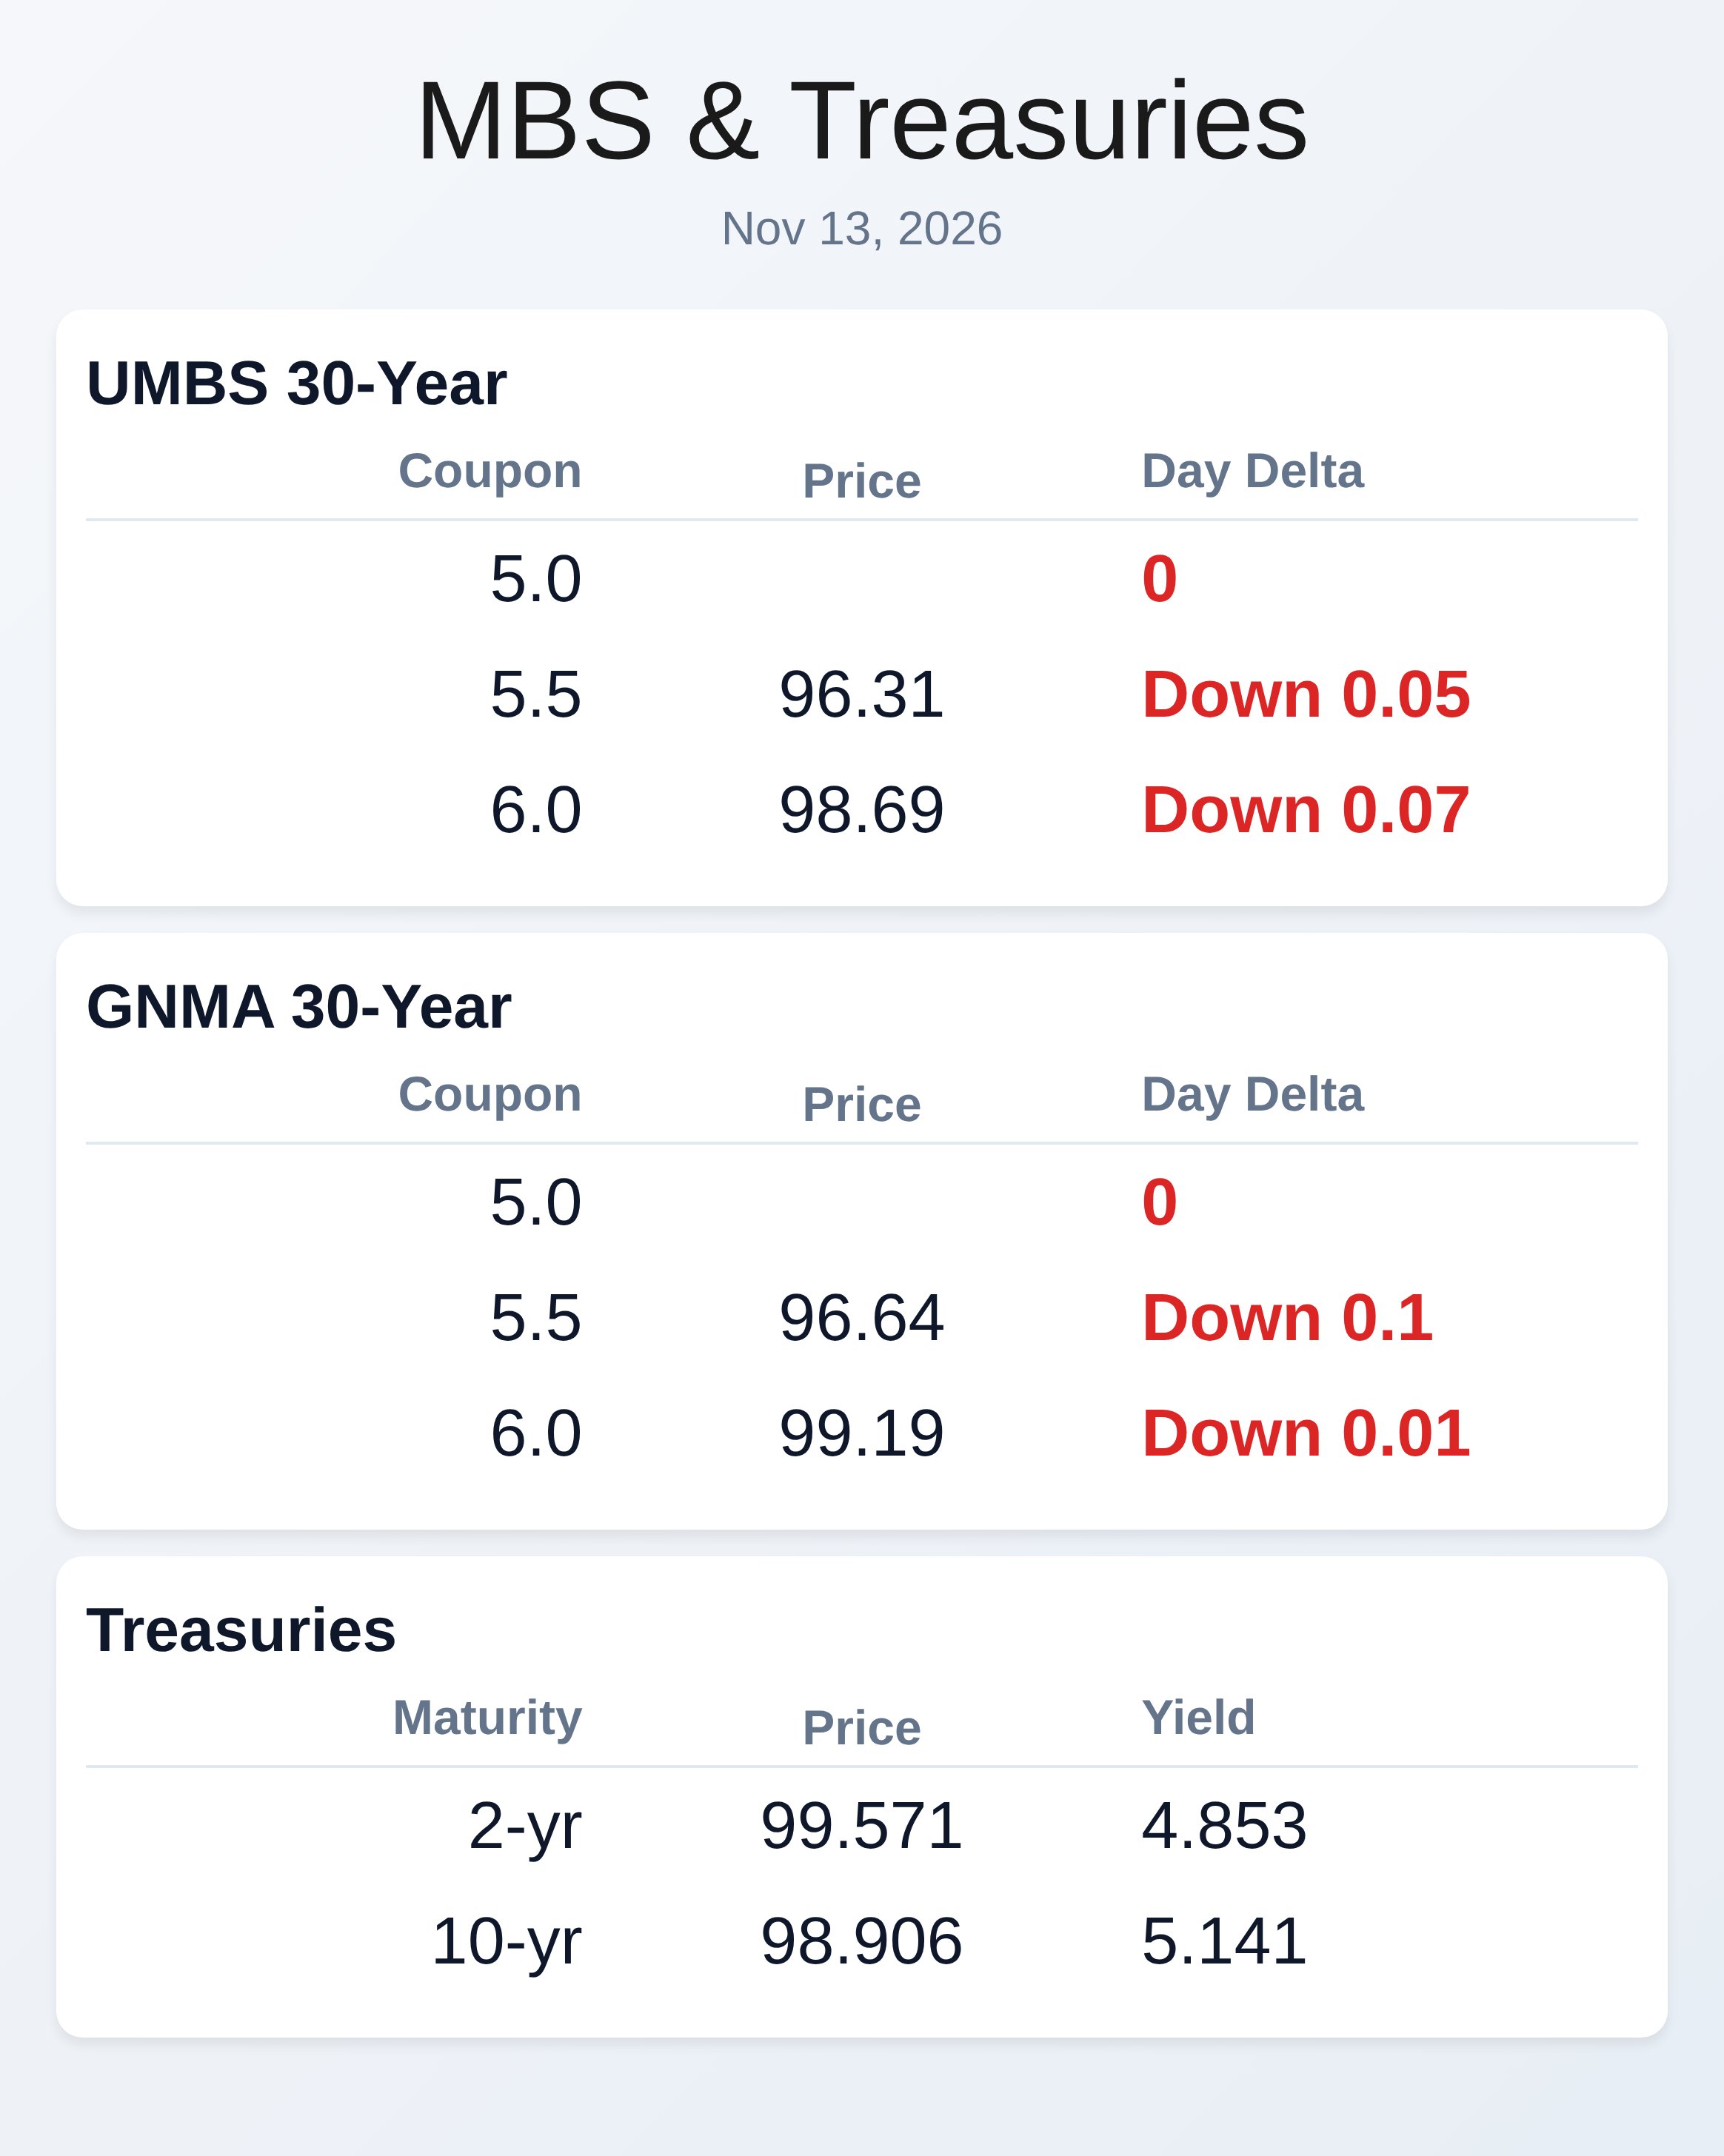
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |