**WTMS Blog Today = What’s up in Mortgage Today (AM) – 09/25/2026**
Mortgage payment relief arrived in August as median monthly payments fell to $2,162, down from $2,175 in July, while household earnings climbed 4.1% year-over-year to outpace the 2.9% payment increase. The Mortgage Bankers Association’s Purchase Applications Payment Index dropped to 154.3, marking a 0.6% decline that signals improving affordability even as 27 states reported payment declines. FHA borrowers benefited most with median payments falling to $1,856, though conventional borrowers saw their payments rise slightly to $2,188.
This data arrives amid broader market pressures where Treasury yields have climbed nearly 44 basis points this month alone. Core capital expenditure data crushed expectations at 1.6% versus a 0.5% forecast, signaling persistent inflation pressures that keep the Federal Reserve in a challenging position as it balances growth signals against stubborn price persistence. Durable goods orders came in flat at 0% when economists predicted a decline of 0.4%, suggesting manufacturing resilience despite rising interest rate headwinds.
The combination of stronger-than-expected inflation data and solid economic output is pushing the market to price in a prolonged higher-for-longer rate environment. Morgan Stanley economists now expect the Fed to stop hiking after December and March—about one hike short of market expectations—but inflation readings like today’s suggest the path remains uncertain. The housing market is shifting leverage toward buyers as new home sales rebounded 6.4% to reach an 684,000 annualized rate in August, the highest level since December 2025, while median prices fell 5.8% year-over-year to $393,700.
Inventory of new homes held steady at 483,000 units with an elevated 8.5-month supply, though just 112,000 homes are completed and ready for immediate occupancy. The Midwest led regional gains with an 84.9% monthly jump, while the Northeast and West posted sharp declines, signaling uneven demand across geographies. Existing home inventory climbed 46% from 2023 levels, forcing sellers to adjust pricing with nearly one in five homes receiving price cuts in August—the highest share for that month since 2020.
HouseCanary received court approval to continue operations in Chapter 11 bankruptcy, allowing the data and appraisal services company to maintain customer support while it restructures and pursues a potentially $175 million claim against Rocket Close from a March 2026 jury award. The filing came after the company defaulted on a $30 million loan, but debtor-in-possession financing now provides liquidity for operations, employee obligations, and customer programs. The bankruptcy could ripple through the market given Google’s reliance on HouseCanary technology for its national home-listings program launched in June.
Rocket Companies disputes the jury award and plans to appeal, creating uncertainty around both companies’ near-term strategic direction. PLACE’s acquisition of Maxwell—a mortgage fintech serving over 400 financial institutions and supporting $130 billion in annual mortgage transactions—expands PLACE’s origination capabilities by adding point-of-sale, business intelligence, fulfillment, and private-label solutions to its real estate platform. Maxwell touches nearly 10% of U.S.
mortgage originations and operates independently under CEO John Paasonen with over 100 employees now joining PLACE. The deal follows PLACE’s August purchase of Radian Group’s real estate services business and a pending acquisition of Radian’s title operations expected to close in the fourth quarter. This consolidation trend reflects the industry’s ongoing push toward integrated platforms.
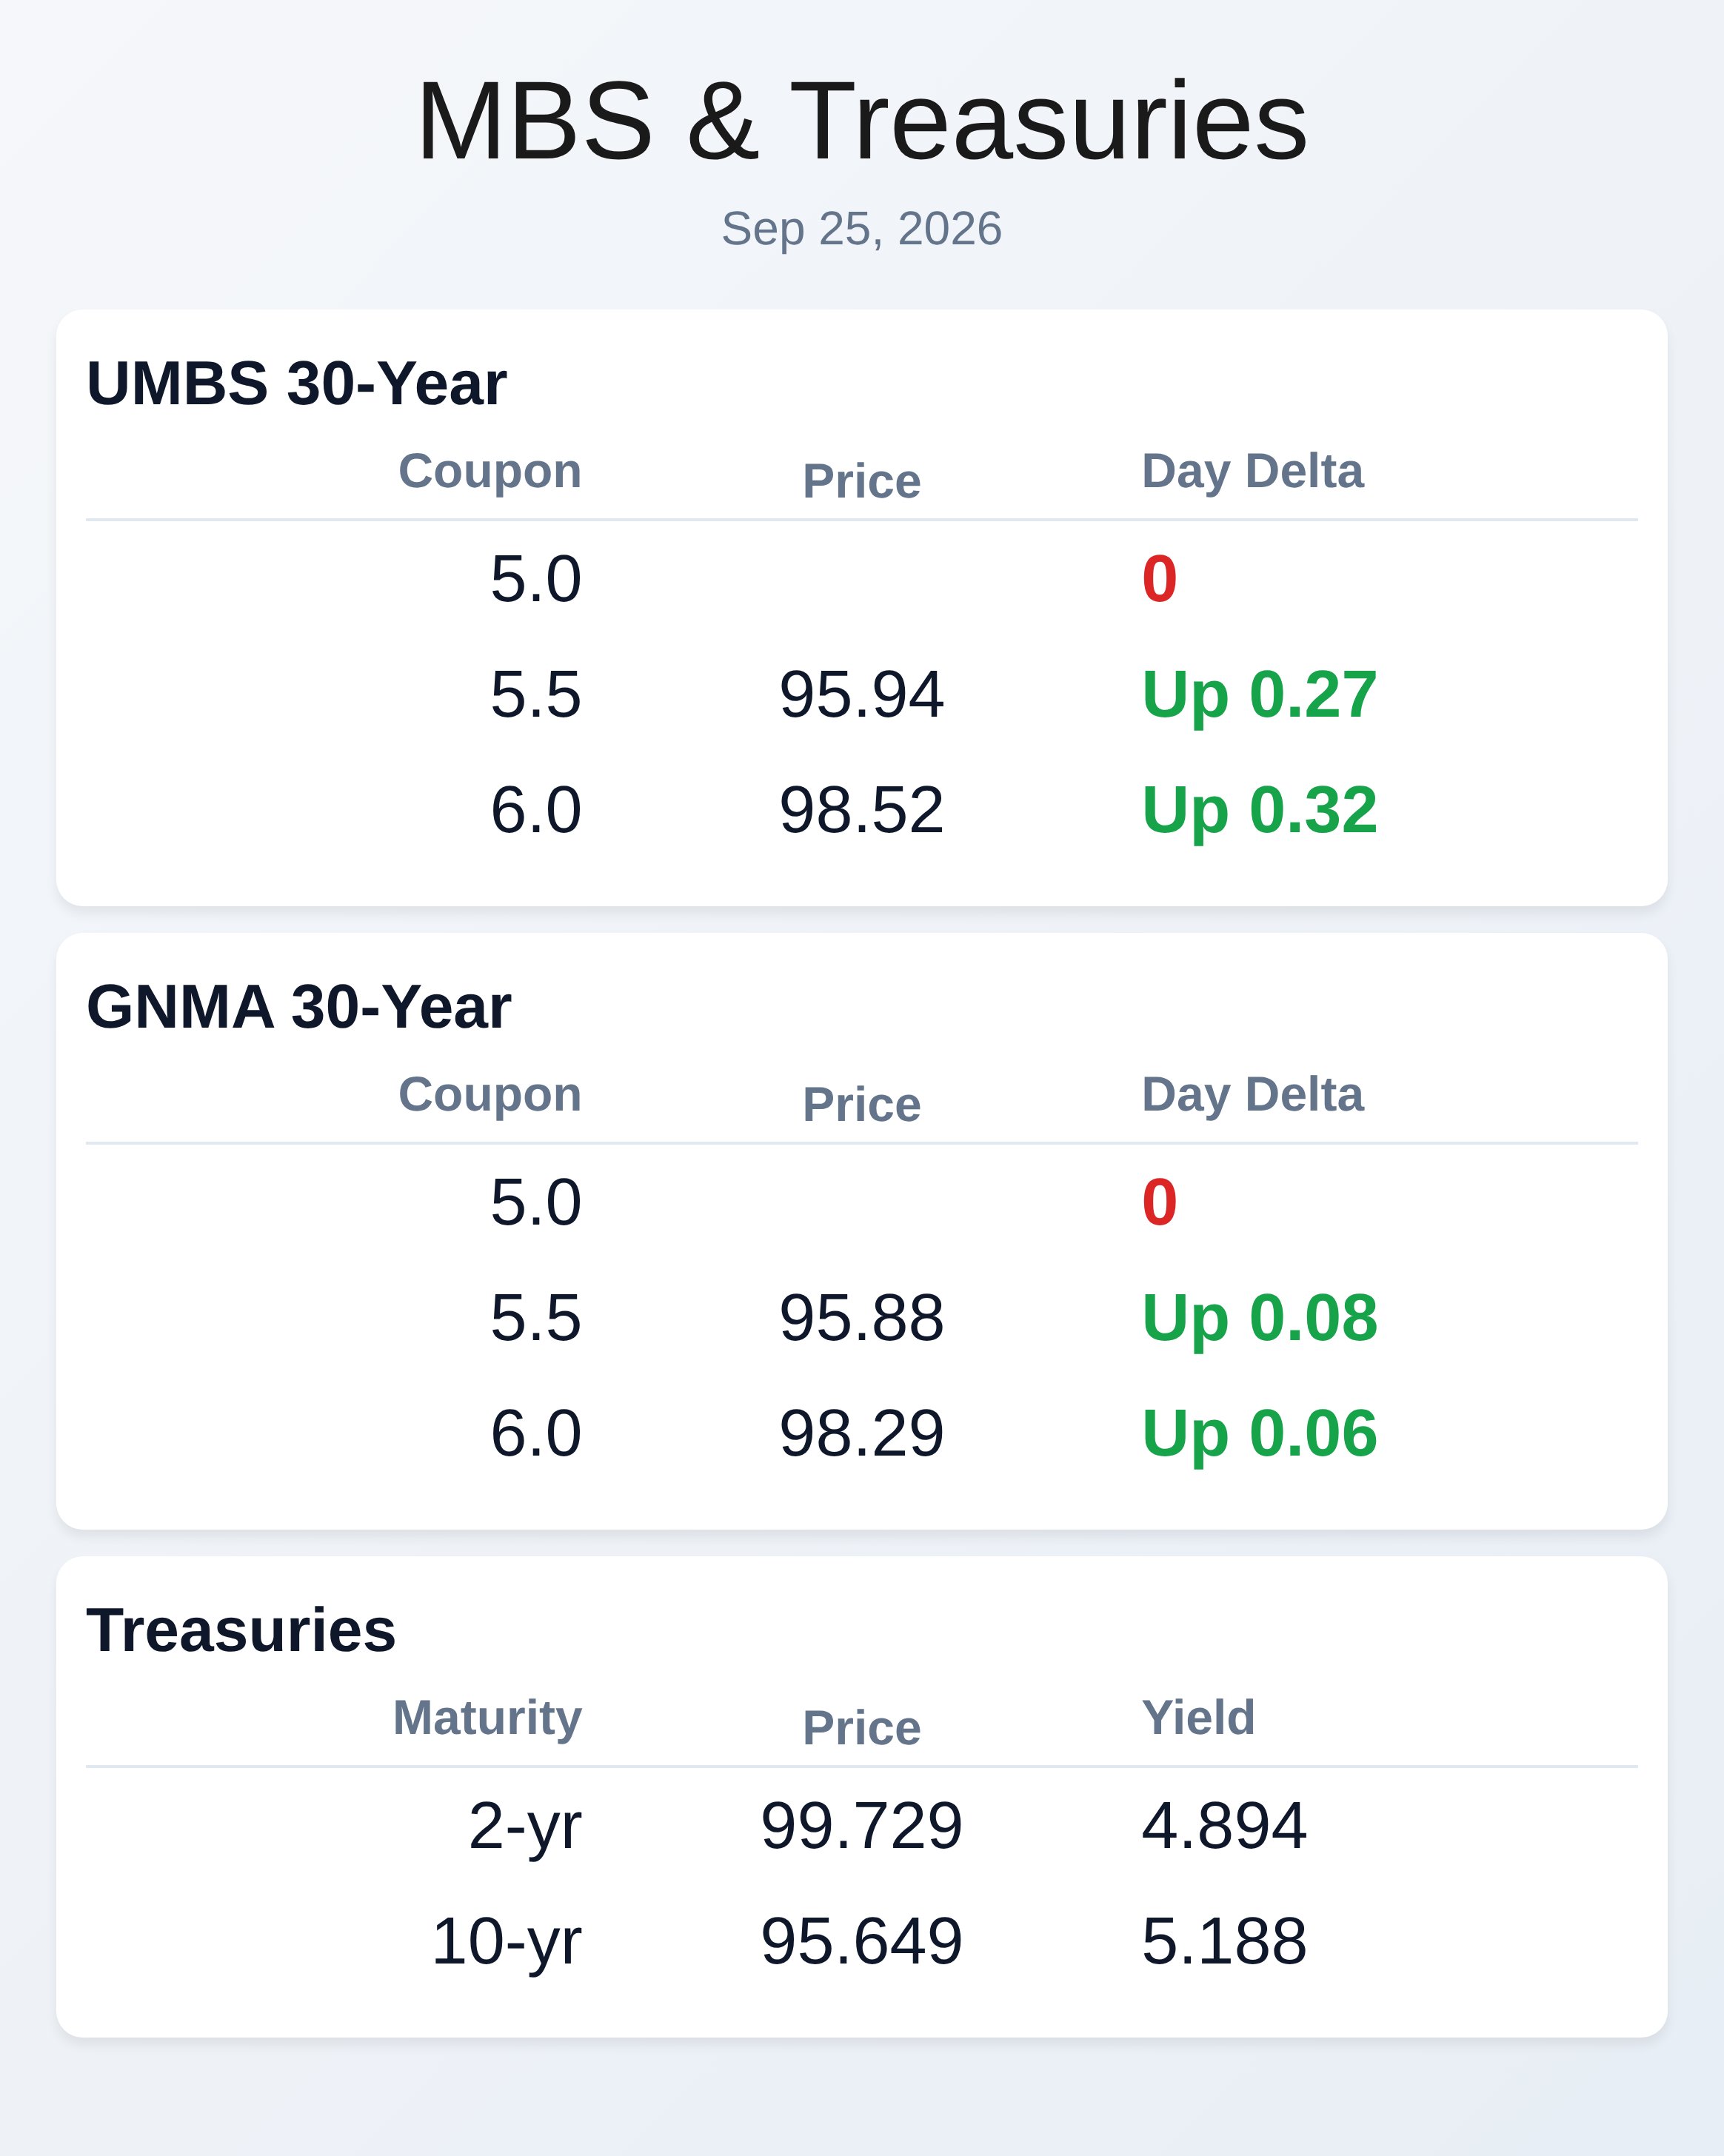
The 10-year Treasury yield is currently trading at 5.171%, down 3.5 basis points from the previous close, while UMBS mortgage-backed securities are showing modest strength with the 6.0 coupon up 0.32 points to 98.52. Market participants are grappling with robust economic data, persistent inflation pressures, and an enormous supply of U.S. government debt that continues to pressure yields higher throughout the month.
The persistent cheapening across the coupon stack and disappointing long-end Treasury auctions suggest demand may be testing its limits, with markets now asking who will be the buyer of size at these levels. Fixed-income traders have rapidly adjusted projections to price in a much higher-for-longer Fed path with the terminal rate approaching 4.86%, nearly 100 basis points above the Fed’s own September projections.
**Locking vs Floating**
Mortgage originators face a challenging environment where catching falling knives before they land remains dangerous, despite the past 48 hours of selling pressure.
Strong economic data and persistent inflation suggest Treasury yields may have further room to climb before bonds become attractive purely on return-to-value metrics. The key question isn’t whether this is the bottom, but rather whether borrowers lock in current rates or continue floating in hopes of future relief that remains uncertain.
**Today’s Events**
Core Capital Expenditure (August): 1.6% vs 0.5% forecast, 0.2% previous
Durable Goods Orders (August): 0% vs -0.4% forecast, 1.1% previous
Final September University of Michigan Consumer Sentiment (scheduled later today)
Remarks from New York Fed President Williams and Kansas City Fed President Schmid
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
| 5.5 | 95.94 | 0.27 |
| 6.0 | 98.52 | 0.32 |
| 5.5 | 95.88 | 0.08 |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
| 2 yr | 4.894 | 99.729 | -0.031 |
| 3 yr | 4.975 | 98.347 | -0.032 |
| 5 yr | 5.033 | 99.855 | -0.021 |
| 7 yr | 5.109 | 99.367 | -0.019 |
| 10 yr | 5.188 | 95.649 | -0.013 |
| 30 yr | 5.487 | 94.7 | 0.01 |