**WTMS Blog Today = What’s up in Mortgage Today (AM) – 10/08/2026**
Bonds surrendered early-morning gains as Federal Reserve Governor Chris Waller signaled that additional rate hikes remain on the table despite September’s softer payroll report. The 10-year Treasury yield climbed to 5.343% from the prior close, erasing gains driven by overnight strength in Japanese government bonds and a dip in crude oil below $98 per barrel. UMBS 6.0 coupons fell 25 basis points to 97.58, while GNMA 6.0 declined 9 basis points to 98.16, reflecting persistent downward pressure on mortgage-backed securities.
Waller’s hawkish comments on persistent inflation and unanchored inflation expectations reignited concerns about the Fed’s commitment to tighter policy through at least mid-2027. Oil prices rebounding alongside Treasury weakness suggest energy inflation remains a structural headwind for originators targeting rate-sensitive refinance activity. The U.S.
trade deficit widened to $105.6 billion in August, exceeding economist forecasts of $102.1 billion and underscoring the resilience in domestic demand despite elevated interest rates. Imports surged 4.3% while exports rose only 1.4%, highlighting the asymmetry driving global fiscal concerns and weighing on international bond markets. France’s 10-year yield spread over Germany narrowed sharply after Marine Le Pen’s deficit-reduction proposal, but global sovereign debt anxiety continues to feed spillover pressure into U.S.
Treasuries. The broader equity rally powered by artificial intelligence deals and strong corporate earnings has competed aggressively for investor capital, crowding out traditional bond demand. For mortgage sellers, this dynamic means secondary marketing margins remain compressed as investors prioritize higher-yielding equities and corporate debt over agency MBS.
Elevated Treasury issuance tied to the U.S. fiscal deficit, combined with war-related inflation pressures and tariff-induced price pass-through, continues to anchor longer-dated yields near multi-year highs. The Federal Reserve’s willingness to deploy the Fed Funds Rate as an anti-inflation tool, along with genuine economic resilience in services data and labor markets, has sustained the upward bias in the yield curve.
Foreign demand for U.S. debt has weakened gradually due to trade relationship deterioration and tariff concerns, further reducing a traditional source of bond market support. Market participants remain defensive pending tangible evidence of a yield correction, which historically requires sustained daily declines of 6 basis points or more.
Originators face headwinds locking borrowers into mid-to-upper-7% mortgage rates, constraining pipeline volume and forcing margin compression strategies on competitive products. Today’s economic calendar included the August Trade Balance and weekly jobless claims data, with the latter showing 197,000 initial claims against a forecast of 200,000. Fed remarks from Governor Bowman, Boston President Logan, and New York President Williams preceded a $58 billion auction of 3-year Treasury notes, testing investor appetite amid elevated yields and fiscal uncertainty.
Retail sentiment appears resilient according to preliminary CNBC/NRF monitoring, though services-sector price pressures remain a persistent concern for policymakers assessing inflation momentum. The 30-year Treasury auction scheduled for later in the week will provide critical insight into investor demand at current yield levels above 5.6%. Market participants should monitor whether strong economic data continues to argue for additional Fed tightening or whether credit stress signals shift the inflation-versus-growth narrative.
Secondary market strategists noted that the intraday bond recovery mid-session failed to establish a convincing floor, as yields hit new long-term highs before rebounding. This pattern reinforces the prevailing trend toward higher rates rather than signaling a durable reversal in the fixed-income outlook. The correlation between oil prices and Treasury yields remains loose but notable, suggesting energy inflation expectations continue to drive term premium compression across the curve.
Rate locks remain appropriate only for borrowers with committed closing dates within 30 days, as floating-rate risk continues to outweigh the cost of locking given persistent Fed hawkishness. Loan officers should expect continued pressure on product margins and pipeline velocity until evidence of a meaningful yield correction materializes. Capital markets leaders are recalibrating hedging strategies and secondary marketing operations for an extended higher-rate environment, with some vendors announcing AI-native systems designed to optimize margin capture in compressed-spread scenarios.
The mortgage industry’s technology vendors gathered at industry conferences this week to demonstrate how intelligent automation could help originators reduce costs and improve execution speed despite lower-volume production. Correspondent partners and wholesale platforms continue to expand down-payment assistance options and deliver non-QM and alternative credit products to maintain borrower access. Servicers report elevated focus on fee prevention and operational efficiency as loan volumes adjust to the new rate regime.
For originators, now is the time to stress-test business model assumptions and evaluate whether current staffing and technology investments align with a prolonged period of higher rates and reduced transaction volume.
**Locking vs Floating**
Remain defensive and avoid aggressive locking until the market demonstrates a successful yield correction, defined as average daily declines of at least 6 basis points sustained over two consecutive trading days. War-related inflation pressures, elevated Treasury issuance driven by fiscal imbalances, strong corporate bond competition, resilient economic data, and the Fed’s commitment to fighting inflation all contribute to the ongoing upward bias in rates.
Foreign investor demand continues to weaken due to tariff and trade concerns, removing a traditional source of bond market support. The prevailing trend remains firmly toward higher rates, making rate locks appropriate only for borrowers with imminent, committed closing dates. Floating rate risk remains preferable to locking given the Fed’s persistent hawkish stance and persistent inflation concerns.
**Today’s Events**
August Trade Balance released at 8:30 AM ET showed a widening deficit to $105.6 billion, exceeding the $102.1 billion forecast. Weekly jobless claims came in at 197,000 versus a forecast of 200,000. Fed remarks from Governor Bowman, Boston President Logan, and New York President Williams were scheduled throughout the day.
Treasury auction of $58 billion in 3-year notes was held at 1:00 PM ET. 30-year Treasury bond auction was scheduled for later in the week.
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
**UMBS 30 Year**
| Coupon | Price | Intra-Day Change |
|—:|—:|—:|
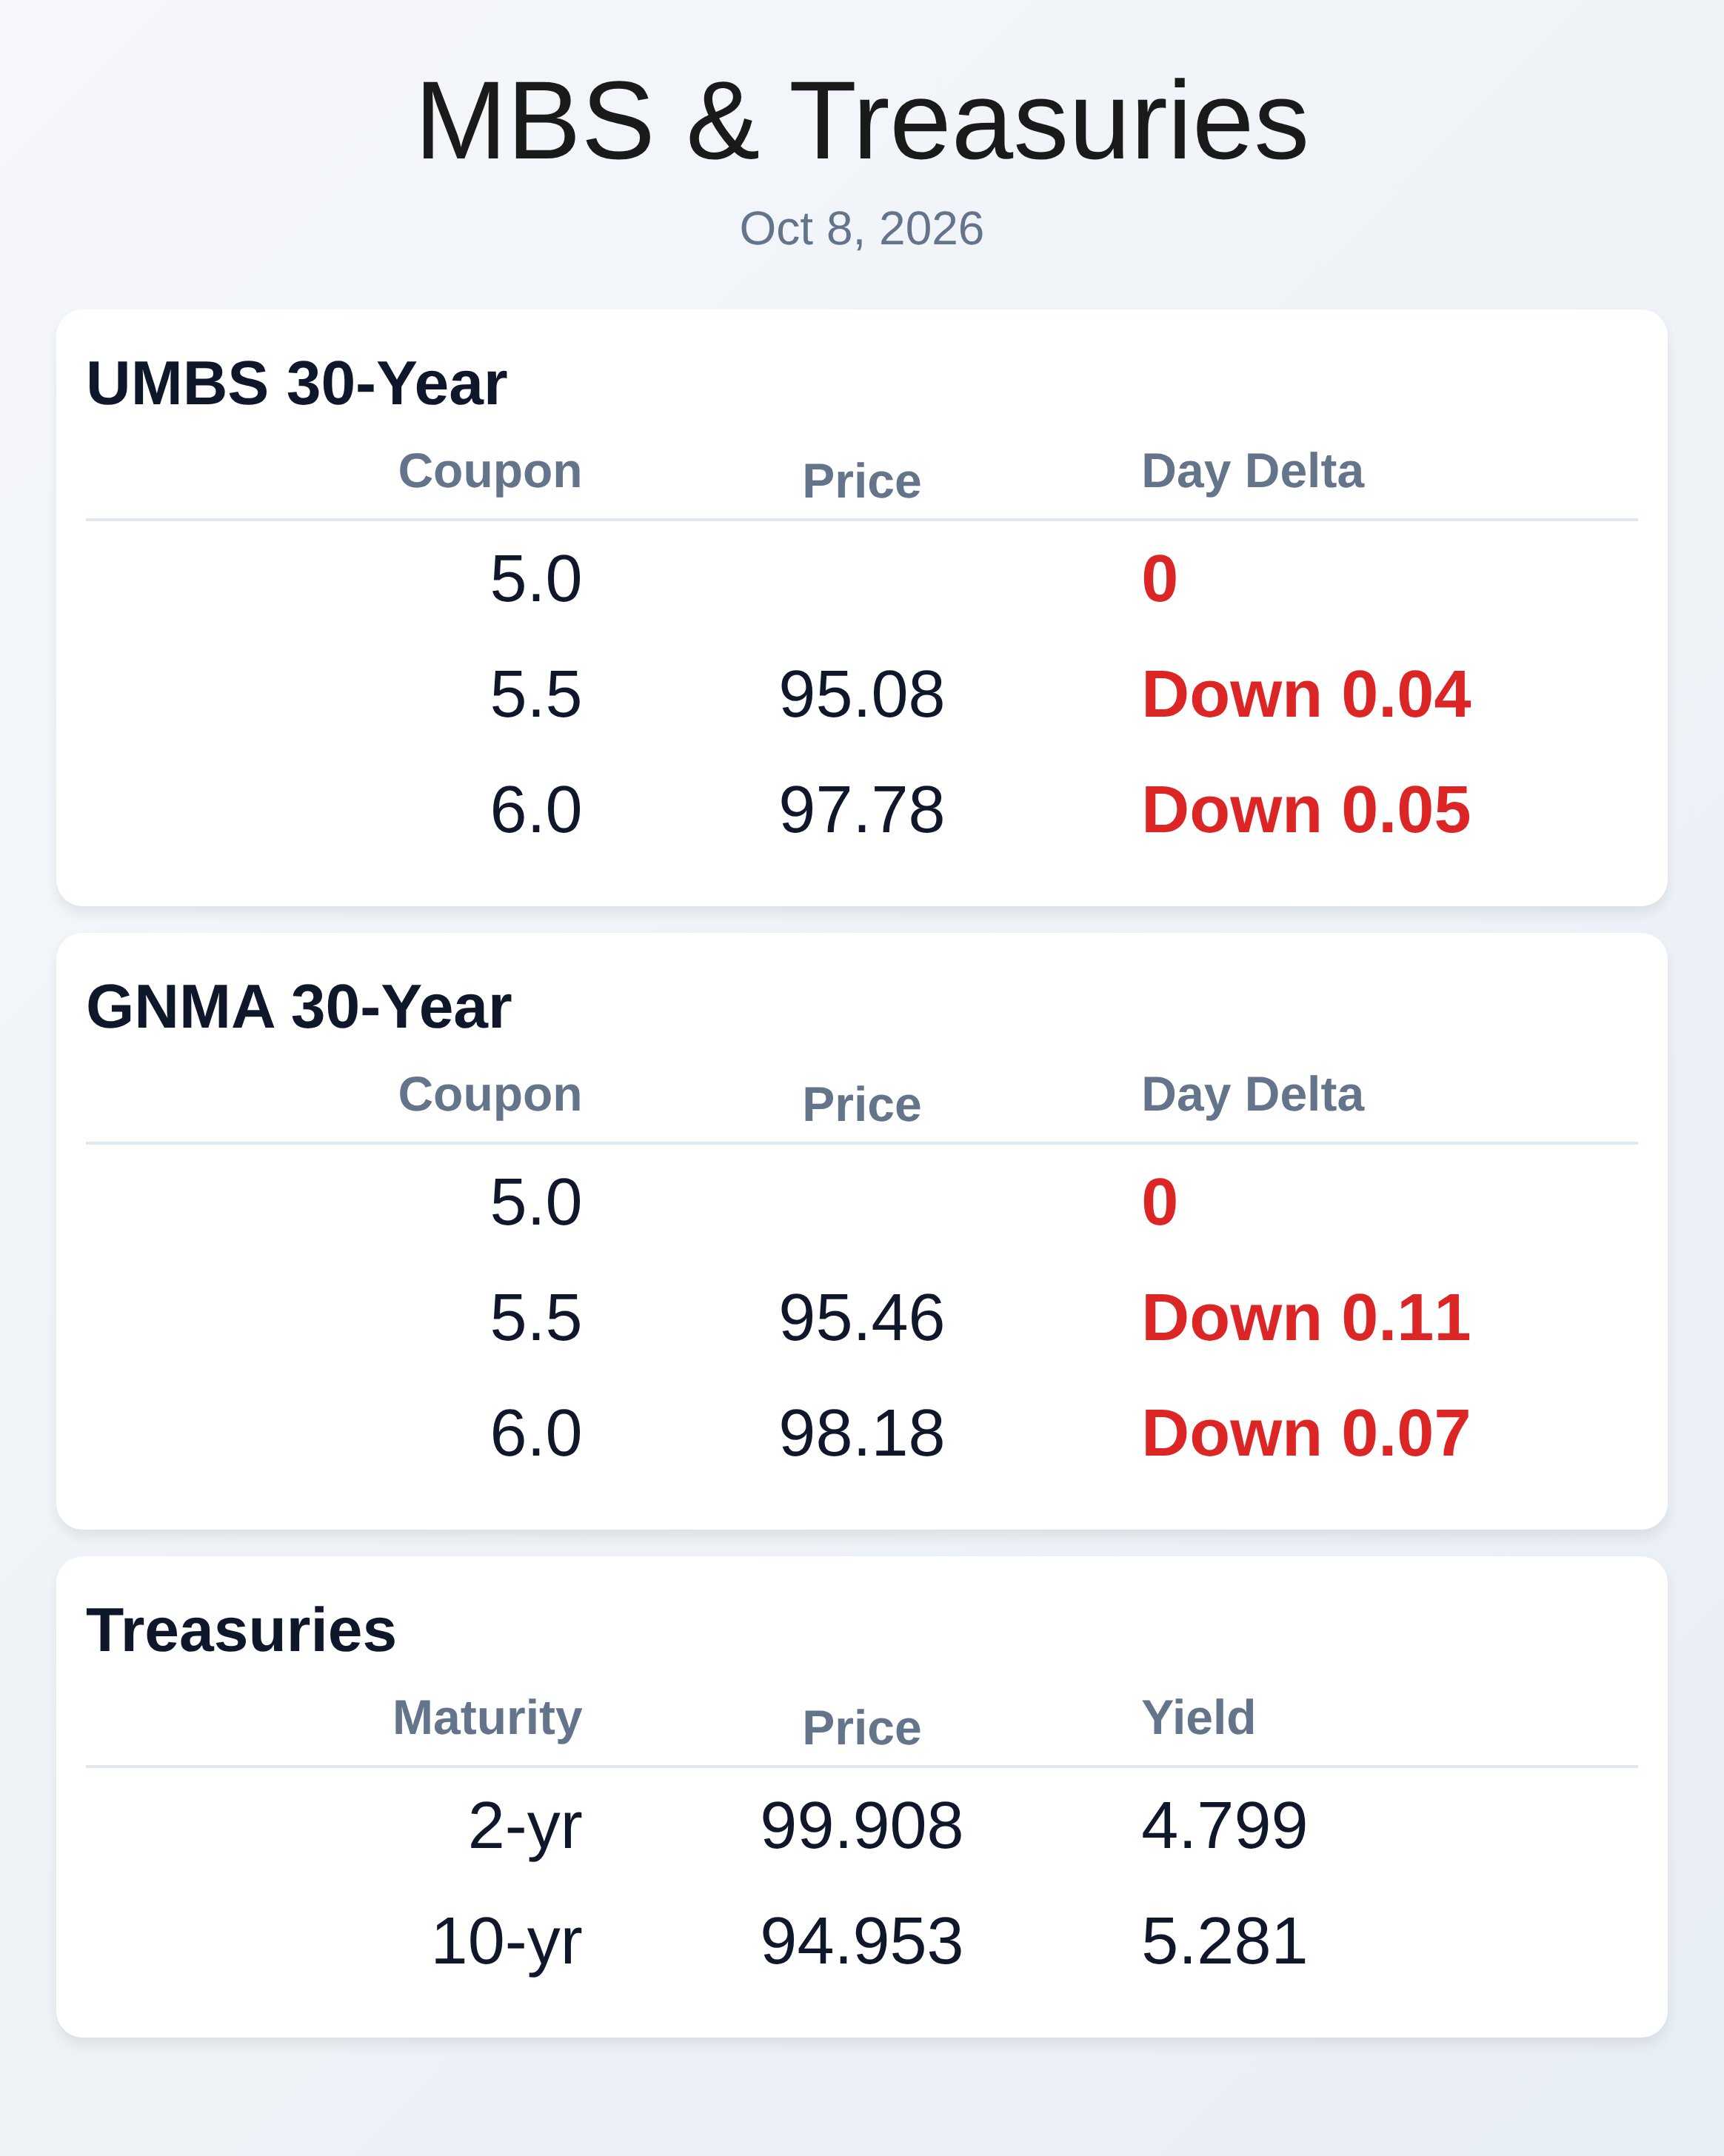
| 5.5 | 95.08 | -0.04 |
| 6.0 | 97.78 | -0.05 |
| 6.5 | 100.30 | -0.01 |
**GNMA 30 Year**
| Coupon | Price | Intra-Day Change |
|—:|—:|—:|
| 5.5 | 95.46 | -0.11 |
| 6.0 | 98.18 | -0.07 |
| 6.5 | 100.49 | -0.16 |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
|—:|—:|—:|—:|
| 2 yr | 4.799 | 99.908 | 0.040 |
| 3 yr | 4.941 | 99.818 | 0.032 |
| 5 yr | 5.045 | 99.802 | 0.021 |
| 7 yr | 5.166 | 99.038 | 0.008 |
| 10 yr | 5.281 | 94.953 | -0.010 |
| 30 yr | 5.646 | 92.509 | -0.024 |
Stay informed on mortgage markets and secondary strategy.
Subscribe free at WellThatMakesSense.com.