**WTMS Blog Today = What’s up in Mortgage Today (AM) – 10/08/2026**
Treasury yields jumped overnight as Federal Reserve Governor Chris Waller signaled that more rate hikes are needed due to strong economic data and persistent inflation concerns. The 10-year Treasury climbed above 5.34 percent, pushing mortgage rates firmly into mid-7 percent territory as bond markets wrestled with conflicting signals from oil prices and Fed communications. Mortgage-backed securities weakened alongside the broader selloff, with UMBS 6.0 coupons down roughly 22 basis points from recent highs.
The persistent upward march in rates shows no signs of reversing without meaningful evidence of economic weakness or inflation decline. For mortgage originators, today’s action reinforces the defensive posture that has defined the past six weeks of market trading. Waller’s hawkish comments hit the short end of the curve hardest, pulling Fed Funds futures back to levels that signal rising rate expectations well into 2027.
The yield curve continued its steepening bias as longer-term bonds absorbed selling pressure from the war-driven inflation narrative, elevated Treasury issuance tied to fiscal imbalances, and ongoing competition for investor demand from equities and corporate debt. Oil prices also rose in sympathy with the broader commodity complex, adding another layer of inflation concern to an already hostile rate backdrop. Foreign demand for U.S.
Treasuries continues to weaken amid tariff concerns and deteriorating trade relationships. The fundamental drivers that pushed rates higher since August remain firmly in place with no clear catalysts for meaningful relief. Market observers note that midday recoveries, like the one seen earlier this week, fail to reverse the prevailing uptrend unless yields fall at least 6 basis points daily for multiple consecutive days.
The absence of such a correction pattern suggests the current rising-rate environment is structural rather than cyclical. Jobless claims and continued claims data released this morning came in slightly better than expected, adding fuel to the strong-economy narrative that justifies higher rates. Upcoming Treasury auctions of 10-year and 30-year debt this week will test investor appetite at increasingly elevated yield levels.
Rate lock activity remains subdued as mortgage professionals await concrete signs of market stabilization before committing to longer-term positions. European bond market volatility, particularly in French sovereign debt, continues to create spillover effects in U.S. Treasury markets despite lower oil prices.
The ECB’s ongoing inflation concerns and geopolitical uncertainties abroad reinforce the risk-on bias in equities and risk-off bias in fixed income. U.S. mortgage servicers and secondary marketing teams are managing heightened basis risk as mortgage pools reprice daily in reaction to yield volatility.
Warehouse lending capacity remains fluid, but pricing has tightened as lenders navigate the uncertain rate path ahead. The broader market consensus suggests that relief, if it comes, will require either a dramatic shift in geopolitical tensions or clear evidence of economic deceleration. Mortgage originators should remain defensive in their pipeline management and client communication strategies.
Lock/float decision trees favor locking borrower rates despite pain, as the risk-reward profile continues to favor protection over speculation on further rallies. Correspondent lending networks are experiencing elevated pull-through volatility as borrowers struggle with higher payment obligations in the current rate environment. Staffing decisions at larger production shops are likely being deferred pending clarity on the sustainability of origination volumes at current rate levels.
The industry’s weekly dashboards now consistently show negative intra-day momentum even when morning recoveries create false hope.
**Locking vs Floating**
Remain defensive until Treasury yields demonstrate sustainable downward momentum of at least 6 basis points per day for two consecutive days. Rising rate momentum since August has been relentless and driven by multiple structural factors: geopolitical inflation impacts, elevated fiscal issuance, corporate bond competition for investor capital, equity market strength, declining foreign demand tied to tariffs, resilient economic data, and Federal Reserve determination to combat inflation.
Mortgage professionals should prioritize locking borrower rates to secure margin and certainty rather than speculating on mean reversion that has not yet materialized.
**Today’s Events**
Thursday, October 8: Jobless Claims (8:30 AM) forecast 200K vs. prior 197K; Continued Claims (8:30 AM) forecast 1,710K vs.
prior 1,701K; Fed remarks from Governor Chris Waller; Treasury auctions of 10-year and 30-year securities.
**Bond Pricing**
**UMBS 30 yr**
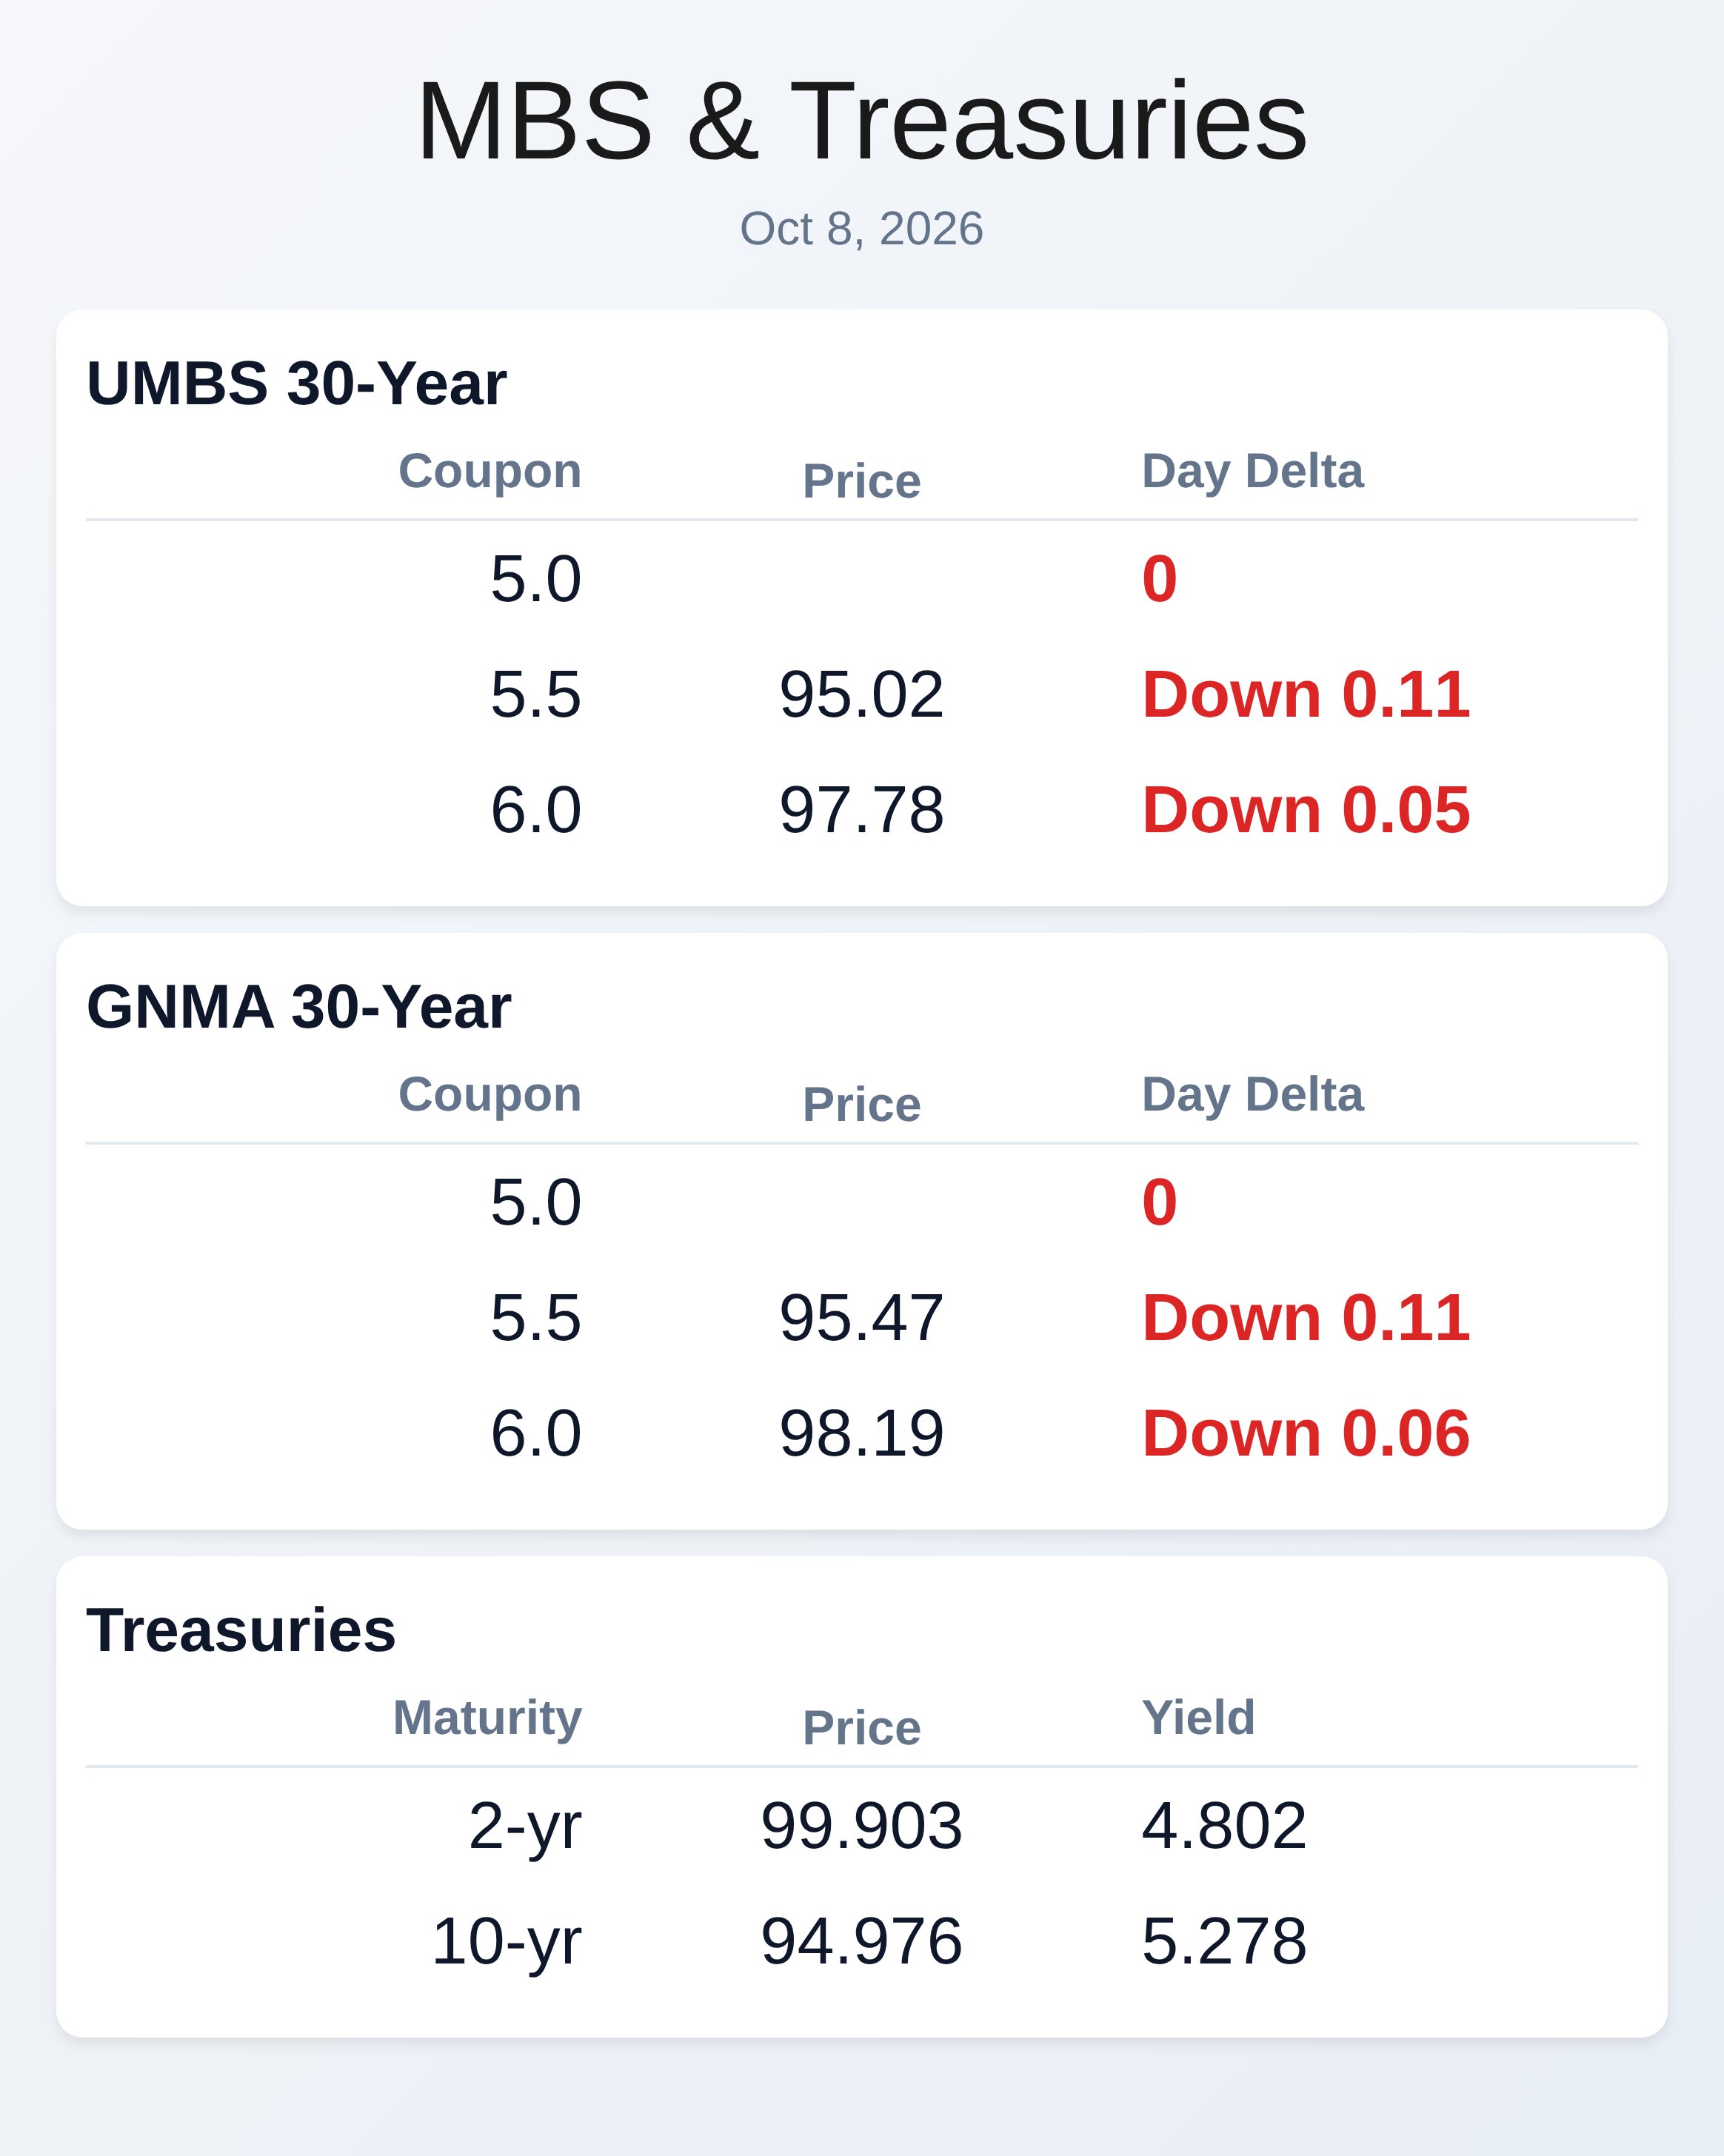
| Coupon | Price | Intra-Day Change |
| 5.5 | 95.02 | -0.11 |
| 6.0 | 97.78 | -0.05 |
| 5.5 | 95.47 | -0.11 |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
| 10yr | 5.278 | 94.976 | -0.013 |
| 30yr | 5.644 | 92.540 | -0.027 |