**WTMS Blog Today = What’s up in Mortgage Today (AM) – 10/14/2026**
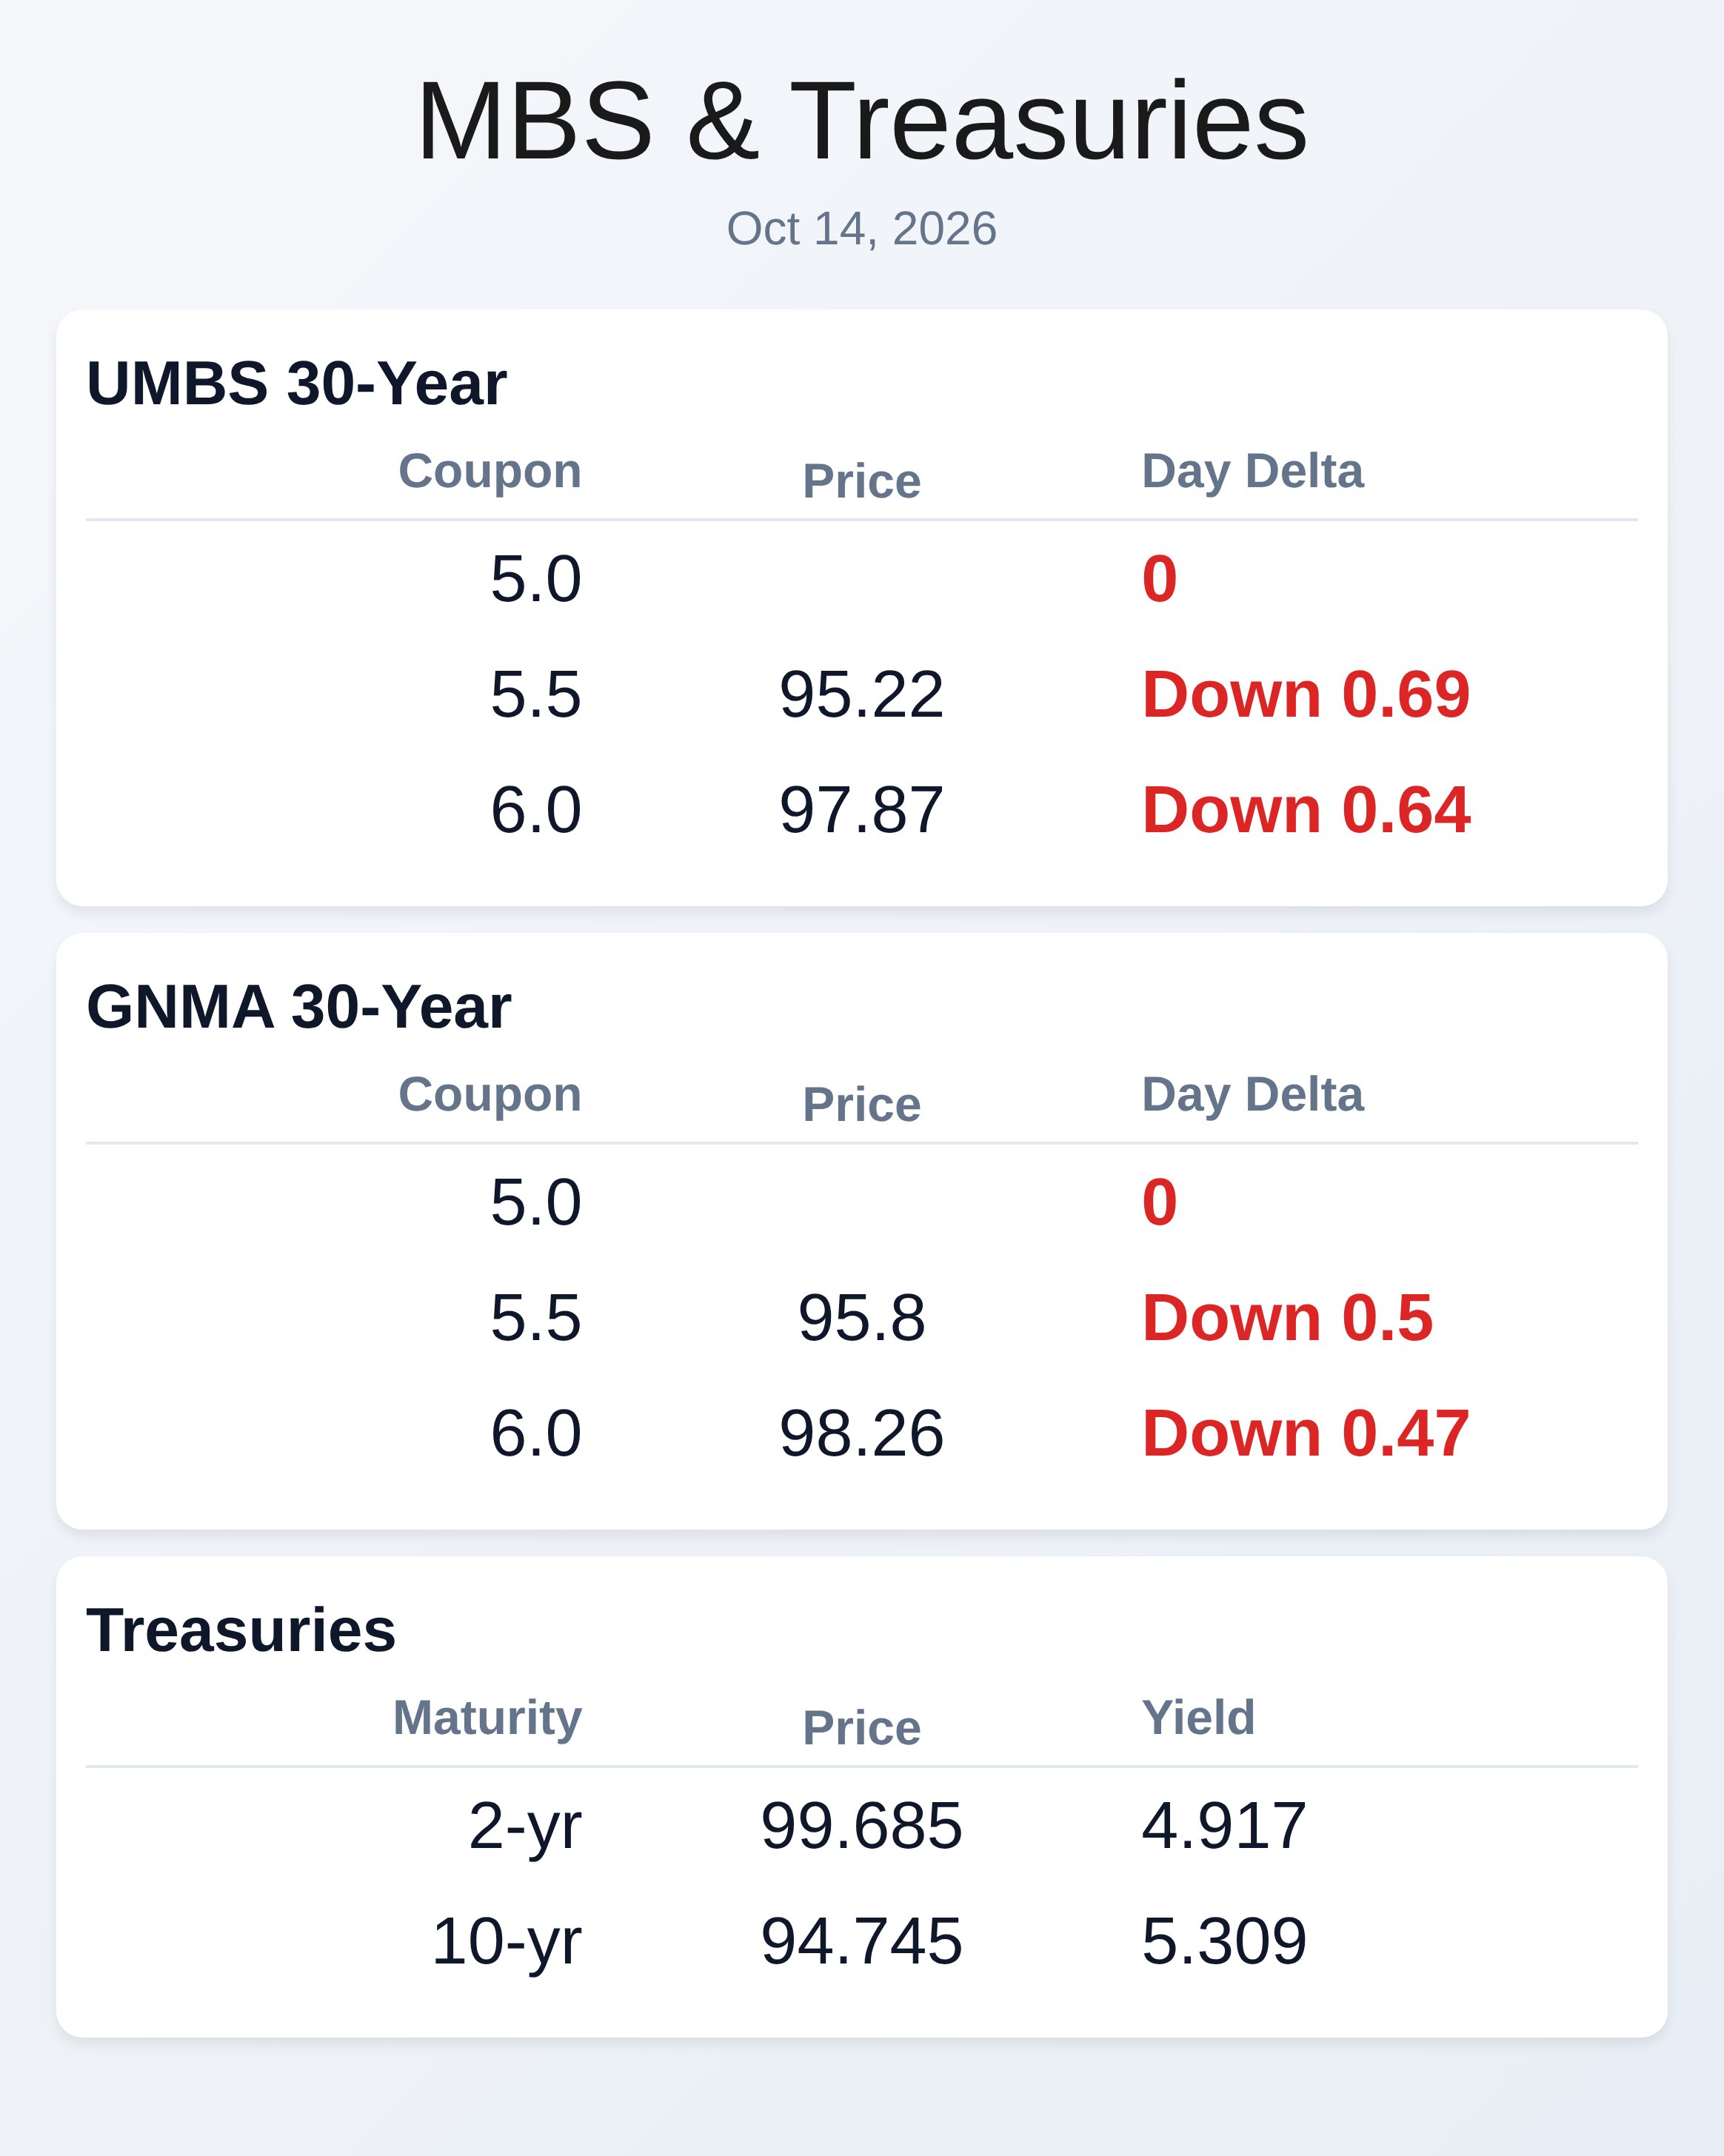
Mortgage originators faced a sharp market reset today as hotter-than-expected inflation data sent Treasury yields climbing and agency MBS securities tumbling. Core consumer price inflation came in at 0.335 percent, well above the 0.2 percent forecast, pushing the 10-year Treasury to 5.275 percent and triggering rapid repricing across the mortgage-backed securities complex. The 30-year UMBS 6.0 coupon fell approximately 70 basis points in morning trading, signaling that pipeline hedging and investor positioning are absorbing significant convexity-related selling pressure.
Fed Funds Futures immediately priced in expectations for an additional rate hike, creating two-sided risk for lenders caught between duration extension fears and potential Treasury rallies that could force costly hedge rebalancing. This inflationary surprise underscores why origination profitability remains tethered to basis volatility and macro uncertainty. Mortgage production metrics from September reveal a market flexing around rising rates, with total lock volume declining 2 percent month-over-month and refinance volume dropping 13 percent year-over-year.
What kept purchase volume afloat was product mix diversification: non-QM locked loans jumped 8 percent from August and now represent 12 percent of total production, up nearly 5 percentage points annually, while ARM usage reached 14 percent, the highest level since 2019. Lenders stretched beyond conforming conforming programs to keep deals moving forward as higher rates compressed margins and borrower capacity. This shift toward alternative products and shorter-duration loans is precisely what mortgage bankers should expect as the rate environment remains restrictive and economic resilience is tested by tighter financial conditions.
Industry consolidation continued with Optimal Blue’s acquisition of Usherpa, a mortgage CRM and lead-generation platform serving over 200,000 loan officers nationwide. The deal aims to unify pricing intelligence, borrower engagement, and origination workflows into a single command center that combines Optimal Blue’s rate and eligibility technology with Usherpa’s CRM capabilities. Meanwhile, Newrez and eXp Realty launched Revenos Mortgage, a joint venture designed to serve eXp’s agents following the wind-down of Success Lending and marking a first-of-its-kind partnership at that scale.
These moves signal continued consolidation and channel partnerships as lenders seek to capture real estate referral volume and streamline the borrower journey from application through closing. Market participants are watching loanDepot, which was trading around 56 cents per share and faces a New York Stock Exchange deficiency notice for failure to meet continued listing standards. The company reported strong third-quarter momentum with 25 percent unit volume growth and a 33 percent jump in purchase market share, though the stock’s weakness suggests investor skepticism about sustainability.
LoanDepot’s successful re-entry into wholesale lending and expansion into home equity demonstrates operational flexibility, but capital management and profitability remain critical to addressing the listing challenge. The company’s ability to execute its transformation agenda will be closely watched by the broader industry as a barometer of market consolidation pressures. Regulatory and compliance headwinds are mounting as lenders prepare for November 2nd’s shift to UAD 3.6 appraisal standards, replacing datasets unchanged since 2010.
The new format includes significantly more data points and dynamic sections, requiring underwriters to completely relearn appraisal workflows and creating higher risk of missed issues if review policies are not updated. Without approved policy exceptions from Fannie Mae and Freddie Mac, new UAD 2.6 submissions will be rejected after the November 2 deadline, making pipeline readiness critical. Lenders and AMCs should prioritize integration testing, staff training, and review policy updates now to avoid investor suspenses and repurchases that could derail fall production closings.
Incoming economic data—specifically Wednesday’s CPI print and Thursday’s PPI report—will be primary catalysts for Treasury direction and mortgage-market stability this week. Persistent price pressures alongside resilient economic activity would reinforce the Federal Reserve’s case for continued restrictive monetary policy, while moderating inflation or weakening demand could support a Treasury rally and provide relief to MBS markets. Strong third-quarter earnings from interest-rate-sensitive sectors like banking could reinforce expectations that the economy can absorb higher borrowing costs, keeping yields elevated and origination profitability under pressure.
Conversely, signs of delayed economic damage from tighter conditions could reverse recent weakness and create a window for mortgage purchase activity to accelerate as affordability headwinds ease temporarily.
**Locking vs Floating**
For pipeline hedgers, the current environment presents two-sided risk: further rate increases could widen mortgage spreads and improve execution for lenders who locked loans, while a Treasury rally could shorten MBS duration and force costly hedge adjustments. Basis volatility remains elevated, with convexity-related selling creating daily swings in MBS prices that make both locking and hedging decisions time-sensitive.
Originators should monitor Fed Funds Futures and upcoming inflation reports closely, as the next policy decision could dramatically shift the risk-reward calculus for floating pipelines versus locked commitments.
**Today’s Events**
September CPI print already released; core came in at 0.335 percent versus 0.2 percent forecast. Remaining week includes September PPI on Thursday, retail sales, initial jobless claims, manufacturing surveys, industrial production data, and the Federal Reserve’s Beige Book.
Market focus is on whether economic momentum can sustain elevated yields or whether growth is weakening enough to support a Treasury recovery.
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |