**WTMS Blog Today = What’s up in Mortgage Today (PM) – 10/14/2026**
Seller advantage hits a 13-year high as buyers hit record lows, with home sellers outnumbering purchasers by a stunning 63% in September according to Redfin data. This marks the fourth straight monthly record for the gap, driven by the lowest buyer count on record at 928,892 while seller inventory climbed to its highest level since March 2020. Only five major metro markets remain seller-favorable, while 41 of 50 tracked metros now favor buyers looking for negotiating power.
Real estate agents and loan originators should understand this shifts the conversation around concessions, price reductions, and rate buydowns with different impacts on borrower cash and monthly payments. Inflation came in hotter than expected Wednesday morning, with September’s consumer prices rising 3.7% year-over-year and core inflation printing at 0.335% versus forecasts of 0.2%. The hotter-than-forecast inflation reading undoes recent dovish Fed commentary and resets rate hike probability expectations back into focus.
Mortgage-backed securities declined sharply on the news, and the 10-year Treasury yield jumped 7 basis points in the immediate aftermath of the CPI release. For mortgage originators, this week’s bond rally lows now serve as a key floor for near-term rate expectations, meaning borrowers sitting on the fence face renewed pressure to lock rather than float. Mortgage origination volumes are sliding into 2027 with the MBA forecasting single-family originations to decline 5% to just under $2 trillion next year.
Purchase originations are expected to tick up 0.8% to $1.42 trillion while refinancing is projected to plummet 17% to $571 billion. The total loan count is expected to drop 5.6% to 5.0 million loans, reflecting both the affordability squeeze and reduced refinancing opportunity as rates remain elevated. This creates a sustained headwind for lenders managing operating costs and staffing in a market that offers fewer revenue opportunities from traditional channels.
The MBA Homebase platform launched Wednesday in partnership with FirstHome IQ, offering loan officers across all lender types NMLS-approved continuing education, monthly coaching, and weekly guidance. The platform targets 5,000 participants by year-end with a longer-term goal of 25,000 and aims to deepen loan officer involvement in housing policy advocacy. Existing-home sales rose 1.5% month-over-month to an annual rate of 3.99 million in September, though inventory remains elevated and median days-on-market stretched to 33 days.
Despite modest monthly gains, August and September marked the two slowest months for home sales this year as rising rates continue to pressure buyer affordability. Mortgage applications fell 2.7% week-over-week as the average 30-year fixed rate climbed to 7.5%, its highest level in nearly three years. Adjustable-rate mortgages now account for 10.5% of applications—the highest share since October 2025—as borrowers seek payment relief on initial periods.
Total applications are down 37.5% year-over-year while refinancing fell 56% and purchase applications dropped 16% compared to last October. Lenders are seeing both declining transaction volumes and a compositional shift toward ARMs, suggesting borrowers are prioritizing short-term payment affordability over long-term rate certainty. VantageScore 4.0 continues expanding across Fannie Mae and Freddie Mac as lenders implement the alternative credit scoring model.
Pennymac has now rolled the model across all three production channels, and while the shift promises broader credit access, questions persist about whether lenders might favor scoring models that produce more favorable borrower results. Sub-700 FICO loans now represent 11.4% of 2026 UMBS 30-year issuance—the highest share since 2023—indicating measurable credit quality migration. Investors and loan servicers will need to monitor whether broader adoption of alternative scores materially changes performance patterns over time.
**Locking vs Floating**
Bonds closed Friday near two-day lows after the CPI surprise, suggesting this week’s rally low now represents a tactical floor for rate movement in the near term. Traders are repositioning for potential Fed rate hike probability to climb back into focus. Borrowers and originators should favor a selective locking posture given both inflation pressure and uncertainty around the Fed’s October meeting.
**Today’s Events**
September Existing Home Sales: 3.99M (actual vs. 3.95M forecast)
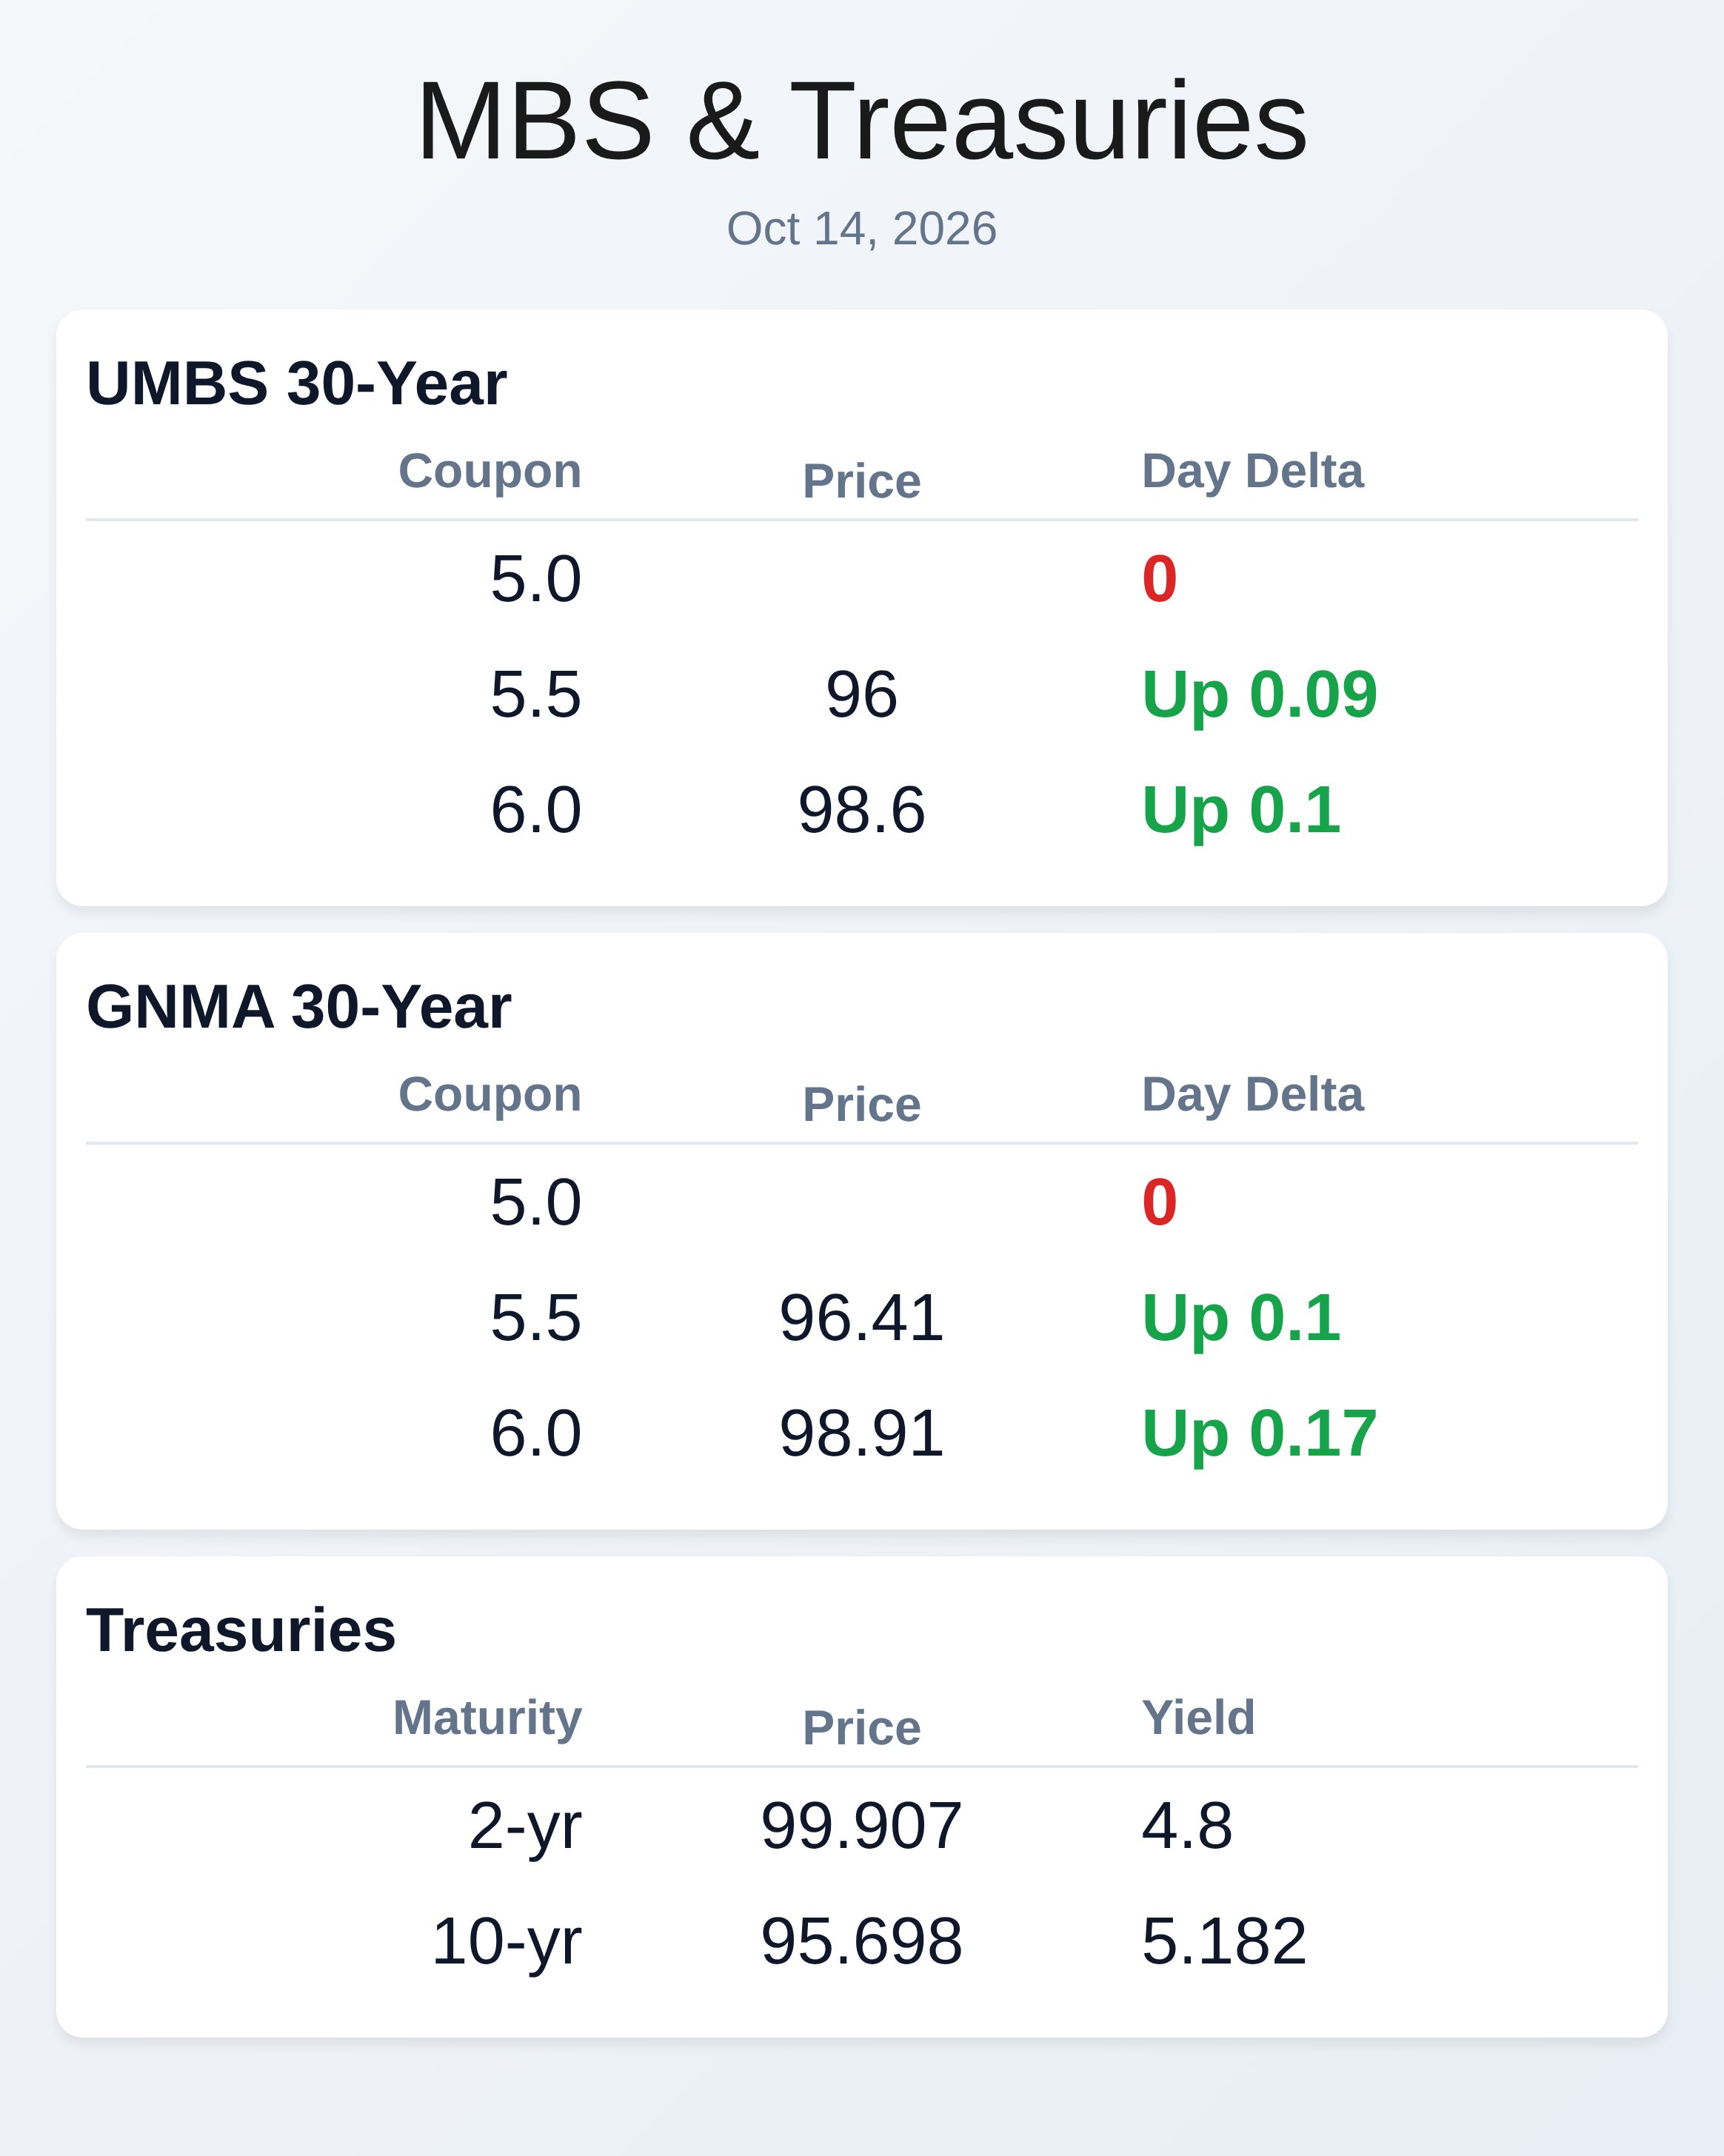
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |