**WTMS Blog Today = What’s up in Mortgage Today (PM) – 09/28/2026**
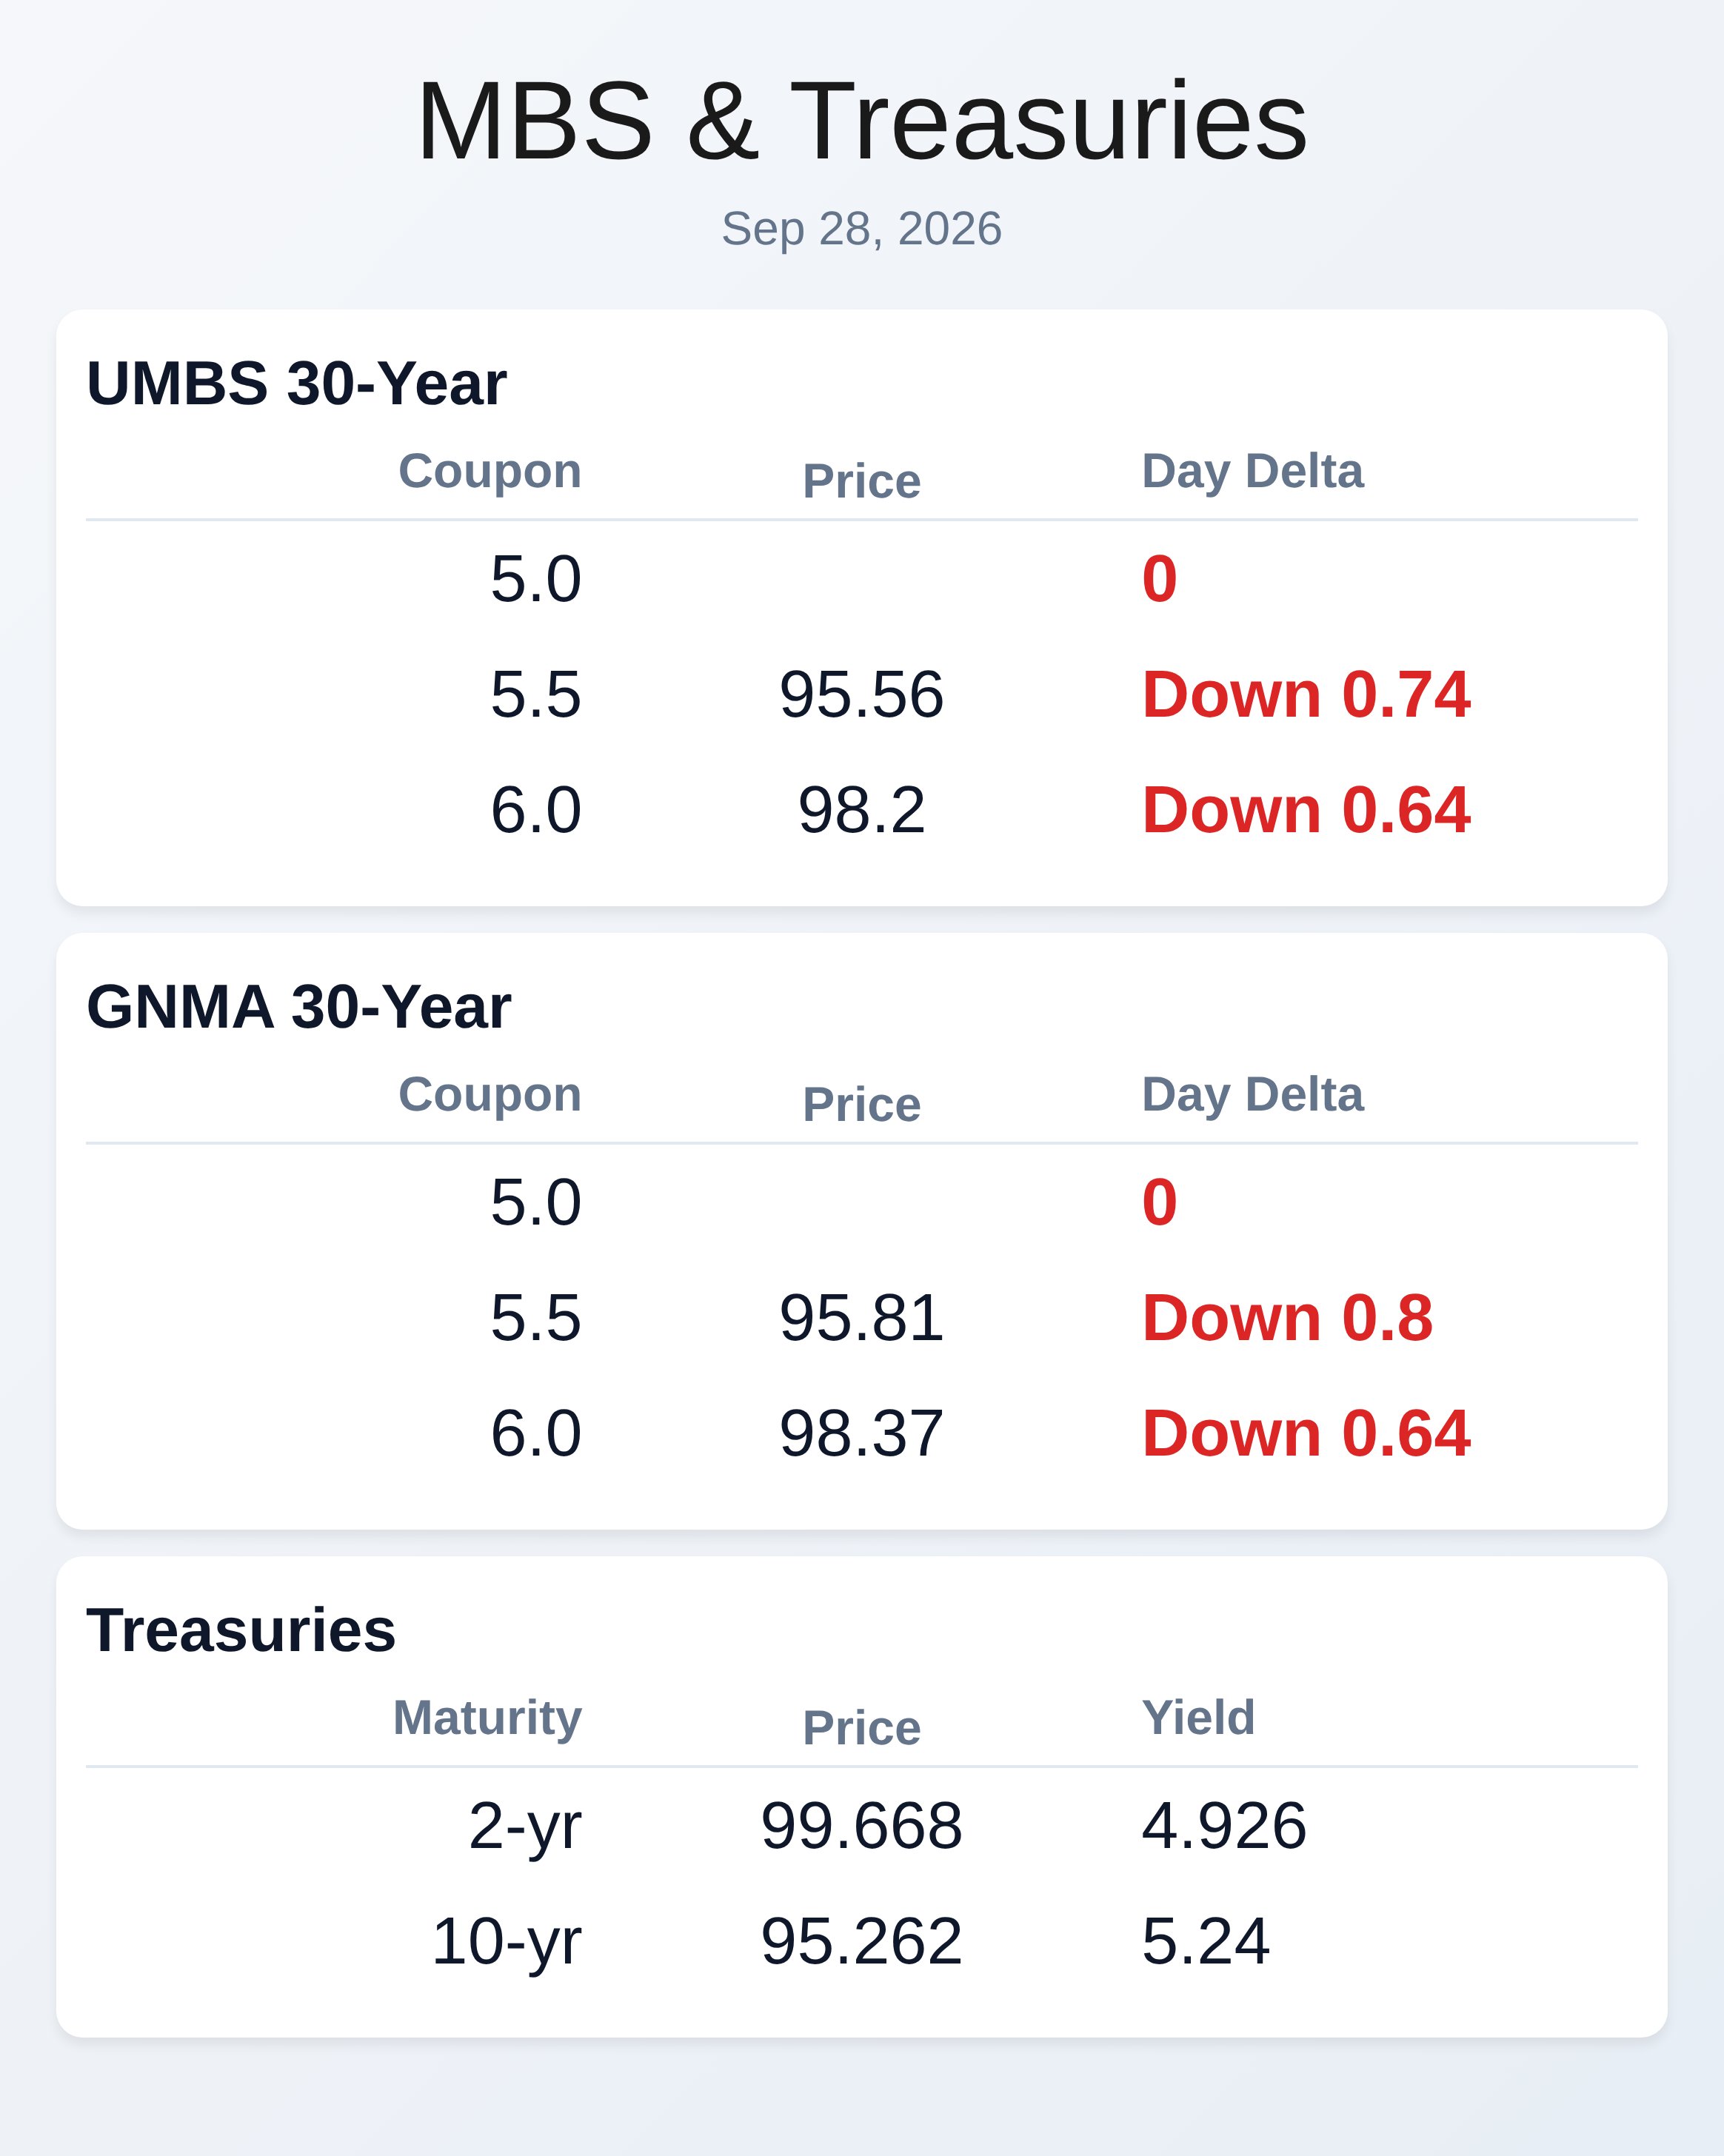
Bond weakness accelerated Monday as Treasury yields jumped to 19-year highs on geopolitical tensions and persistent inflation concerns. The 10-year yield climbed 7.6 basis points to 5.24%, with the benchmark 30-year bond rising to 5.55%, the highest level since 2004. UMBS 6.0 prices dropped 0.64 points while GNMA securities tracked similarly, signaling broader weakness across mortgage-backed securities amid elevated oil prices and concerns about prolonged Middle East conflict.
Major banks are rolling out incentives to compete for borrowers as mortgage activity slows and affordability stretches beyond reach. Chase launched a limited-time rate sale offering up to 25 basis points off through October 4, while Bank of America is offering grants up to $17,500 toward down payments and closing costs. Wells Fargo is rewarding existing customers with rate discounts based on account balances, and Navy Federal introduced a no-refi rate drop program for members with six on-time payments, signaling industry-wide concern about origination volume.
The wholesale channel is contracting as Eleven Mortgage exits its correspondent and wholesale businesses in 60 days, leaving broker loans still in the pipeline. Benchmark Mortgage announced aggressive lock policy changes including a flat 100 basis point extension fee versus the former 2 basis point daily rate. This marks another casualty in a consolidating industry where wholesale platforms continue to wind down operations amid rising capital pressures and reduced profitability in the current rate environment.
UWM is raising at least $400 million through a rights offering as the wholesale giant pushes ahead with broker growth and capital restructuring. Oaktree Capital and the Ishbia family are backstopping the 200 million-share offering, reinforcing investor commitment to the channel’s expansion despite industry headwinds. The move signals confidence in wholesale mortgage banking but comes amid broader market uncertainty and competitive pressures from both retail and correspondent channels.
Mortgage industry practices around producer compensation reveal the “Moneyball problem” of measuring the wrong metrics when evaluating LO value. Volume-based rankings obscure true profitability, as $100 million in production from one originator may generate vastly different economics than the same volume from another depending on required support, pricing concessions, and pull-through rates. Stratmor argues lenders should track contribution dollars at the loan, LO, and branch level to understand actual profitability rather than relying solely on production volume comparisons.
NFM Lending confirmed unauthorized access to customer data after a ransomware group claimed it stole 2.5 terabytes of information including Social Security numbers and financial accounts around September 7. A proposed class action lawsuit was filed September 16 in Maryland federal court, alleging the company failed to notify affected customers in a timely manner. The breach illustrates escalating cybersecurity risks in the mortgage industry and the critical importance of rapid incident response and customer notification protocols.
**Locking vs Floating**
Investors should continue waiting for stronger bond market signals before adjusting lock-and-float strategies. While weak economic data could trigger rate recovery, stronger data will likely push yields higher, adding to recent upward momentum. Until bonds demonstrate genuine rally conviction independent of forced selling, cautious positioning remains prudent given the conflicting technical signals and macro uncertainty.
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
|—:|—:|—:|
| 5.5 | 95.81 | -0.8 |
| 6.0 | 98.37 | -0.64 |
| 6.5 | 100.43 | -0.61 |
**US Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |
|—|—:|—:|—:|
| 2 yr | 4.926 | 99.668 | 0.067 |
| 3 yr | 5.012 | 98.247 | 0.073 |
| 5 yr | 5.072 | 99.688 | 0.079 |
| 7 yr | 5.151 | 99.121 | 0.076 |
| 10 yr | 5.24 | 95.262 | 0.076 |
| 30 yr | 5.549 | 93.833 | 0.06 |
Stay current on mortgage markets and industry strategy—subscribe free at WellThatMakesSense.com.