**WTMS Blog Today = What’s up in Mortgage Today (PM) – 10/08/2026**
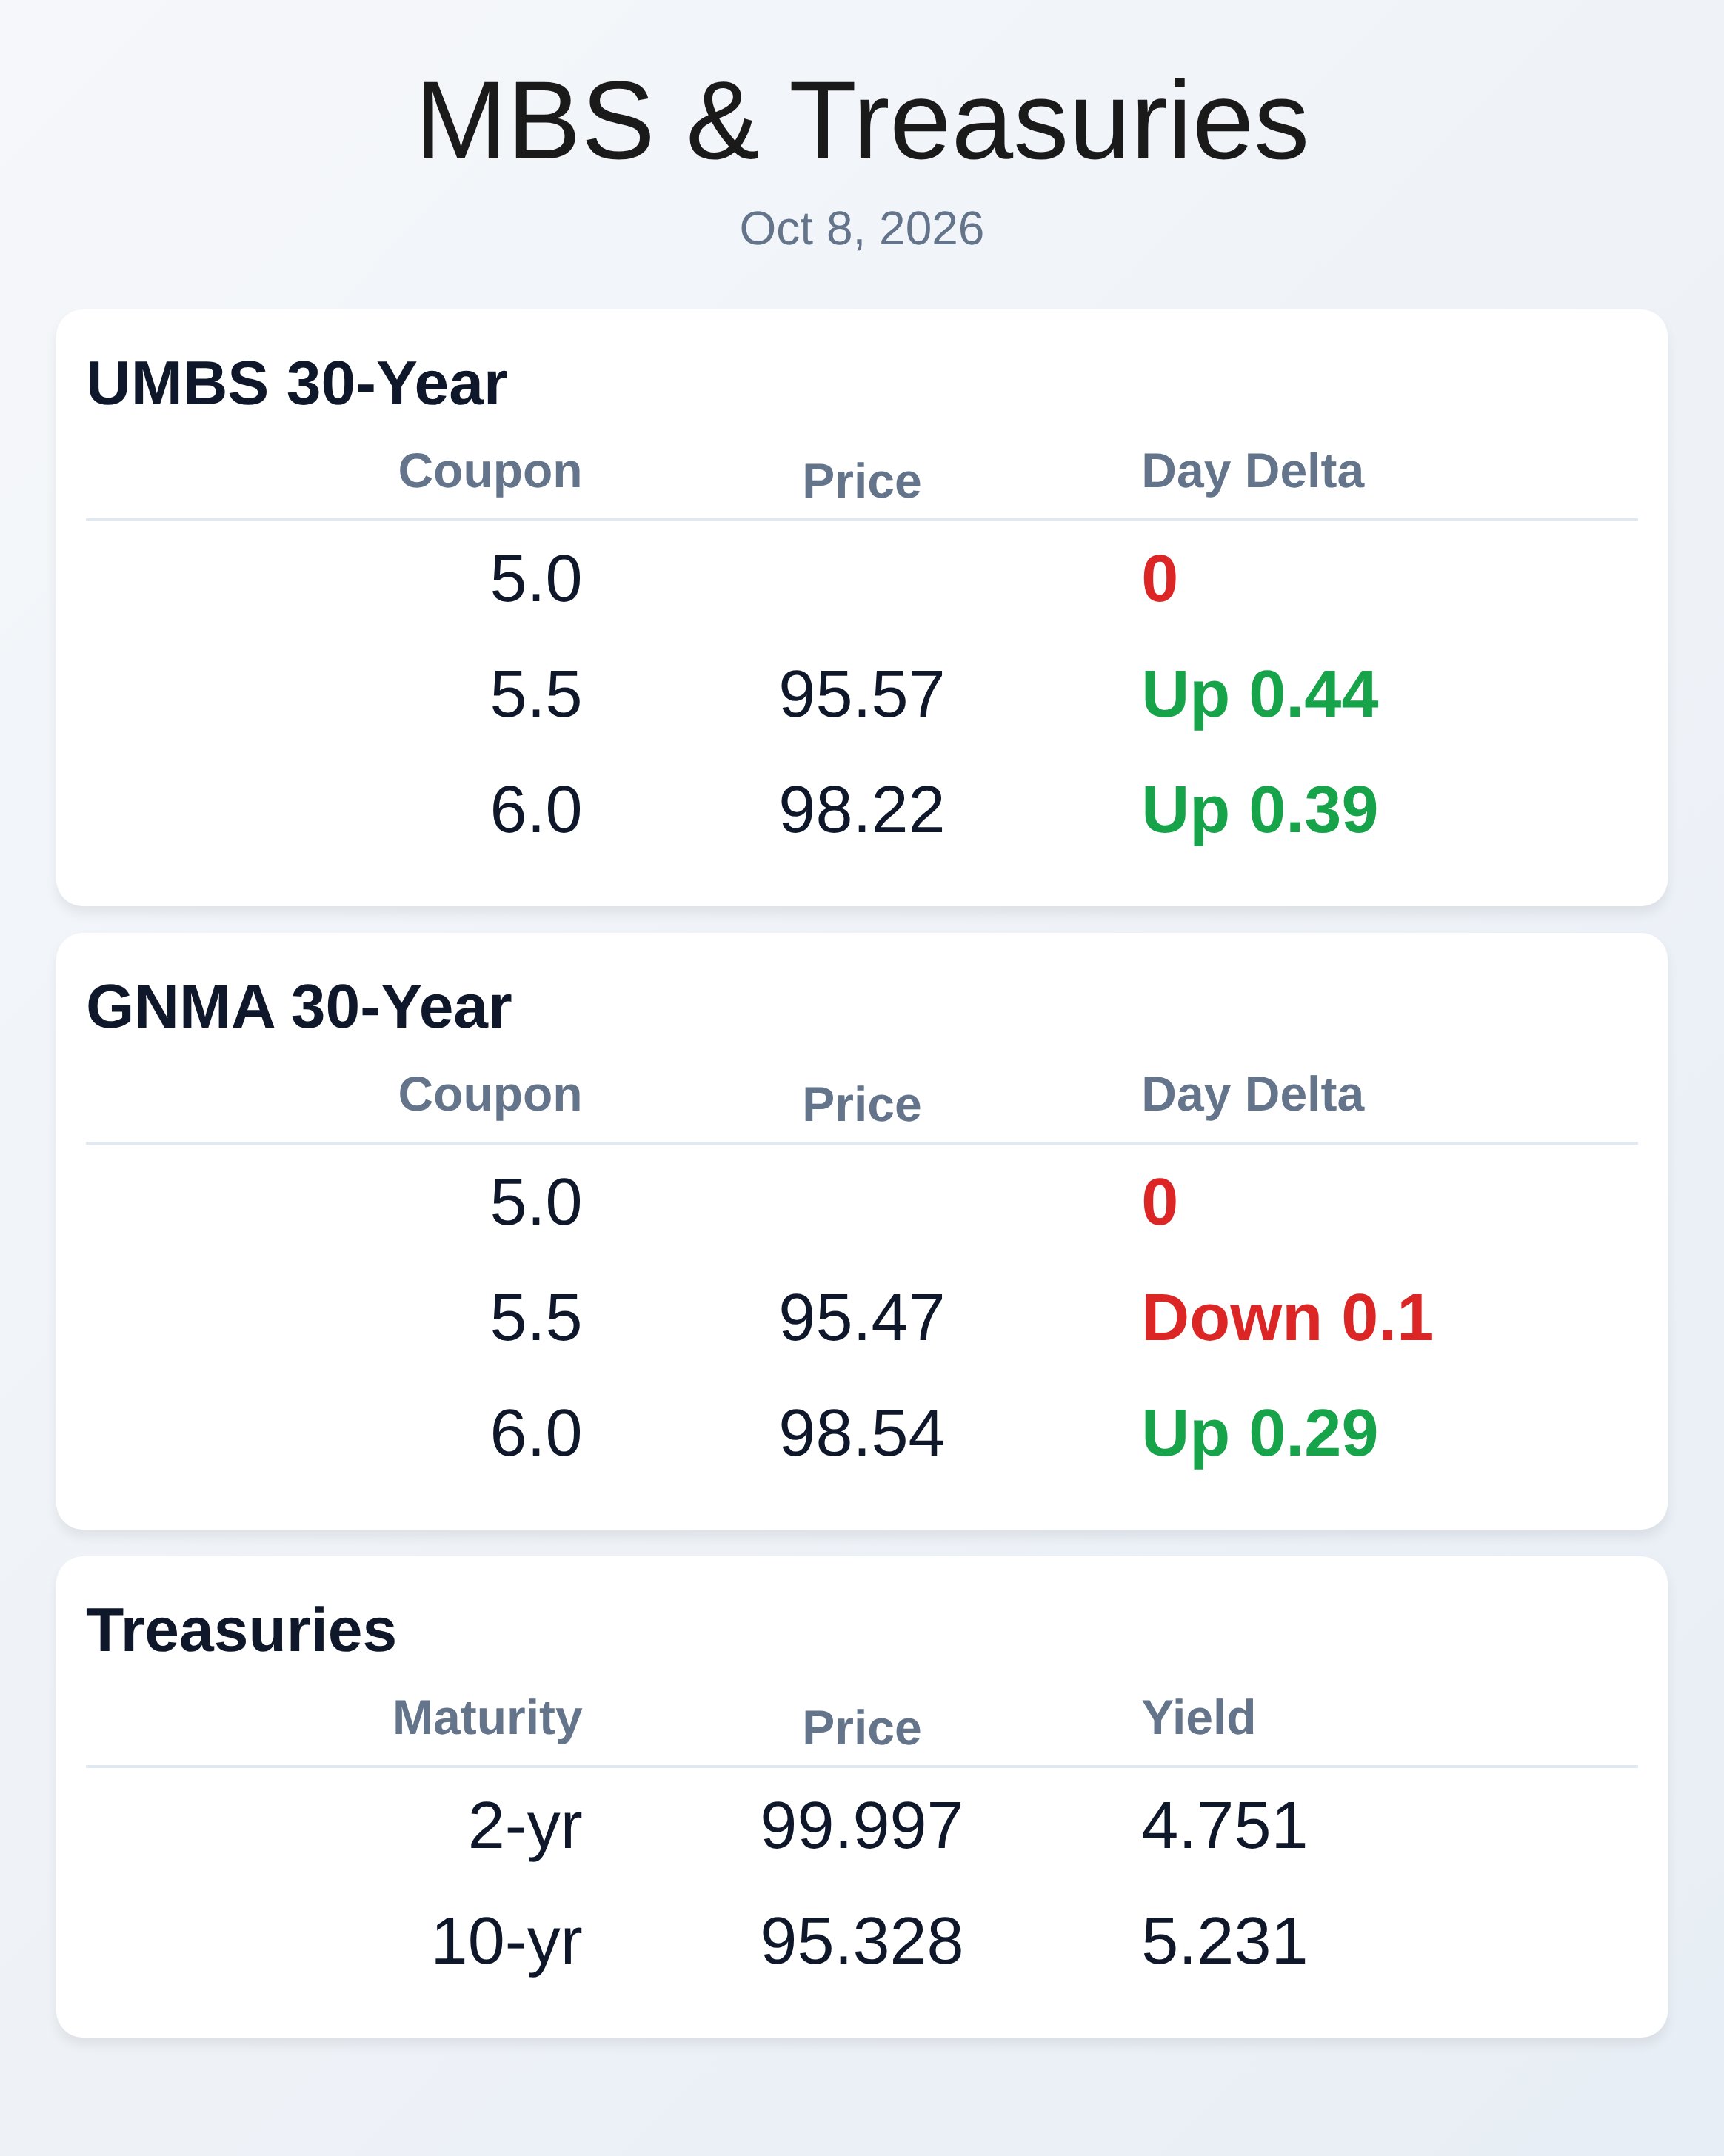
Bonds staged a genuine two-day rally that markets are calling the first real turning point since yields broke above 5.3% earlier this fall. The 10-year Treasury dropped 6.3 basis points to 5.225% by mid-afternoon, with UMBS 6.0 coupons gaining 42 basis points to 98.25. MBS pricing strength and a stronger-than-expected 30-year bond auction provided additional conviction to the move.
Today’s action follows Wednesday’s modest recovery, creating a momentum pattern worth monitoring. However, analysts caution this remains embryonic and needs sustained conviction to confirm a real shift in direction. The rally drew support from war-related headlines and what appears to be classic “buy the dip” behavior at key yield ceilings around 5.33–5.35%.
Investors appear to be testing whether the bond market’s recent selling pressure has finally exhausted itself. Fed funds futures for mid-2027 moved alongside the 10-year yield, suggesting the market is repricing expectations for future rate decisions. Treasury auction results turned surprisingly solid after the rally had already pushed prices higher.
The exact catalysts remain somewhat opaque, leaving traders to construct competing narratives about fundamental drivers. Seven structural headwinds continue to support elevated rates across the curve: geopolitical inflation concerns tied to ongoing conflicts, massive Treasury issuance from fiscal imbalances, heavy corporate bond supply competing for investor demand, resilient equity markets absorbing capital that might otherwise flow to bonds, weakening foreign demand partly driven by tariff uncertainty, genuinely strong economic data, and a Federal Reserve willing to deploy its rate tool aggressively. These factors remain anchored in place regardless of two good trading days.
Without a meaningful shift in one or more of these elements, the rally faces headwinds that could reassert themselves quickly. Morning trading started weak after Fed Vice Chair Chris Waller reiterated that more rate hikes were needed given strong economic growth and persistent inflation concerns. His comments spooked the short end of the curve at 4:30 a.m.
Eastern, pushing Fed funds futures for next year higher and dragging near-term yields with it. Rising oil prices added pressure to the bearish sentiment early on. By mid-morning, however, the tone shifted as bonds recovered almost entirely, closing out the overnight weakness without obvious new catalyst.
The disconnect between morning hawkishness and afternoon strength illustrates how fragile the current sentiment remains. For originators, today’s modest relief should not trigger aggressive locking strategies until the market proves it can hold gains consistently. A sustained break below 5.20% on the 10-year would represent phase one confirmation, but real conviction requires the market to close November below 5.00%.
Historical precedent shows that yield rallies from peaks can run anywhere from 30 basis points over six weeks to extreme examples of 100 basis points in two months, depending entirely on economic shifts. Lock decisions should remain calibrated to client demand rather than the belief a major correction is underway. Lenders holding rate sheets steady through this volatility are positioned safely regardless of which scenario unfolds.
**Locking vs Floating**
Treasury auctions and yield-support levels matter more than intraday price swings when deciding lock positioning. The market appears to be testing whether 5.33–5.35% on the 10-year acts as a hard ceiling for investor demand, and today’s action suggests it may be holding. A confirmed break below 5.20% would signal phase one of a potential correction, though November data and economic conditions will determine whether any rally sticks.
Until the market demonstrates sustained momentum—ideally through month-end—borrowers in no rush should stay floating, while those with committed purchase deadlines should consider locking to protect certainty.
**Today’s Events**
October 8, 2026: Initial Jobless Claims (8:30 a.m. ET) expected at 200K vs.
prior 197K; Continued Claims (8:30 a.m. ET) expected at 1,710K vs. prior 1,701K.
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |