Loading...
HOME2023-01-22T13:43:33-07:00

Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (AM) - 09/18/26 {{catlist}}
September 18, 2026
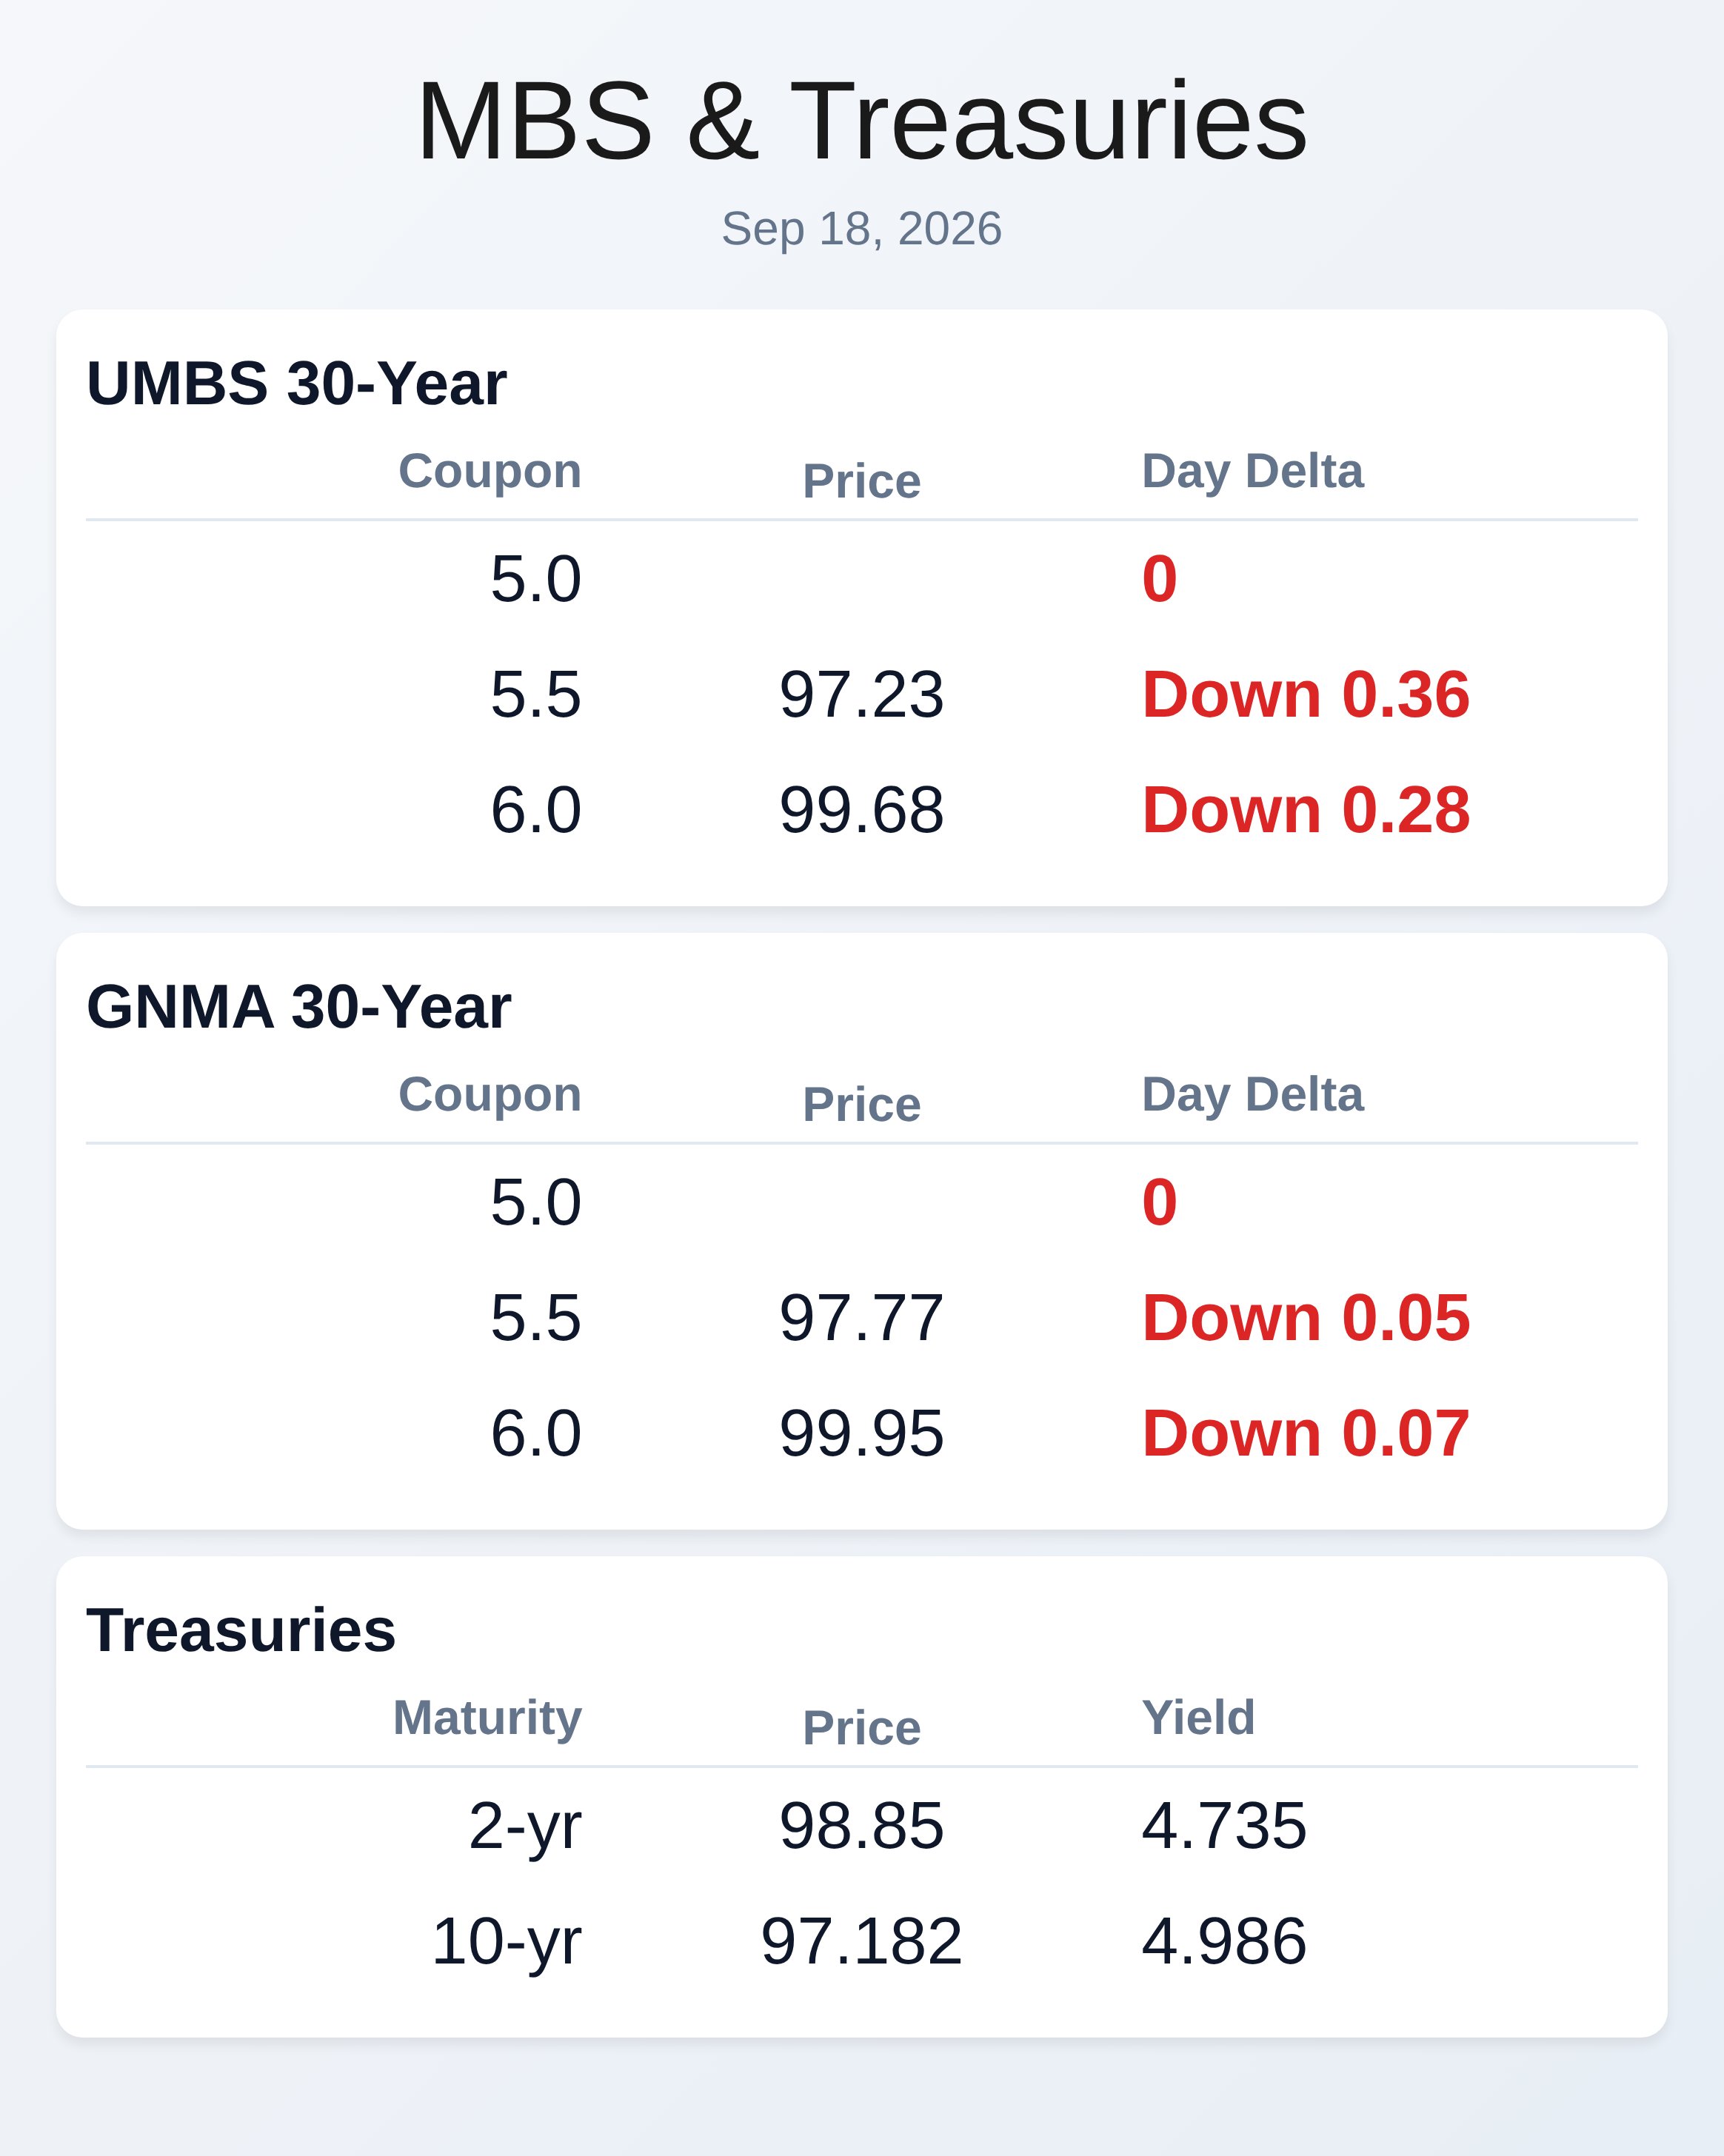
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/18/2026** Bonds are selling off sharply this morning as the 10-year Treasury yield climbs to 4.986%, up 5.3 basis points, signaling renewed investor caution despite Thursday's modest rally. UMBS 30-year coupons are down across the board—5.5s off 0.36, 6.0s down 0.28, and 6.5s sliding 0.20—while GNMA securities show more modest declines. The market is wrestling with competing narratives: the Fed's hawkish 25-basis-point hike on Wednesday reasserted inflation-fighting credibility, but today's weakness suggests investors are already pricing in multiple additional rate increases through 2027. Oil prices remain under pressure, which typically supports bonds but has not reversed this morning's slide. The key technical level to watch is 4.94% on the 10-year; a sustained move below that threshold would signal genuine momentum toward lower rates. Yesterday's economic data painted a decidedly mixed picture that explains the current volatility. Housing starts came in at 1.275 million versus 1.31 million forecast, while building permits printed at 1.394 million against expectations of 1.41 million, both suggesting residential construction is losing steam. Jobless claims crushed estimates at 196,000 versus 208,000 forecast, indicating the labor market remains unusually resilient despite high borrowing costs. The Philadelphia Fed Index held strong at 37.8, but prices paid jumped to 48.60, signaling that inflation pressures are re-emerging even as housing activity cools. This disconnect—weak housing alongside tight labor and price growth—leaves the Fed with limited comfort on rate cuts, making the current yield environment sticky. The mortgage market faces structural headwinds from negative convexity as roughly 98% of 30-year borrowers now lack refinancing incentive. When rates rise, homeowners stay put, forcing MBS investors to hold longer-duration assets just as prices fall—the opposite problem they face during rallies. This convexity drag is particularly acute in higher-coupon 5.5% mortgages, which are experiencing positive convexity as refinancing options vanish entirely. Originators should recognize that MBS are increasingly range-bound rather than trending in either direction, reducing the urgency for extreme positioning either way. The current market environment rewards lender discipline over aggressive directional calls. The conventional conforming market continues to tighten eligibility standards and adjust loan pricing. FHFA Director Bill Pulte directed Fannie Mae to align servicing policies with Freddie Mac, allowing proactive borrower outreach for mortgage insurance cancellation based on current home values—a modest borrower relief measure. Fannie Mae expanded VantageScore 4.0 credit scoring from limited rollout to broad availability, giving approved lenders another underwriting option as the industry modernizes credit frameworks. Fiscal concerns pose a headwind to longer-duration bonds, making a sustained move below 5% in the 30-year difficult without meaningful economic deterioration. With much of 2027's expected tightening already priced in, bond yields may drift lower as investors reassess realistic rate-hike limits, though geopolitical energy pressures and AI-driven demand complicate inflation forecasts. Originators should prepare for range-bound rates and avoid over-extending capacity on the assumption of meaningful rate relief. **Locking vs Floating** Recent economic data shows housing construction losing momentum—starts and permits both missed estimates—while labor markets remain tight and price pressures are re-emerging. This mixed backdrop argues against aggressive floating positions, as the Fed retains hawkish optionality despite softer housing. Borrowers stretched on affordability have less margin for error, making lock discipline especially important to avoid future repurchase risk. **Today's Events** August Building Permits: 1.394M (forecast 1.41M, previous 1.433M) August Housing Starts: 1.275M (forecast 1.31M, previous 1.239M) September 5 Continued Claims: 1.730M (forecast 1.78M, previous 1.774M) September 12 Jobless Claims: 196K (forecast 208K, previous 206K) September Philadelphia Fed Business Index: 37.8 (forecast 30.5, previous 47.4) September Philadelphia Fed Prices Paid: 48.60 (previous 40.90) **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.5 | 97.23 | -0.36 | | 6.0 | 99.68 | -0.28 | | 5.5 | 97.77 | -0.05 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | Market Data
Mortgage Today (PM) - 09/17/26 {{catlist}}
September 17, 2026
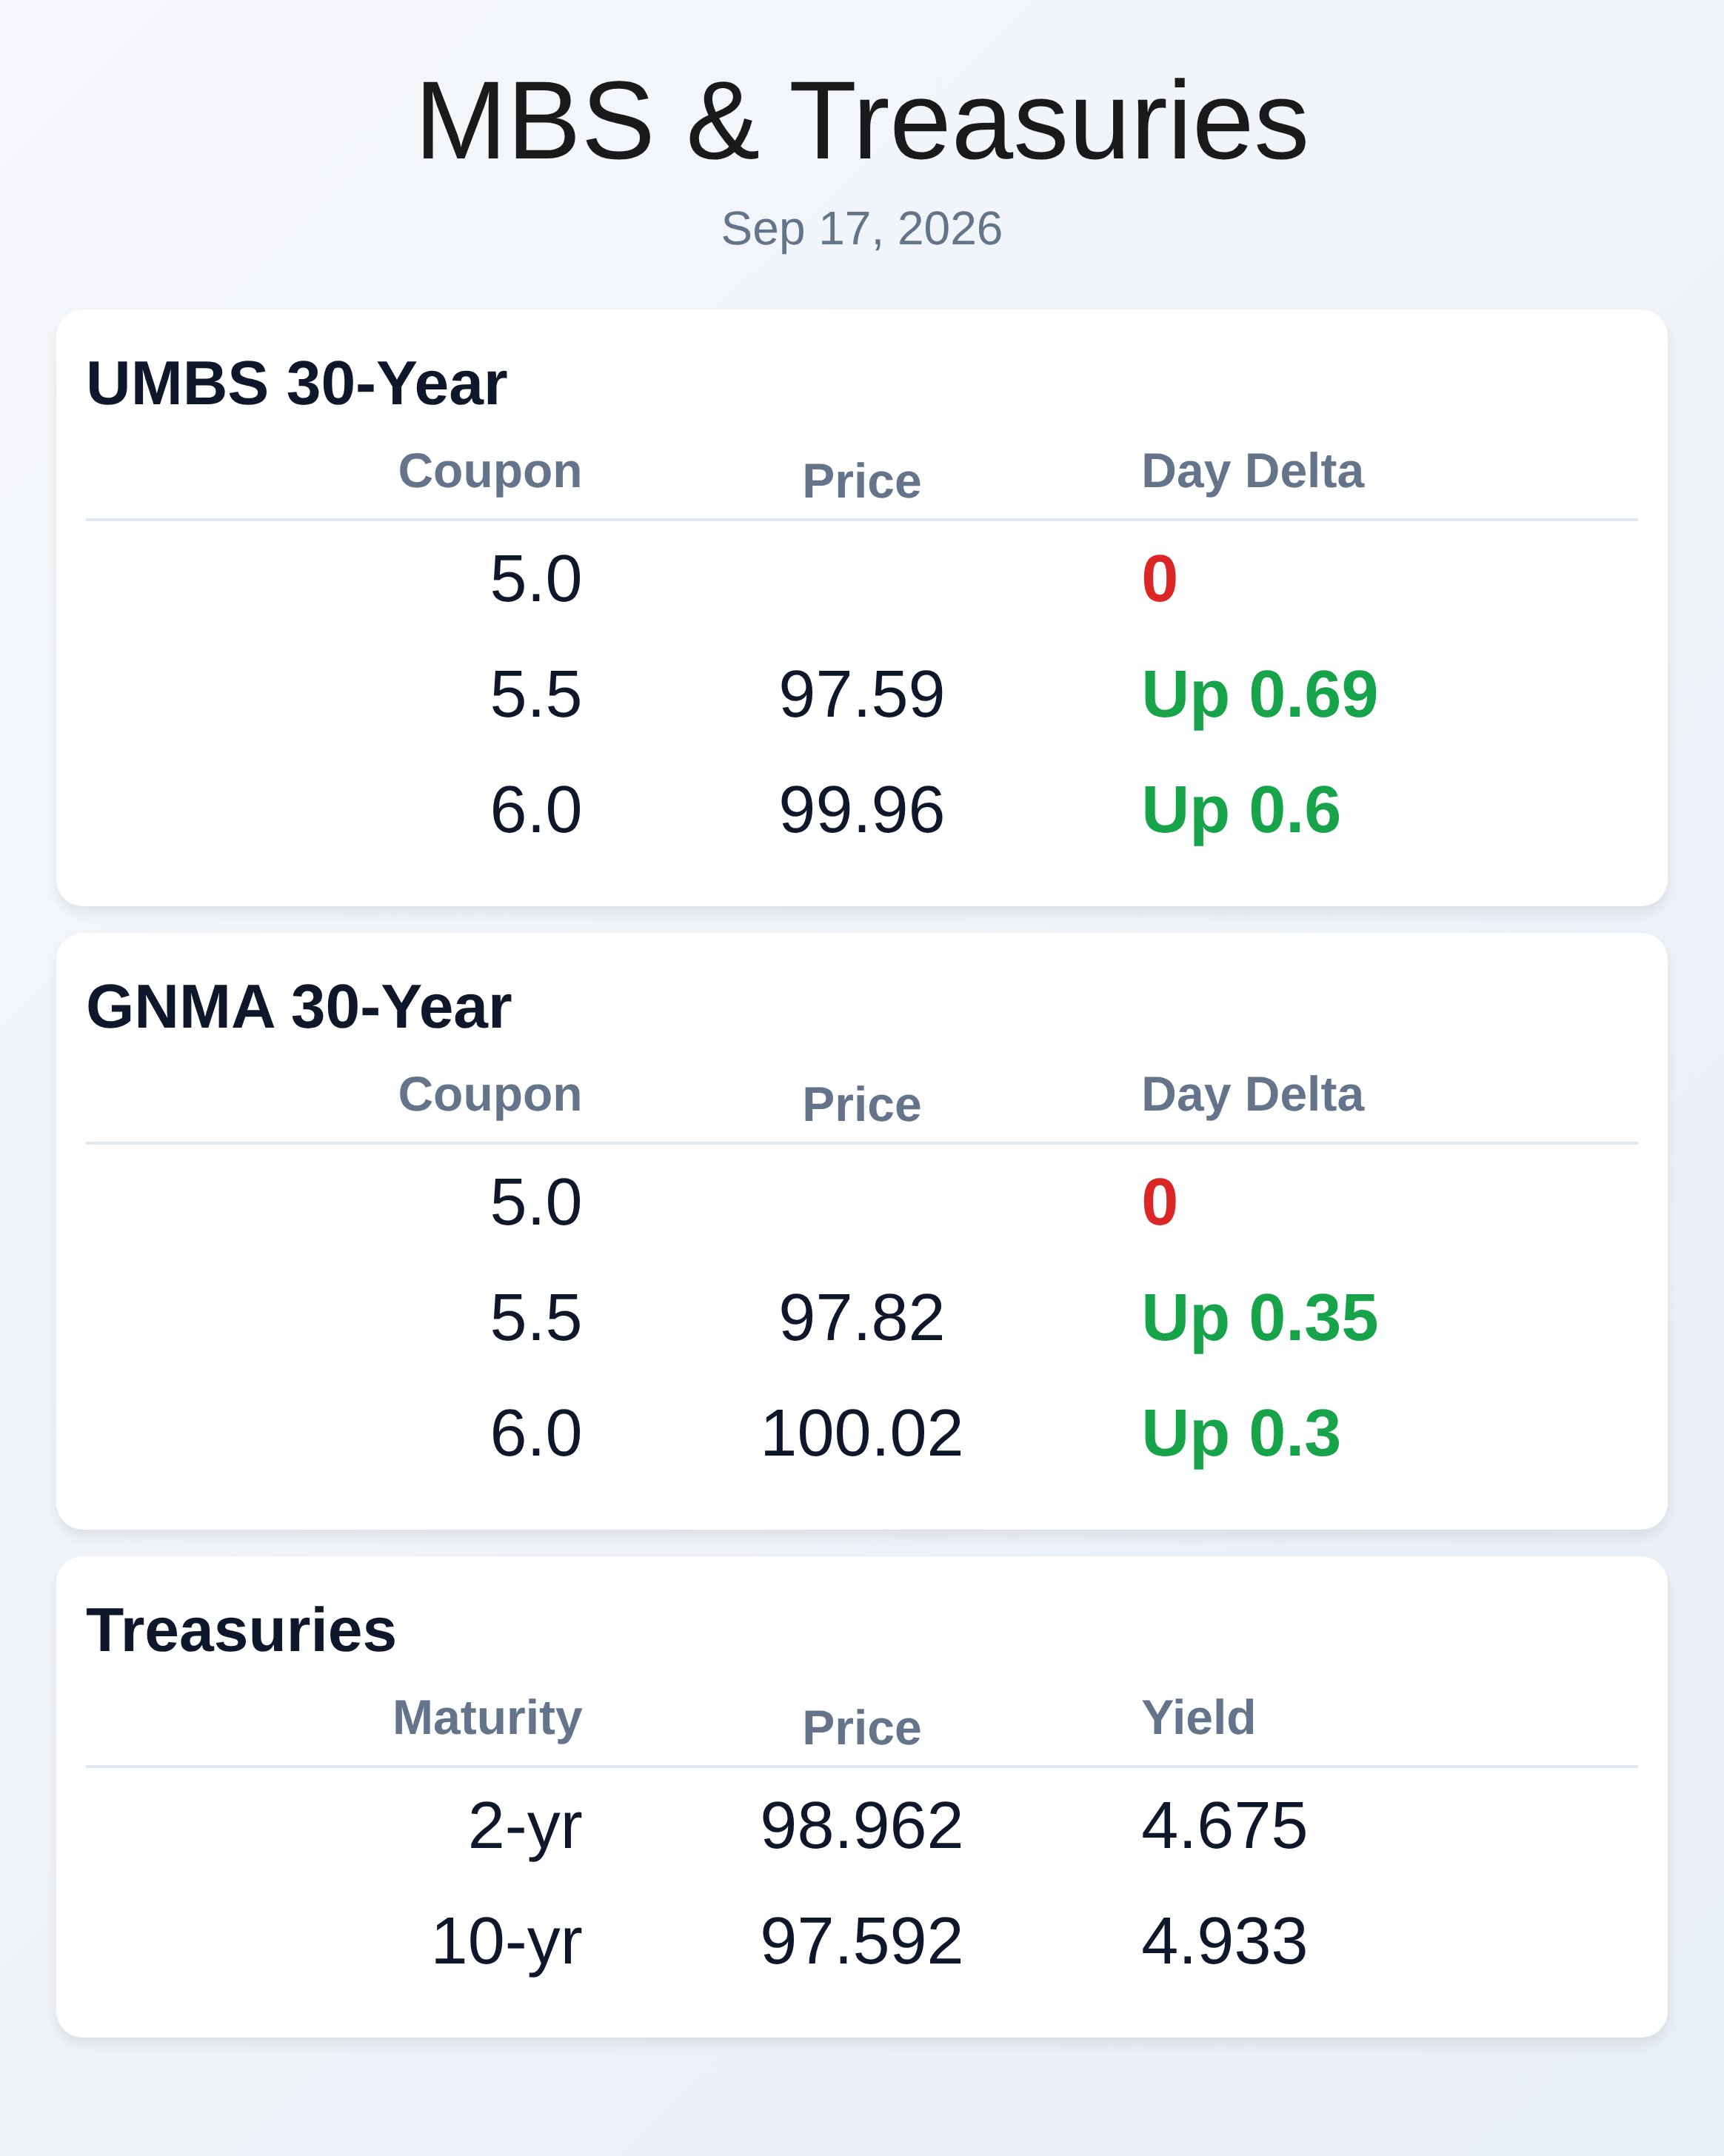
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 09/17/2026** Mortgage rates caught a reprieve today as Treasury yields retreated following the Federal Reserve's widely anticipated rate hike, with the 10-year yield sliding 8.5 basis points to settle near 4.93%. UMBS securities gained significant ground throughout the session, with the 5.5 coupon jumping 69 basis points to 97.59 and the 6.0 coupon rising 60 ticks to 99.96. The bond market's positive reception suggests investors believe the Fed's tightening cycle may be nearing its end, though officials signaled additional rate increases could still be on the table if inflation persists. Economic data painted a mixed picture, with jobless claims coming in better than expected at 196K versus 208K forecast, while building permits and housing starts both lagged forecasts. The market's challenge now revolves around whether this modest rally represents a true shift in momentum or merely profit-taking before the Fed's next move. The disconnect between Fed policy and mortgage rates remains a critical lesson for originators to communicate. While the Fed's rate hike will push HELOC costs higher immediately—since those products typically track the prime rate—mortgage rates hardly budged because they forward-price Treasury expectations and long-term inflation outlooks. This fundamental difference allows loan officers to educate borrowers that a Fed hike does not automatically translate into higher mortgage rates, especially when Treasury yields are moving lower simultaneously. Homebuyers fixated on Fed announcements often miss the more relevant driver: 10-year Treasury yields. Understanding this relationship helps originators cut through market noise and position themselves as credible advisors during volatile rate environments. The Philly Fed Business Index surged to 37.8 from the prior 47.4 reading, falling short of the 30.5 forecast and signaling cooling manufacturing activity. Continued jobless claims dropped to 1.73 million from 1.774 million previously, suggesting labor market resilience despite tightening monetary policy. Building permits slipped to 1.394 million versus a 1.41 million forecast, while housing starts fell to 1.275 million compared to expectations of 1.31 million. Prices paid in the Philly region jumped to 48.6, marking persistent inflationary pressures even as economic growth moderates. These crosscurrents reinforce the volatility mortgage originators face: softening activity paired with sticky inflation creates an uncertain outlook for rate direction and borrower demand. The critical technical level to watch remains the 4.94% threshold on 10-year yields, which serves as both a floor for optimistic traders and a ceiling for risk-averse investors. Breaking below this level cleanly would signal a meaningful shift toward lower rates, though energy prices remain a wildcard that could undermine sustained improvement. By day's end, UMBS 6.5 coupons notched a 54-basis-point gain to 102.08, providing some relief for lenders holding in-the-money servicing portfolios. GNMA securities lagged slightly, with the 6.5 coupon up just 4 basis points to 101.77, likely reflecting different prepayment assumptions. Treasury curve steepening—particularly the 2-year to 10-year spread—adds complexity for hedging strategies and lock management. Originators should recognize that today's rally occurred on tighter credit spreads and improving risk sentiment, not on weakness in economic fundamentals. The fact that mortgage rates held firm near 7% despite the Fed's hike demonstrates the secondary market's confidence in a pause cycle, but that conviction could evaporate if inflation data surprises to the upside. Lock strategies should remain disciplined; borrowers closing within 30 to 45 days face genuine rate risk if Treasury yields retest higher levels. Float positions benefit from the current softness, but the risk-reward profile deteriorates quickly once we move past September's data calendar. Loan officers must balance optimism about today's moves with realistic hedging around next week's economic releases. Subscribe free to WTMS Blog Today at WellThatMakesSense.com to stay ahead of mortgage market shifts and origination insights. **Locking vs Floating** The market's narrative shifted today: the Fed's rate hike did not automatically derail mortgage rates because those products are driven by Treasury yields and inflation expectations, not Fed policy directly. Jobless claims beating forecasts reinforced the view that one more rate hike may already be priced in, removing some urgency around aggressive Fed tightening. The 4.94% ceiling on 10-year yields represents a psychological and technical pivot point—breaking below it cleanly would favor floaters and increase confidence in lower future rates. Conversely, if yields retest higher after better-than-expected data next week, locks become increasingly attractive relative to floating risk. **Today's Events** Building Permits (Aug): 1.394M vs 1.41M forecast, 1.433M previous Housing Starts (Aug): 1.275M vs 1.31M forecast, 1.239M previous Jobless Claims (Sep/12): 196K vs 208K forecast, 206K previous Continued Claims (Sep/05): 1.73M vs 1.78M forecast, 1.774M previous Philly Fed Business Index (Sep): 37.8 vs 30.5 forecast, 47.4 previous Philly Fed Prices Paid (Sep): 48.60 vs forecast not available, 40.90 previous **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | **GNMA 30yr** | Coupon | Price | Intra-Day Change | |---:|---:|---:| | 5.5 | 97.82 | 0.35 | | 6.0 | 100.02 | 0.3 | | 6.5 | 101.77 | 0.04 | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | |---|---:|---:|---:| | 2yr | 4.675 | 98.962 | -0.059 | | 3yr | 4.742 | 98.984 | -0.078 | | 5yr | 4.787 | 98.185 | -0.087 | | 7yr | 4.858 | 97.9 | -0.088 | | 10yr | 4.933 | 97.592 | -0.086 | | 30yr | 5.289 | 97.548 | -0.07 | Market Data
Mortgage Today (AM) - 09/17/26 {{catlist}}
September 17, 2026
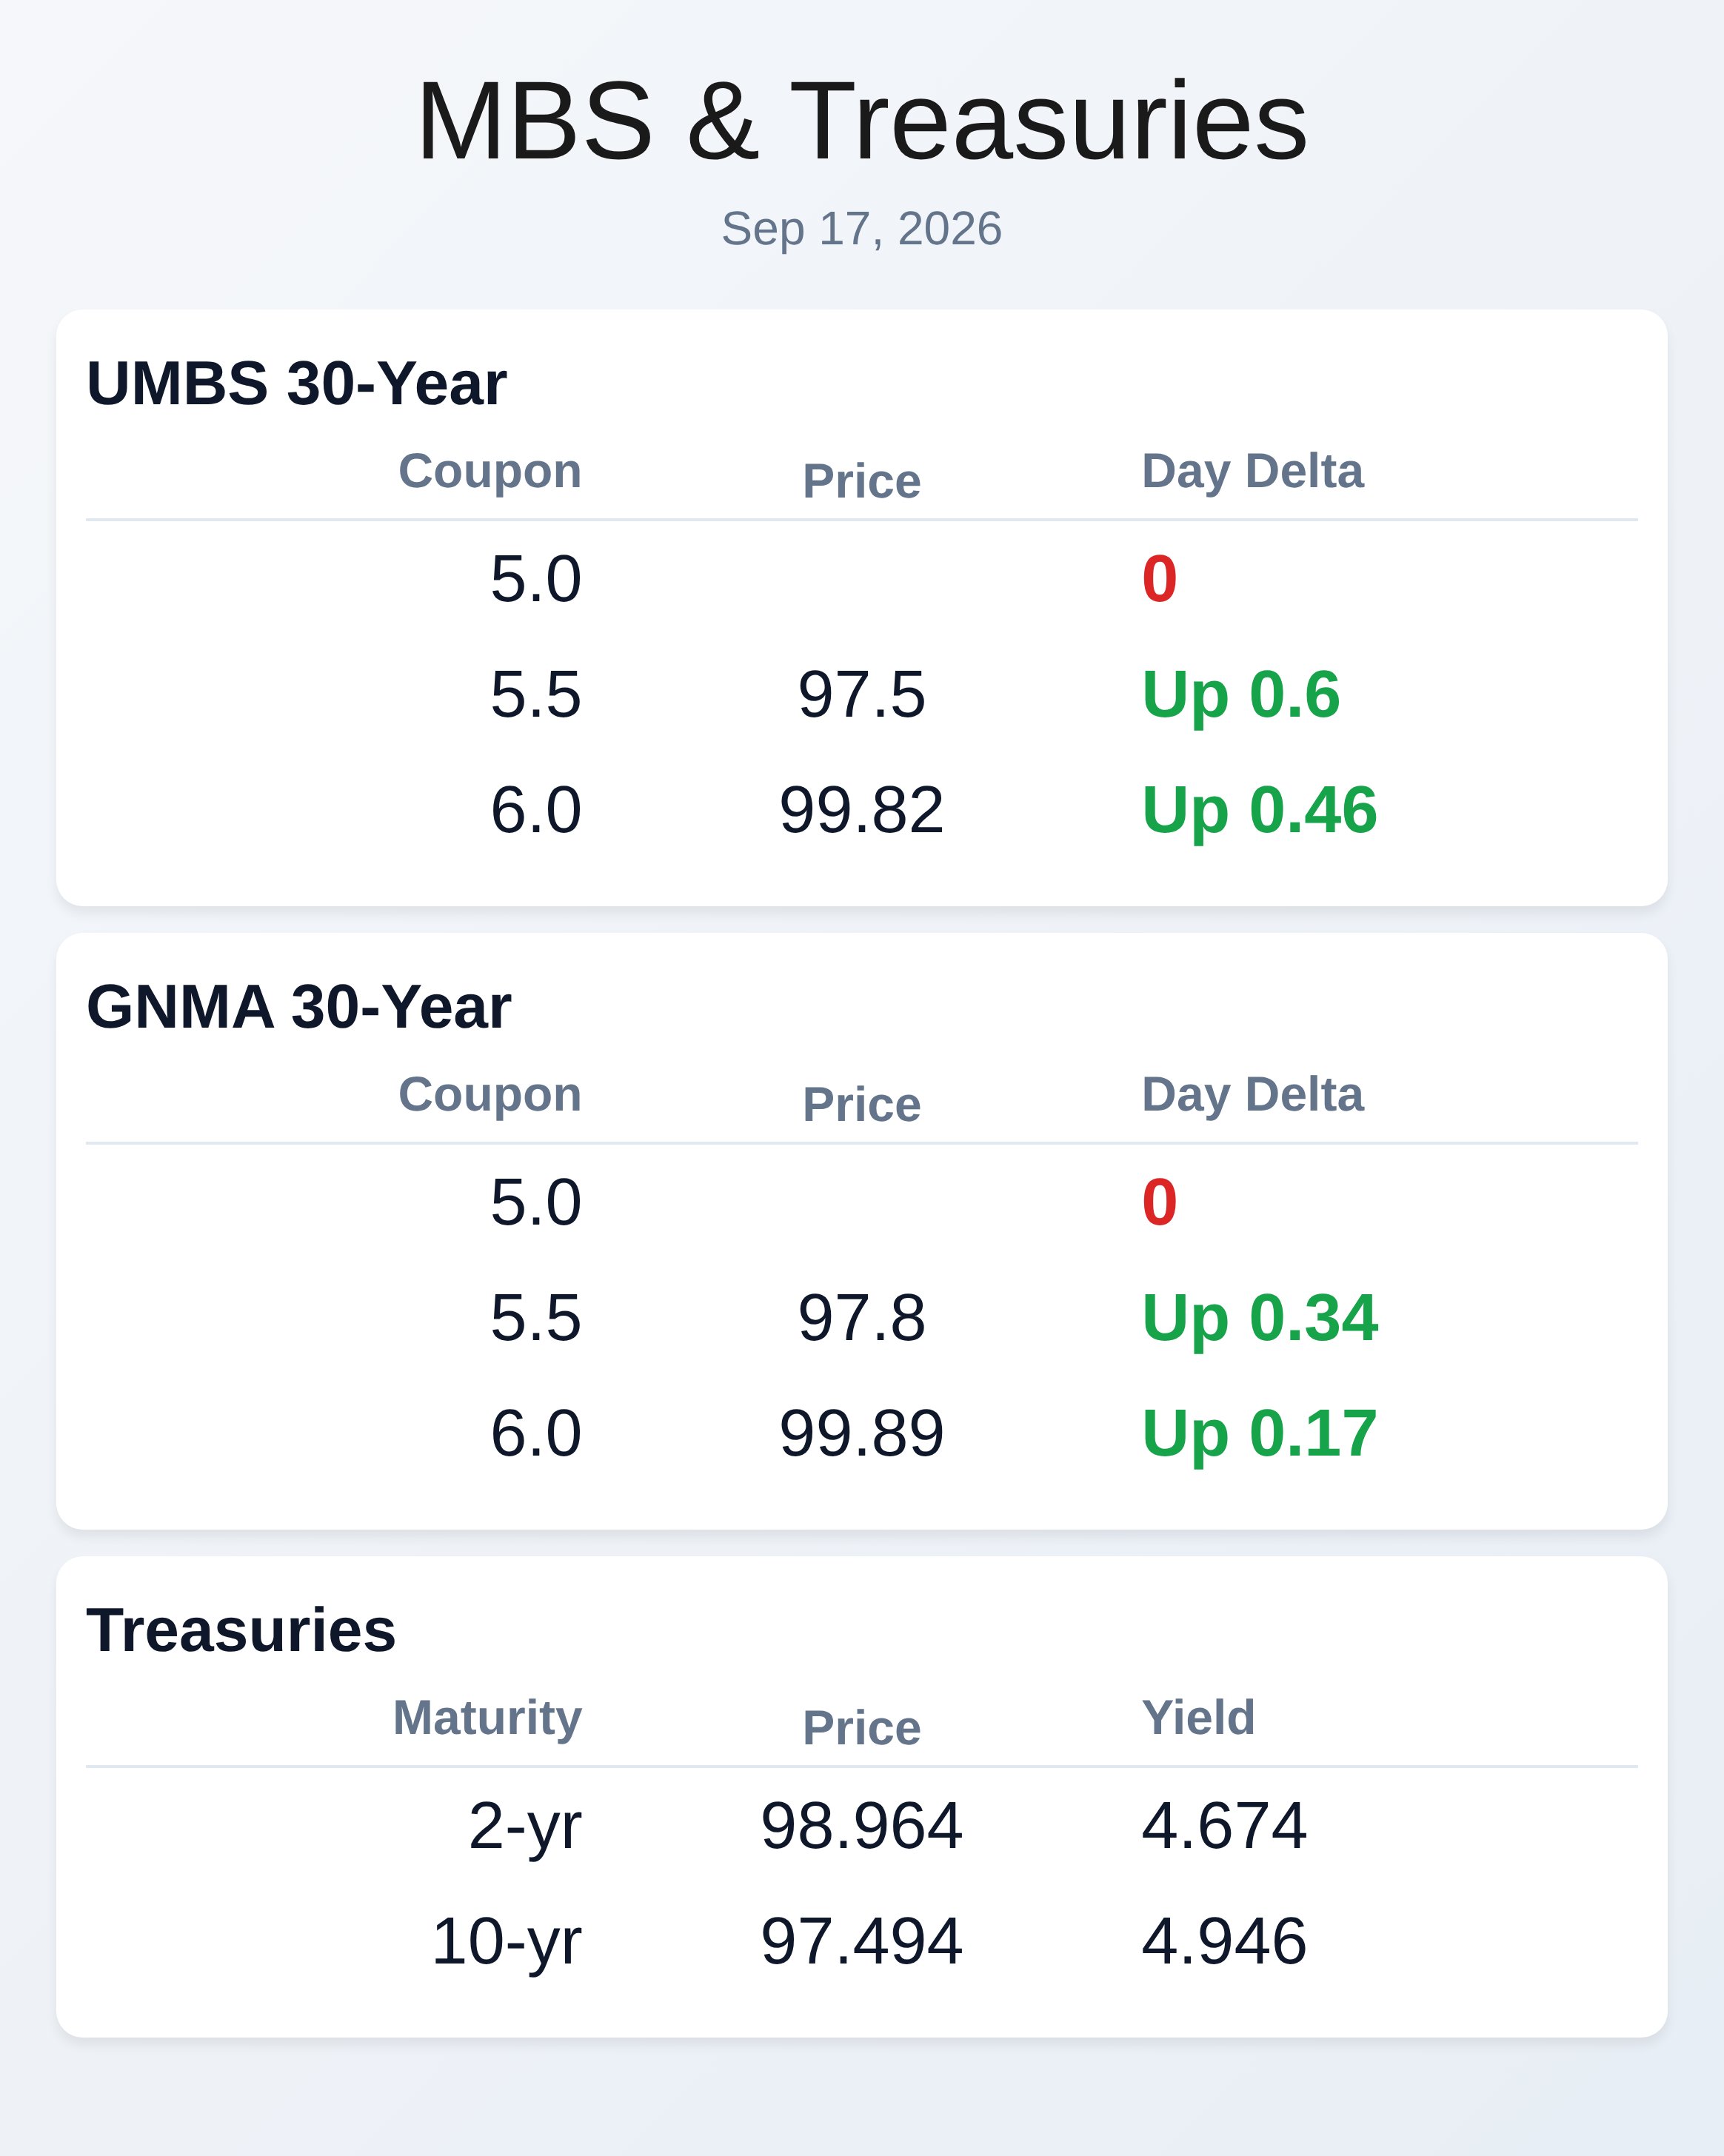
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/17/2026** The Federal Reserve's quarter-point rate hike to 4.00 percent sent mixed signals through bond markets yesterday, with Treasury yields rallying back this morning even as policymakers signaled more tightening ahead. Agency MBS prices rebounded modestly overnight, with UMBS 6.0s holding at 99.82, suggesting some stabilization after the initial volatility. The hawkish tone from Fed policymakers—16 of 18 officials now see at least one more hike in 2026—continues to create uncertainty for lenders trying to lock or float rate locks. Jobless claims came in stronger than expected at 196,000 versus forecasts of 207,000, adding to the mixed economic picture. The 10-year Treasury yield opened this morning at 4.97 percent, down nearly 5 basis points from yesterday's close at 5.01 percent. The week's economic data painted a picture of an economy resilient on employment but fragile on housing. August housing starts fell short at 1.275 million versus expectations of 1.31 million, marking continued weakness in new construction. Building permits also disappointed at 1.394 million, though continuing claims declined to 1.730 million from 1.774 million the prior week. The Philly Fed Business Index dropped to 37.8 from 47.4, signaling a noticeable pullback in regional manufacturing sentiment. These crosscurrents leave originators navigating an environment where robust labor markets contrast sharply with deteriorating housing demand. GNMA 30-year securities showed less volatility than UMBS in overnight trading, with the 6.0 coupon priced at 99.89 after gaining just 17 basis points intraday. The 6.5 coupon held at 102.03, suggesting investors are rotating into higher coupons as rate expectations stabilize. GNMA's more stable performance reflects the government guarantee and continued demand from portfolio managers seeking yield in a higher-for-longer rate environment. Treasury curve positioning shows the 2-year yielding 4.67 percent and the 30-year at 5.30 percent, indicating markets are pricing in eventual rate cuts but not expecting them anytime soon. The spread dynamics between shorter and longer maturities remain the key lens for tracking duration bets across fixed-income desks. Originators face a critical decision point as secondary desks have already repriced locks following the Fed's move. Some lenders held back repricing yesterday afternoon, likely setting themselves up for adjustments this morning, which increases float risk for brokers still holding paper. The consensus among trading desks is cautious: higher Fed funds rates should ultimately help mortgage rates by fighting inflation, but the near-term noise from Fed decisions makes it impossible to confirm that benefit immediately. Floating on lenders who haven't repriced introduces execution risk, while those who repriced for the worse still leave room for tactical positioning before a clear trend emerges. The defensive strategy of waiting for momentum confirmation remains the prudent choice given the elevated uncertainty in rate direction. Mortgage application data from the Mortgage Bankers Association revealed that builder applications for new home purchases fell 5.5 percent year-over-year and declined 6 percent month-over-month in August. This marks the fifth consecutive month of declining applications and represents 2026's lowest monthly total for new construction purchases. Retail sales proved stronger than anticipated at 1.2 percent month-over-month, with core sales up 1.4 percent, showing consumers remain willing to spend even at elevated borrowing costs. The tension between consumer spending power and housing affordability continues to define market dynamics as mortgage rates remain elevated despite yesterday's Treasury rally. The Fed's updated projections now show a median year-end fed funds rate of 4.125 percent, implying one to two additional rate moves before year-end depending on inflation data. Treasury yields have stabilized this morning after moving lower on expectations that the aggressive tightening cycle may finally be plateauing, though any signs of sticky inflation could trigger another leg higher. Oil prices fell 2.5 percent overnight to $99.90 per barrel, easing some of the near-term inflation concerns that had pushed yields to multi-decade highs. The combination of cooling commodity prices, resilient labor markets, and weaker housing activity creates a complex backdrop where mortgage originators must balance rate lock strategy with pipeline management. Markets will closely watch the October and December Fed meetings and any revisions to the neutral rate before committing to a clear directional view on 2027 rates. **Locking vs Floating** Yesterday's Fed hike created an extremely difficult environment for lock-versus-float decisions. Several lenders did not reprice yesterday afternoon, meaning brokers holding loans with those lenders face repricing risk this morning when the lender adjusts. Floating strategy works best when lenders who repriced for worse leave room for positive adjustments, but even then the prudent approach is to wait for clear momentum before abandoning defensive positioning. Treasury support has returned near yesterday's levels, confirming some stability, but the bigger picture question remains unanswered: will higher Fed funds rates ultimately help or hurt mortgage rates? The safest path is to hold defensive floats while monitoring for a strong directional shift rather than trying to catch tops or bottoms during Fed weeks. **Today's Events** Building Permits (Aug): 1.394M vs 1.41M forecast, 1.433M prior Continued Claims (Sep/05): 1.730M vs 1.780K forecast, 1.774K prior Housing Starts (Aug): 1.275M vs 1.31M forecast, 1.239M prior Jobless Claims (Sep/12): 196K vs 208K forecast, 206K prior Philly Fed Business Index (Sep): 37.8 vs 30.5 forecast, 47.4 prior Philly Fed Prices Paid (Sep): 48.60 vs no forecast, 40.90 prior **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.5 | 97.5 | 0.6 | | 6.0 | 99.82 | 0.46 | | 5.5 | 97.8 | 0.34 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2 yr | 4.674 | 98.964 | -0.06 | | 3 yr | 4.745 | 98.976 | -0.08 | | 5 yr | 4.791 | 98.17 | -0.089 | | 7 yr | 4.863 | 97.869 | -0.088 | | 10 yr | 4.946 | 97.494 | -0.073 | | 30 yr | 5.304 | 97.323 | -0.059 | Market Data
LATEST ARTICLES

RECENT ARTICLES

Article Archive

What’s up in Mortgage Today – 8.16.23

August 16th, 2023|0 Comments

MBS have opened up 13 bps on the morning. Stocks in the green, being up 7 points. Russia's central bank raised interest rates from 8.5% to 12% at an emergency meeting yesterday, the [...]

What’s up in Mortgage Today – 8.15.23

August 15th, 2023|0 Comments

MBS up 5 bps on the morning. At least it's green!! Stocks in the red, down 31 points Bonds were already modestly weaker in the overnight session but started losing more ground after [...]

Mortgage Mastery Mashup Training

August 15th, 2023|0 Comments

Mortgage Mastery Mashup Sales Training!!!! Welcome to the WellThatMakesSense Mortgage Mastery MashUp sales training!!! I'm a nerd, so I consume a lot of great content.  And, I love sharing it with [...]

What’s up in Mortgage Today – 8.11.23

August 11th, 2023|0 Comments

MBS taking a hit early. Down a quarter point in early trading. Stocks down about 9 points. Bonds were almost perfectly flat in the overnight session as traders scratched their heads trying to [...]

Subscribe

Send me some brain food

Go to Top