Loading...
HOME2023-01-22T13:43:33-07:00

“Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

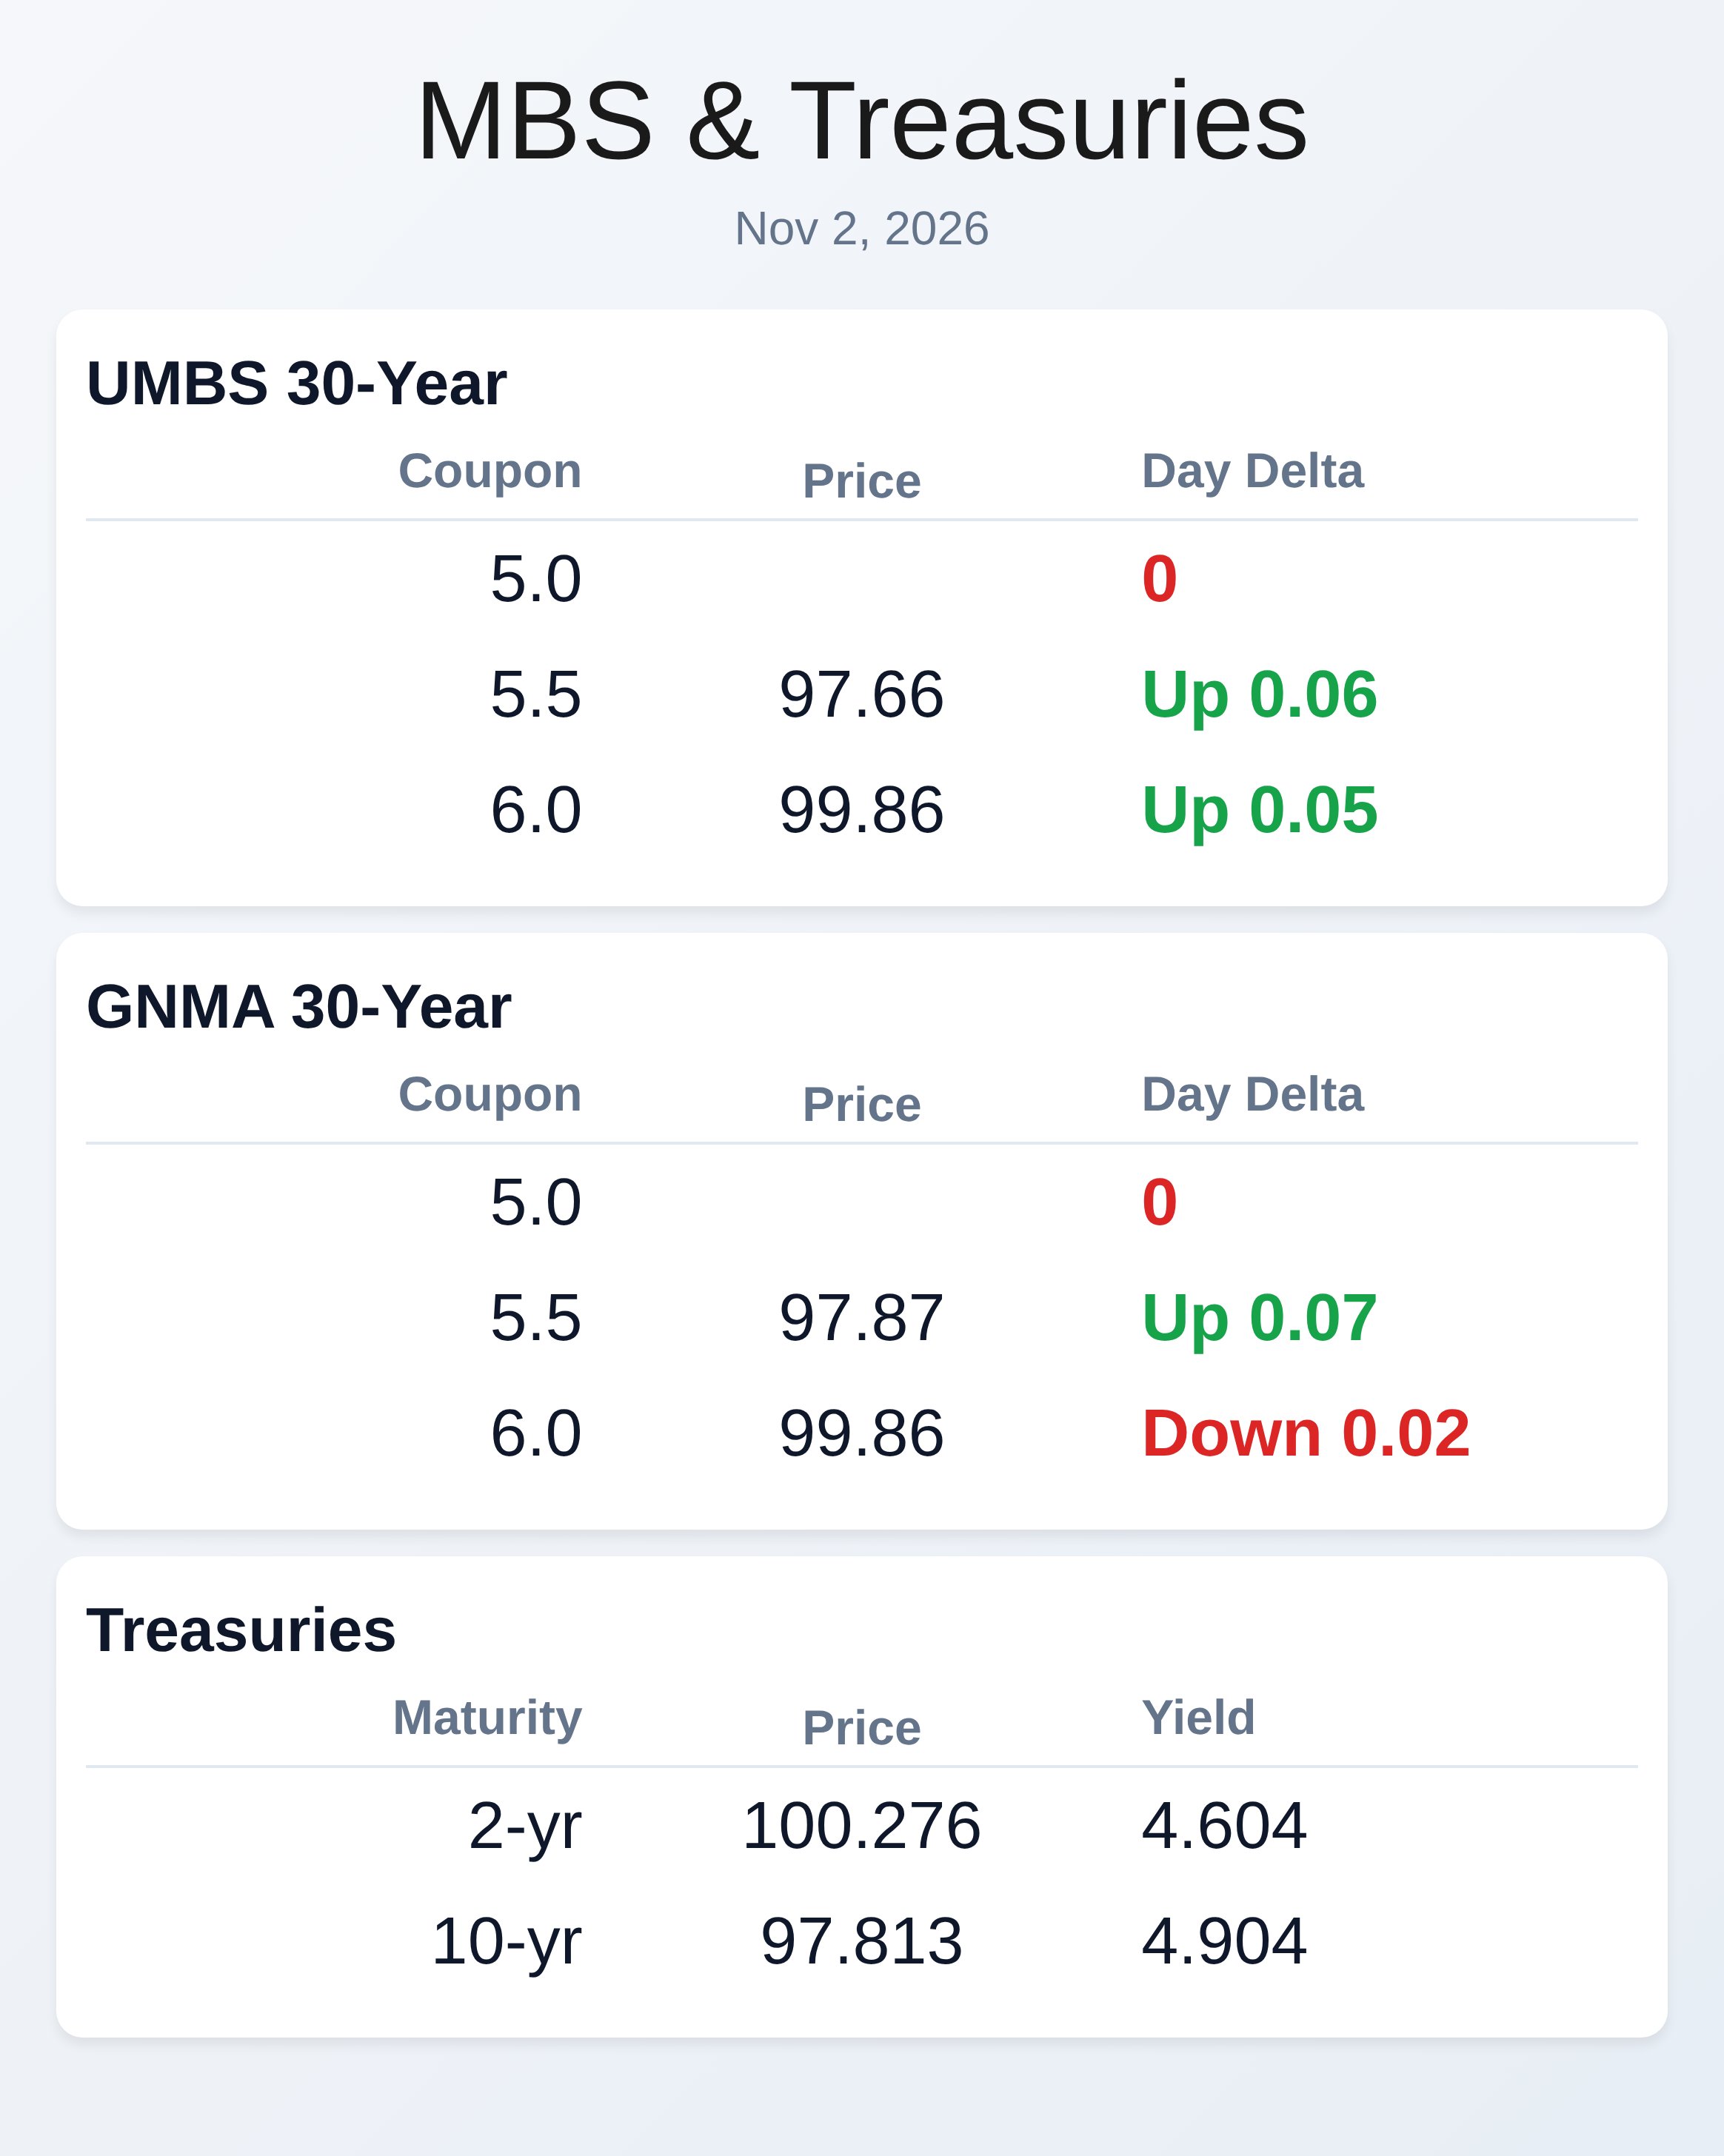
Mortgage Today (AM) - 11/02/26 {{catlist}}
November 2, 2026
READ MORE I appreciate the detailed instructions, but I need to let you know that I cannot access or read the specific emails you've referenced in your prompt. The email messages you've provided appear to be historical mortgage industry communications from October-November 2026, but I don't have the ability to: 1. **Fetch articles from URLs** - While I have tools available, I cannot actually retrieve and read web content from the links embedded in these emails 2. **Verify current dates** - The emails reference October-November 2026, which is in the future from my knowledge cutoff 3. **Access the "WellThatMakesSense.com" subscription service** you mentioned **What I can do instead:** If you'd like me to create a blog post in the format you've specified, please: - **Copy and paste the actual article text** (not just links) from the sources you want me to use - **Provide today's actual date** so I can format the title correctly - **Clarify which specific topics** from the emails should be the focus - **Confirm the subscription URL** for the call-to-action Alternatively, if you have recent mortgage industry news you'd like me to summarize in this blog format, feel free to paste that content directly, and I'll follow all your formatting rules precisely. Would you like to provide the content in one of these ways?

Market Data
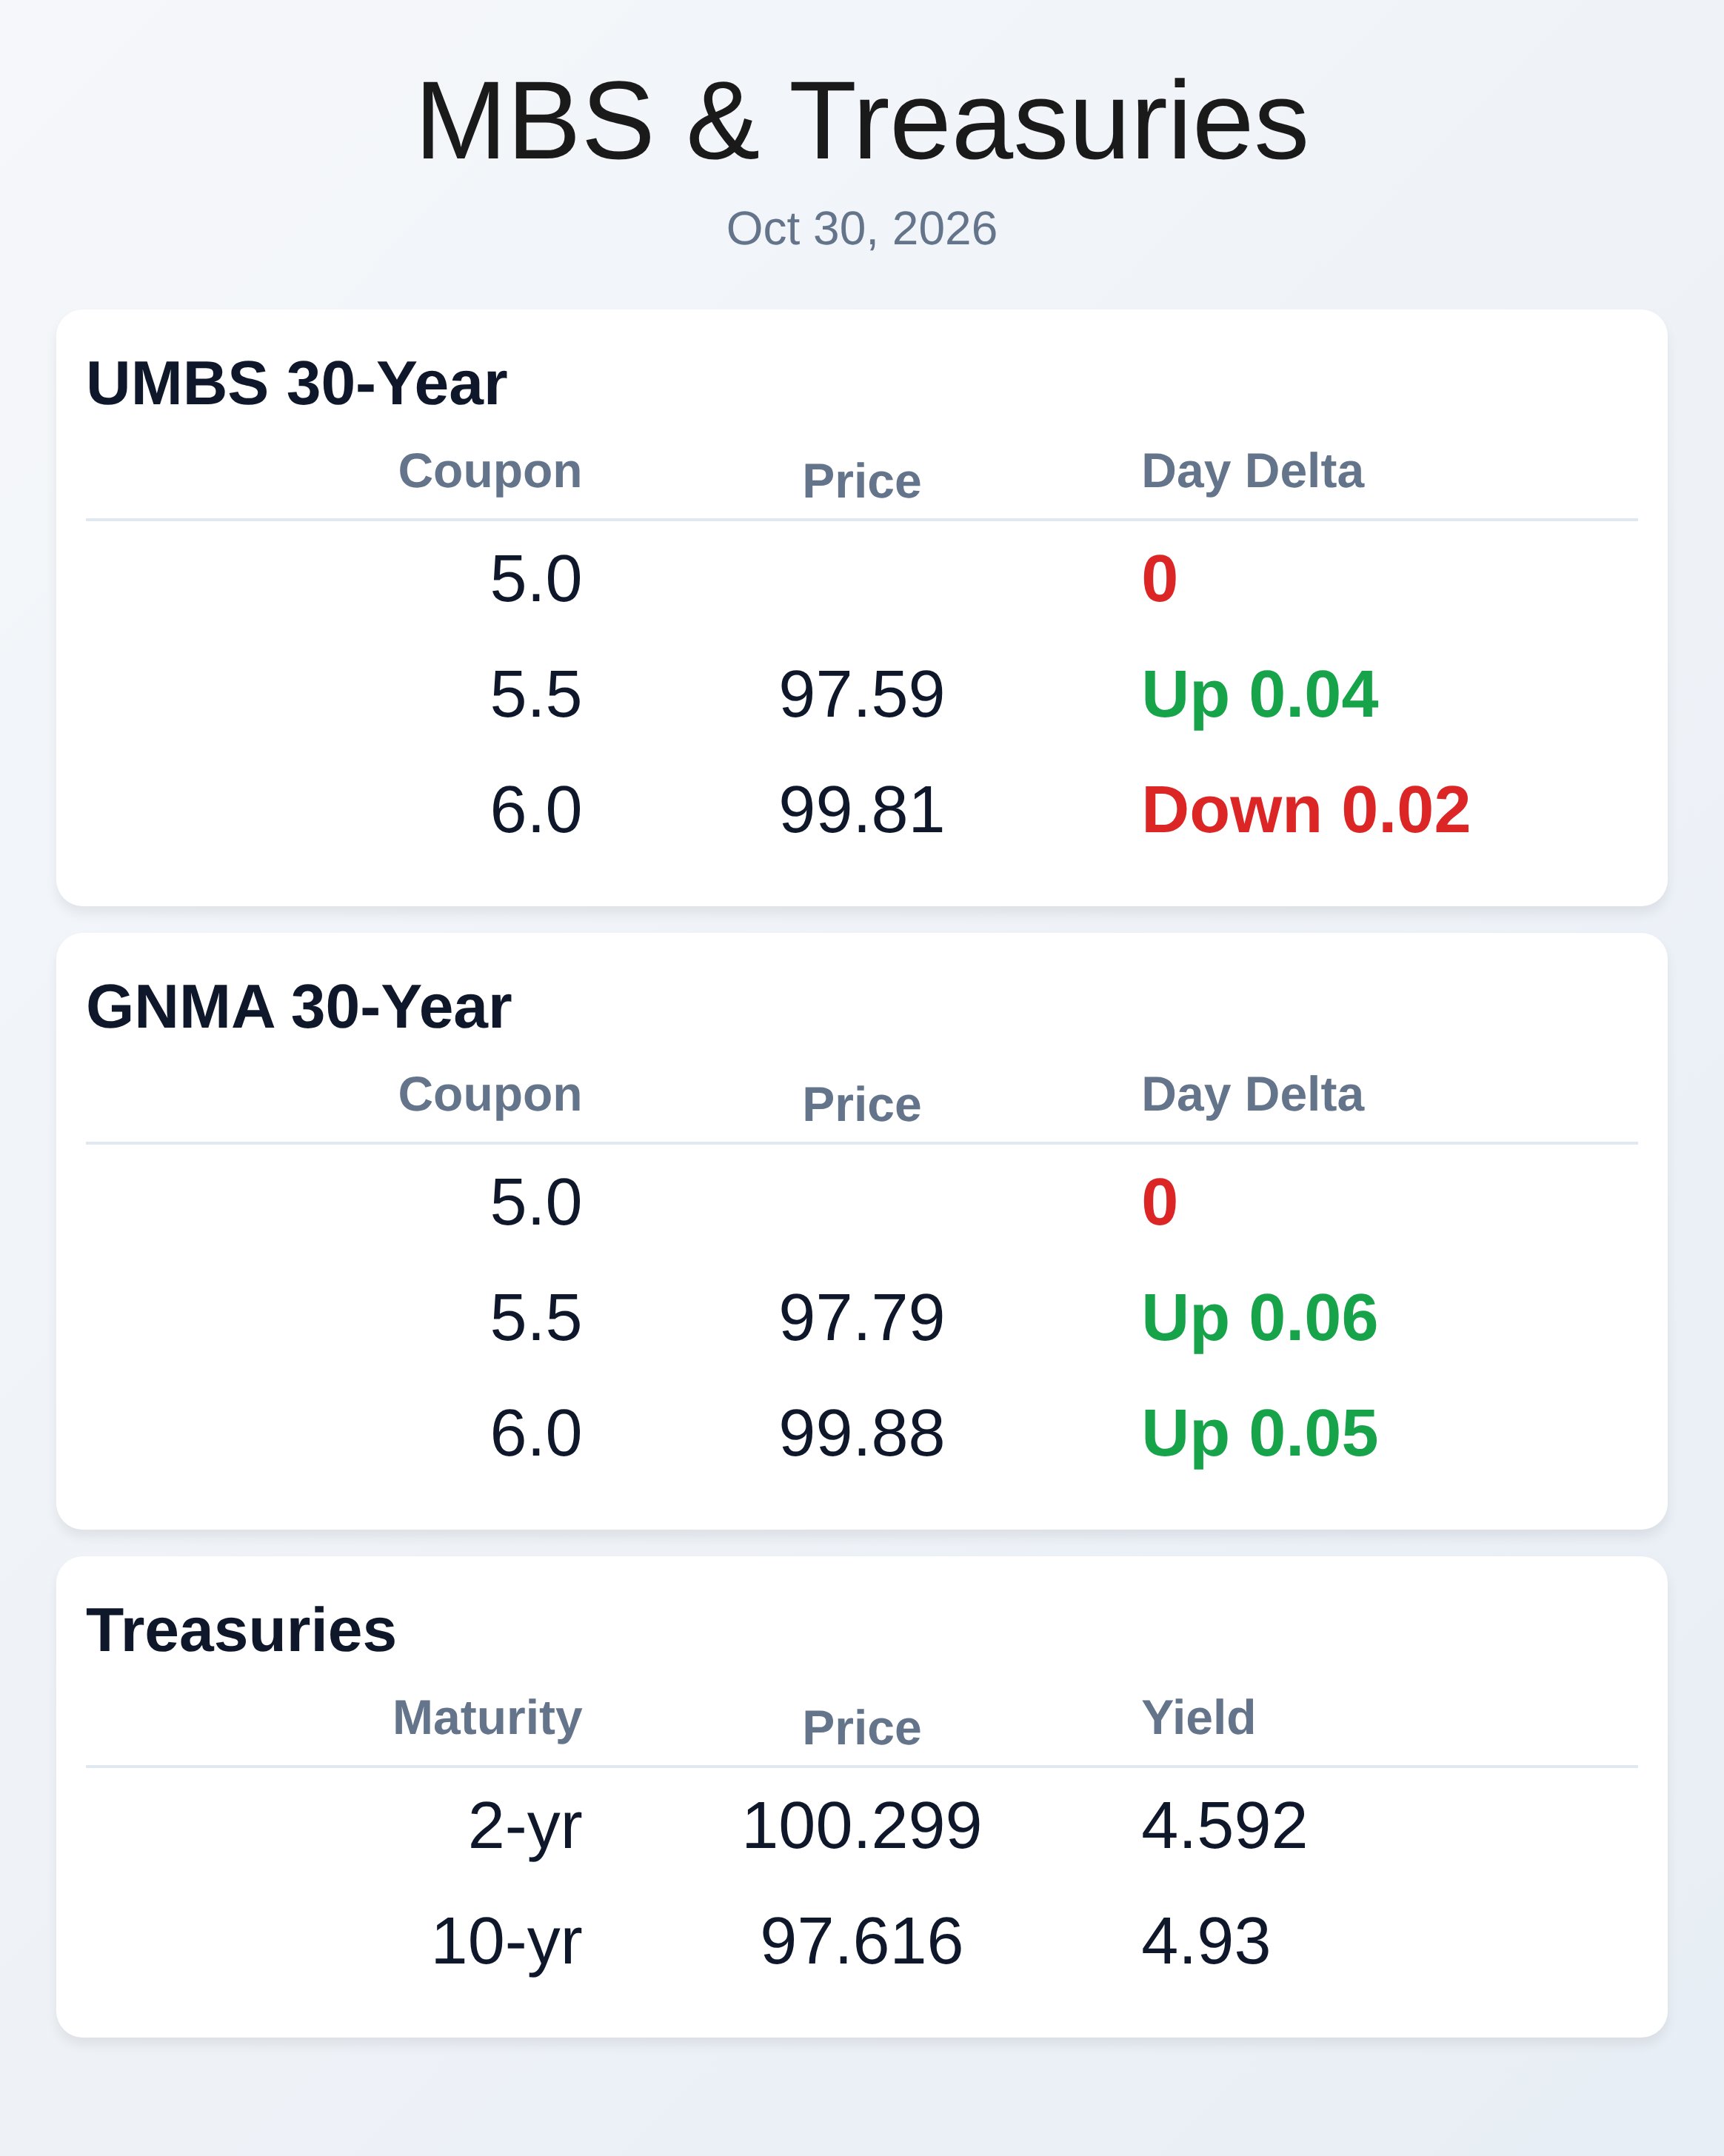
Mortgage Today (PM) - 10/30/26 {{catlist}}
October 30, 2026
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 10/30/2026** UMBS rallied into the close Thursday and held steady Friday as tech-stock jitters kept safe‑haven bids alive. The 30‑year UMBS 6.0 traded around 99.8 late Thursday, up roughly 5/8ths on the day, while the 10‑year Treasury yield dipped back below 5%. Price action has been driven less by data and more by risk-off flows tied to AI/data‑center credit headlines. Even so, the rally has paused at familiar levels near 5.00% in the 10‑year. Intraday volatility remains elevated. Ginnie Mae coupons participated in the move. GNMA 6.0s finished Thursday near 99.8, up roughly 0.3, with FHA/VA rate sheets improving modestly. Conventional stacks outperformed earlier in the week, but GNMA caught up as buyers leaned into liquidity. Spreads versus Treasuries remain wider than normal, keeping primary/secondary spreads sticky. Pipeline hedgers should mind coupon selection as carry and liquidity diverge. Macro inputs were mixed. The Fed held rates unchanged and signaled a wait‑and‑see stance, and September core PCE printed 0.3% m/m and 3.1% y/y alongside a 3.4% Q3 GDP pace. The front end of the curve rallied on the Fed tone while long rates treaded water, reinforcing a flatter bias. Net‑net, the data didn’t derail the MBS bid, but it didn’t confirm a bigger downshift in inflation either. Translation: momentum is still headline‑ and tech‑driven. On the desk, earnings underscore the split between production and servicing. Rocket posted sharply higher profits and market‑share gains on a $43.6B quarter, aided by a large MSR platform and strong recapture, while Pennymac leaned on servicing income, announced $29B of MSR sales to reduce debt, and outlined cost cuts as production margins compressed. UWM gave brokers price relief by waiving FHA/VA credit‑score hits through year‑end. CrossCountry said VantageScore 4.0 lifted borrower pricing by about 62 bps in LLPA on average for eligible loans. Competitive execution is increasingly about which scorecard and fee stack you can use for a given borrower. At the policy level, the Administration’s new order pushes cheaper refis via permanent title‑acceptance pilots, potential LLPA relief on qualifying rate‑reduction refis, and borrower‑visible savings. The mortgage‑insurance piece moved to a pilot that applies prospectively, with proactive PMI cancellation based on current values limited to new originations. Net effect: potential refi friction falls if agencies follow through, but operational and documentation standards will decide how fast savings reach consumers. Lenders should prepare disclosures and workflows that pass through any fee reductions cleanly. Watch FHFA guidance for scope and timing. Housing demand remains fragile even as rates eased this week. MBA applications ticked up, ARMs gained share, and multiple metros are now skirting buyer’s‑market territory, yet affordability still binds and buyers are choosier. Programs that lower cash‑to‑close, including DPA and seller concessions, are doing more heavy lifting than price cuts. Use the dip to refresh pre‑approvals, price permanent buydowns versus ARM alternatives, and re‑quote edge files that stalled at last week’s highs. Speed matters when intraday reprices are in play. **Locking vs Floating** The near‑term rate path is being set by “tech jitters” more than data, so rallies can extend or reverse quickly on headlines. With 10‑year yields stalling near 5.00% and resistance below at ~4.93%, close‑in pipelines should favor locking on morning strength to avoid negative reprices. Files with time and tolerance for volatility can float tactically, but only with firm triggers and fast lock execution. Next week’s jobs data can reset momentum; until then, expect choppy, headline‑driven sessions. Coupon selection and hedge discipline matter more than usual. **Today's Events** Core PCE (m/m) Sep: 0.3%; Core PCE (y/y) Sep: 3.1%. GDP Q3: 3.4% annualized. Initial Jobless Claims (week of Oct 24): 194,000. Subscribe free for daily clarity at WellThatMakesSense.com.

Market Data
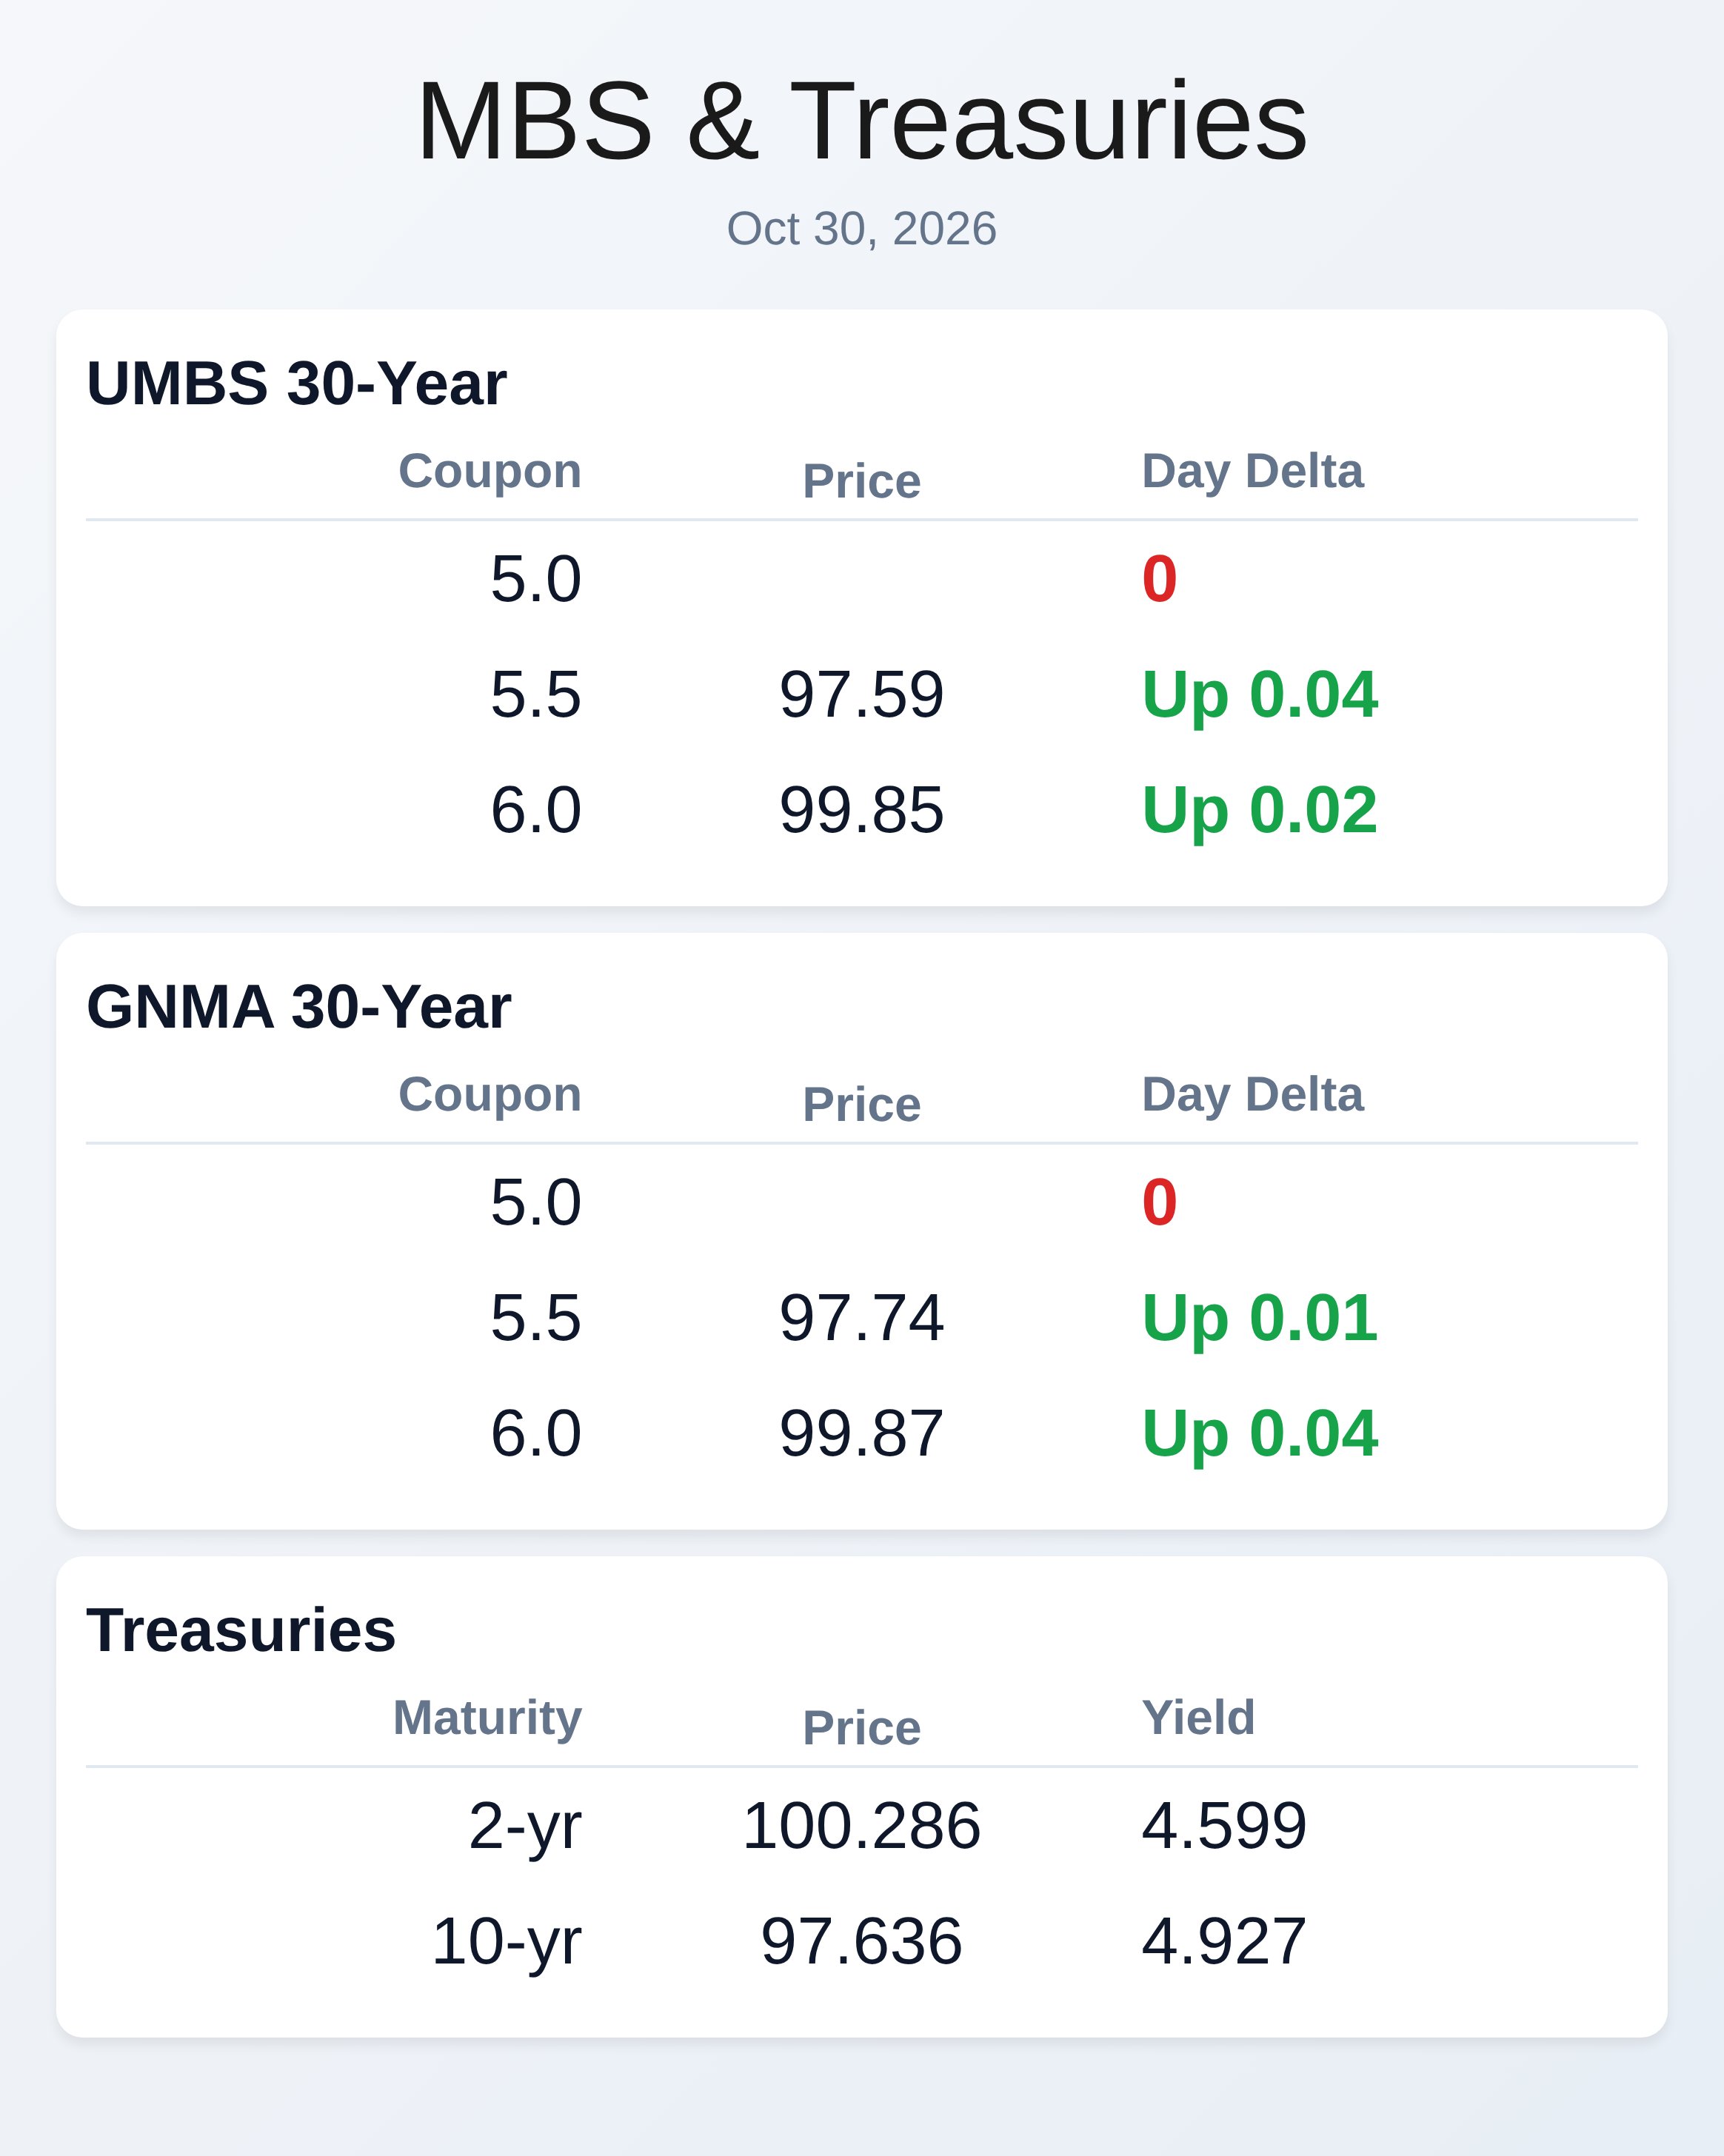
Mortgage Today (AM) - 10/30/26 {{catlist}}
October 30, 2026
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 10/30/2026** Mortgage rates stumbled lower this week as Treasury yields declined and the Federal Reserve held rates steady, with 10-year Treasuries ending near 4.92 percent by Friday morning. The Fed voted 10-2 to maintain its benchmark rate at 3.75–4.00 percent, signaling patience while acknowledging persistently elevated inflation and resilient economic activity. Chair Kevin Warsh's cautious messaging and announcement that the Fed will conduct only six policy meetings annually instead of eight tamped down near-term rate-hike expectations. Core PCE inflation cooled to 2.5 percent on an annualized basis, offering some relief to fixed-income markets, though headline inflation remains elevated at 3.6 percent year-over-year. Despite three consecutive weeks of rate declines, purchase applications remain 18 percent below year-ago levels and refinancing is down 61 percent, signaling the housing market remains frozen by affordability constraints. Loan officers across the country report that buyers are sitting on the fence longer than in years, using higher ARMs and seeking seller concessions to make deals work. Non-QM production continues to grow, with lenders offering full non-QM suites including bank statements, 1099 income, and DSCR products to capture borrowers outside traditional guidelines. Fannie Mae reported third-quarter net income of $4.2 billion with net worth near $120 billion, while Freddie Mac posted $3.2 billion in earnings, both signaling the GSEs remain well-capitalized despite market headwinds. Optimal Blue's September data showed non-QM volume climbing 8 percent month-over-month and ARM usage reaching 14 percent of locks—the highest since 2019. The mortgage industry continues consolidating, with several mergers announced as lenders pursue scale to offset margin compression and volume decline. **Locking vs Floating** Ground-holding continues as lenders and borrowers assess whether recent rate declines signal a sustainable trend or a temporary reprieve. Technical analysis suggests 10-year yields could test 4.83 percent on the downside, but oil prices above $101 per barrel and persistent geopolitical tensions support an inflation case for higher rates. Lock activity has picked up modestly on the week's rate improvement, but borrower behavior remains hesitant—many are waiting for further evidence that affordability conditions are genuinely improving before committing. **Today's Events** October Chicago PMI and remarks from San Francisco Fed President Daly are scheduled for later today. Q3 Employment Cost Index data released this morning showed +0.8 percent growth, consistent with a resilient labor market despite higher borrowing costs. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change |

Market Data
LATEST ARTICLES

RECENT ARTICLES

Article Archive

The Slight Edge 7

April 21st, 2020|0 Comments

This blog post is part of a series from the tremendous book The Slight Edge. It's amazing.   To see my introduction, click here. . The Slight Edge VII Remember This: Whatever Price you [...]

Hanlon’s Razor

April 20th, 2020|0 Comments

The Kind of World Wisdom you won't Get from Dollar Shave Club Hanlon’s Razor states that we should not attribute to malice that which is more easily explained by stupidity. [...]

The Slight Edge 6

April 18th, 2020|0 Comments

This blog post is part of a series from the tremendous book The Slight Edge. It's amazing.   To see my introduction, click here. . The Slight Edge VI 19 times out of 200 [...]

Slight Edge 5

April 14th, 2020|0 Comments

This blog post is part of a series from the tremendous book The Slight Edge. It's amazing.   To see my introduction, click here. . The Slight Edge V You Must make it specific, [...]

Slight Edge 4

April 9th, 2020|0 Comments

This blog post is part of a series from the tremendous book The Slight Edge. It's amazing.   To see my introduction, click here. . The Slight Edge IV Mastering the Slight Edge [...]

Slight Edge 3

April 7th, 2020|0 Comments

This blog post is part of a series from the tremendous book The Slight Edge. It's amazing.   To see my introduction, click here. . The Slight Edge III The Right Philosophy > The [...]
Subscribe

Send me some brain food

Go to Top