**WTMS Blog Today = What’s up in Mortgage Today (AM) – 10/20/2026**
Mortgage originators face a tightening vise as October housing starts fell 5.2 percent to just 1.221 million annually, well below expectations of 1.305 million and signaling continued weakness in demand. The MBA expects 2027 production to fall 5 percent below 2026 levels to around $2 trillion, forcing lenders to scrutinize loan officer productivity and whether current headcount is sustainable through winter. September retail sales outperformed expectations by rising 0.8 percent versus a 0.3 percent forecast, yet this resilience masks underlying fragility as wage growth lags inflation for six consecutive months and borrower debt-to-income ratios remain dangerously elevated.
GSE repurchase activity jumped 19.5 percent quarter-over-quarter to $465.2 million in unpaid principal during Q2 2026, with Fannie Mae rejecting only 16.8 percent of repurchase demands while Freddie was more lenient at 46.9 percent. Pending home sales dropped 4 percent in September from August, marking the biggest monthly fall in over three years and pushing contract signings to their lowest level since 2014 excluding the pandemic. Existing home inventory climbed to 4.8 months of supply while nearly one in five sellers cut asking prices, signaling a buyer’s market emerging despite stubborn mortgage rates hovering near 7.4 percent.
**Locking vs Floating**
Rate volatility has created meaningful two-sided risk for pipeline hedgers as the 10-year Treasury yield swung wildly from 5.36 percent down to 5.03 percent within the same week. Inflation data continues to surprise to the upside, yet technology sector weakness and concerns over unsustainable AI infrastructure financing triggered flight-to-safety flows that pushed bonds higher. The Fed’s December rate-hike probability remains elevated above 88 percent despite hawkish sentiment fading, leaving both lock and float strategies exposed to further swings depending on whether earnings season confirms AI investment returns can justify financing costs.
**Today’s Events**
September Housing Starts: 1.221M annualized (est. 1.305M, down 5.2 percent). Building Permits: 1.400M (est.
1.385K, down 0.2 percent). September Pending Home Sales (pending). Redbook same store sales data.
Atlanta Fed GDPNow Q3 release.
**Bond Pricing**
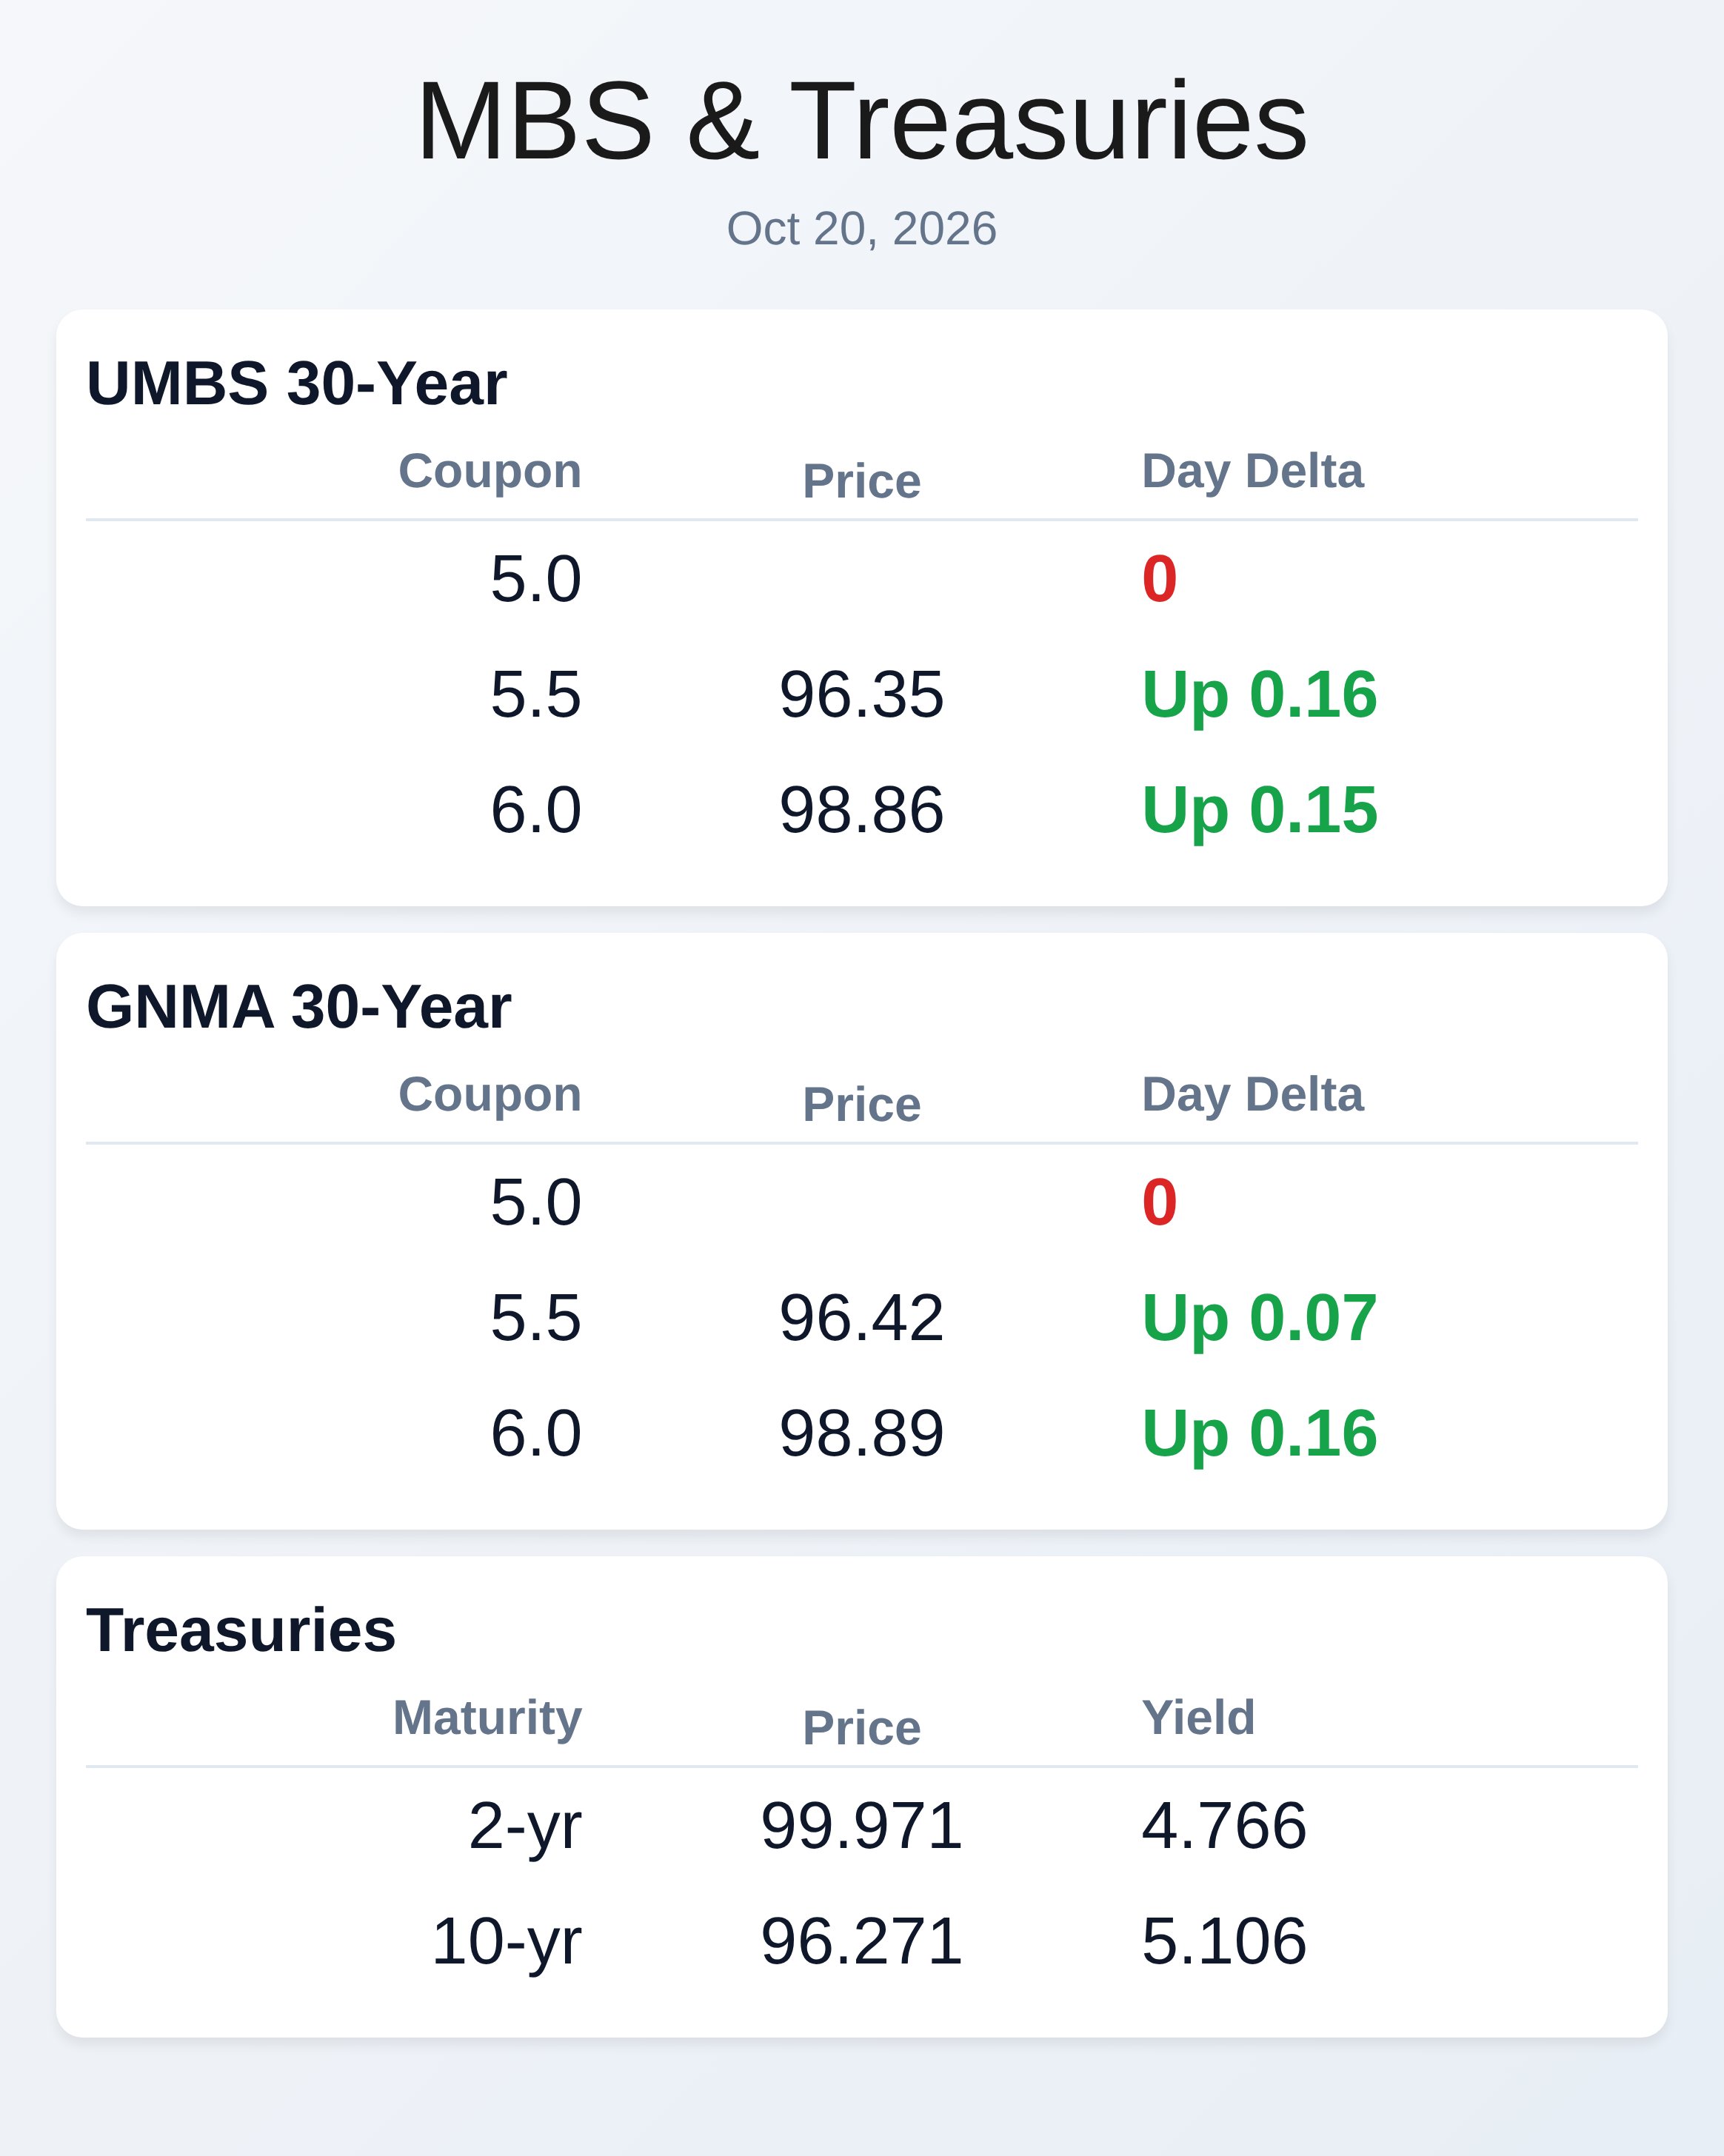
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |