**WTMS Blog Today = What’s up in Mortgage Today (PM) – 10/16/2026**
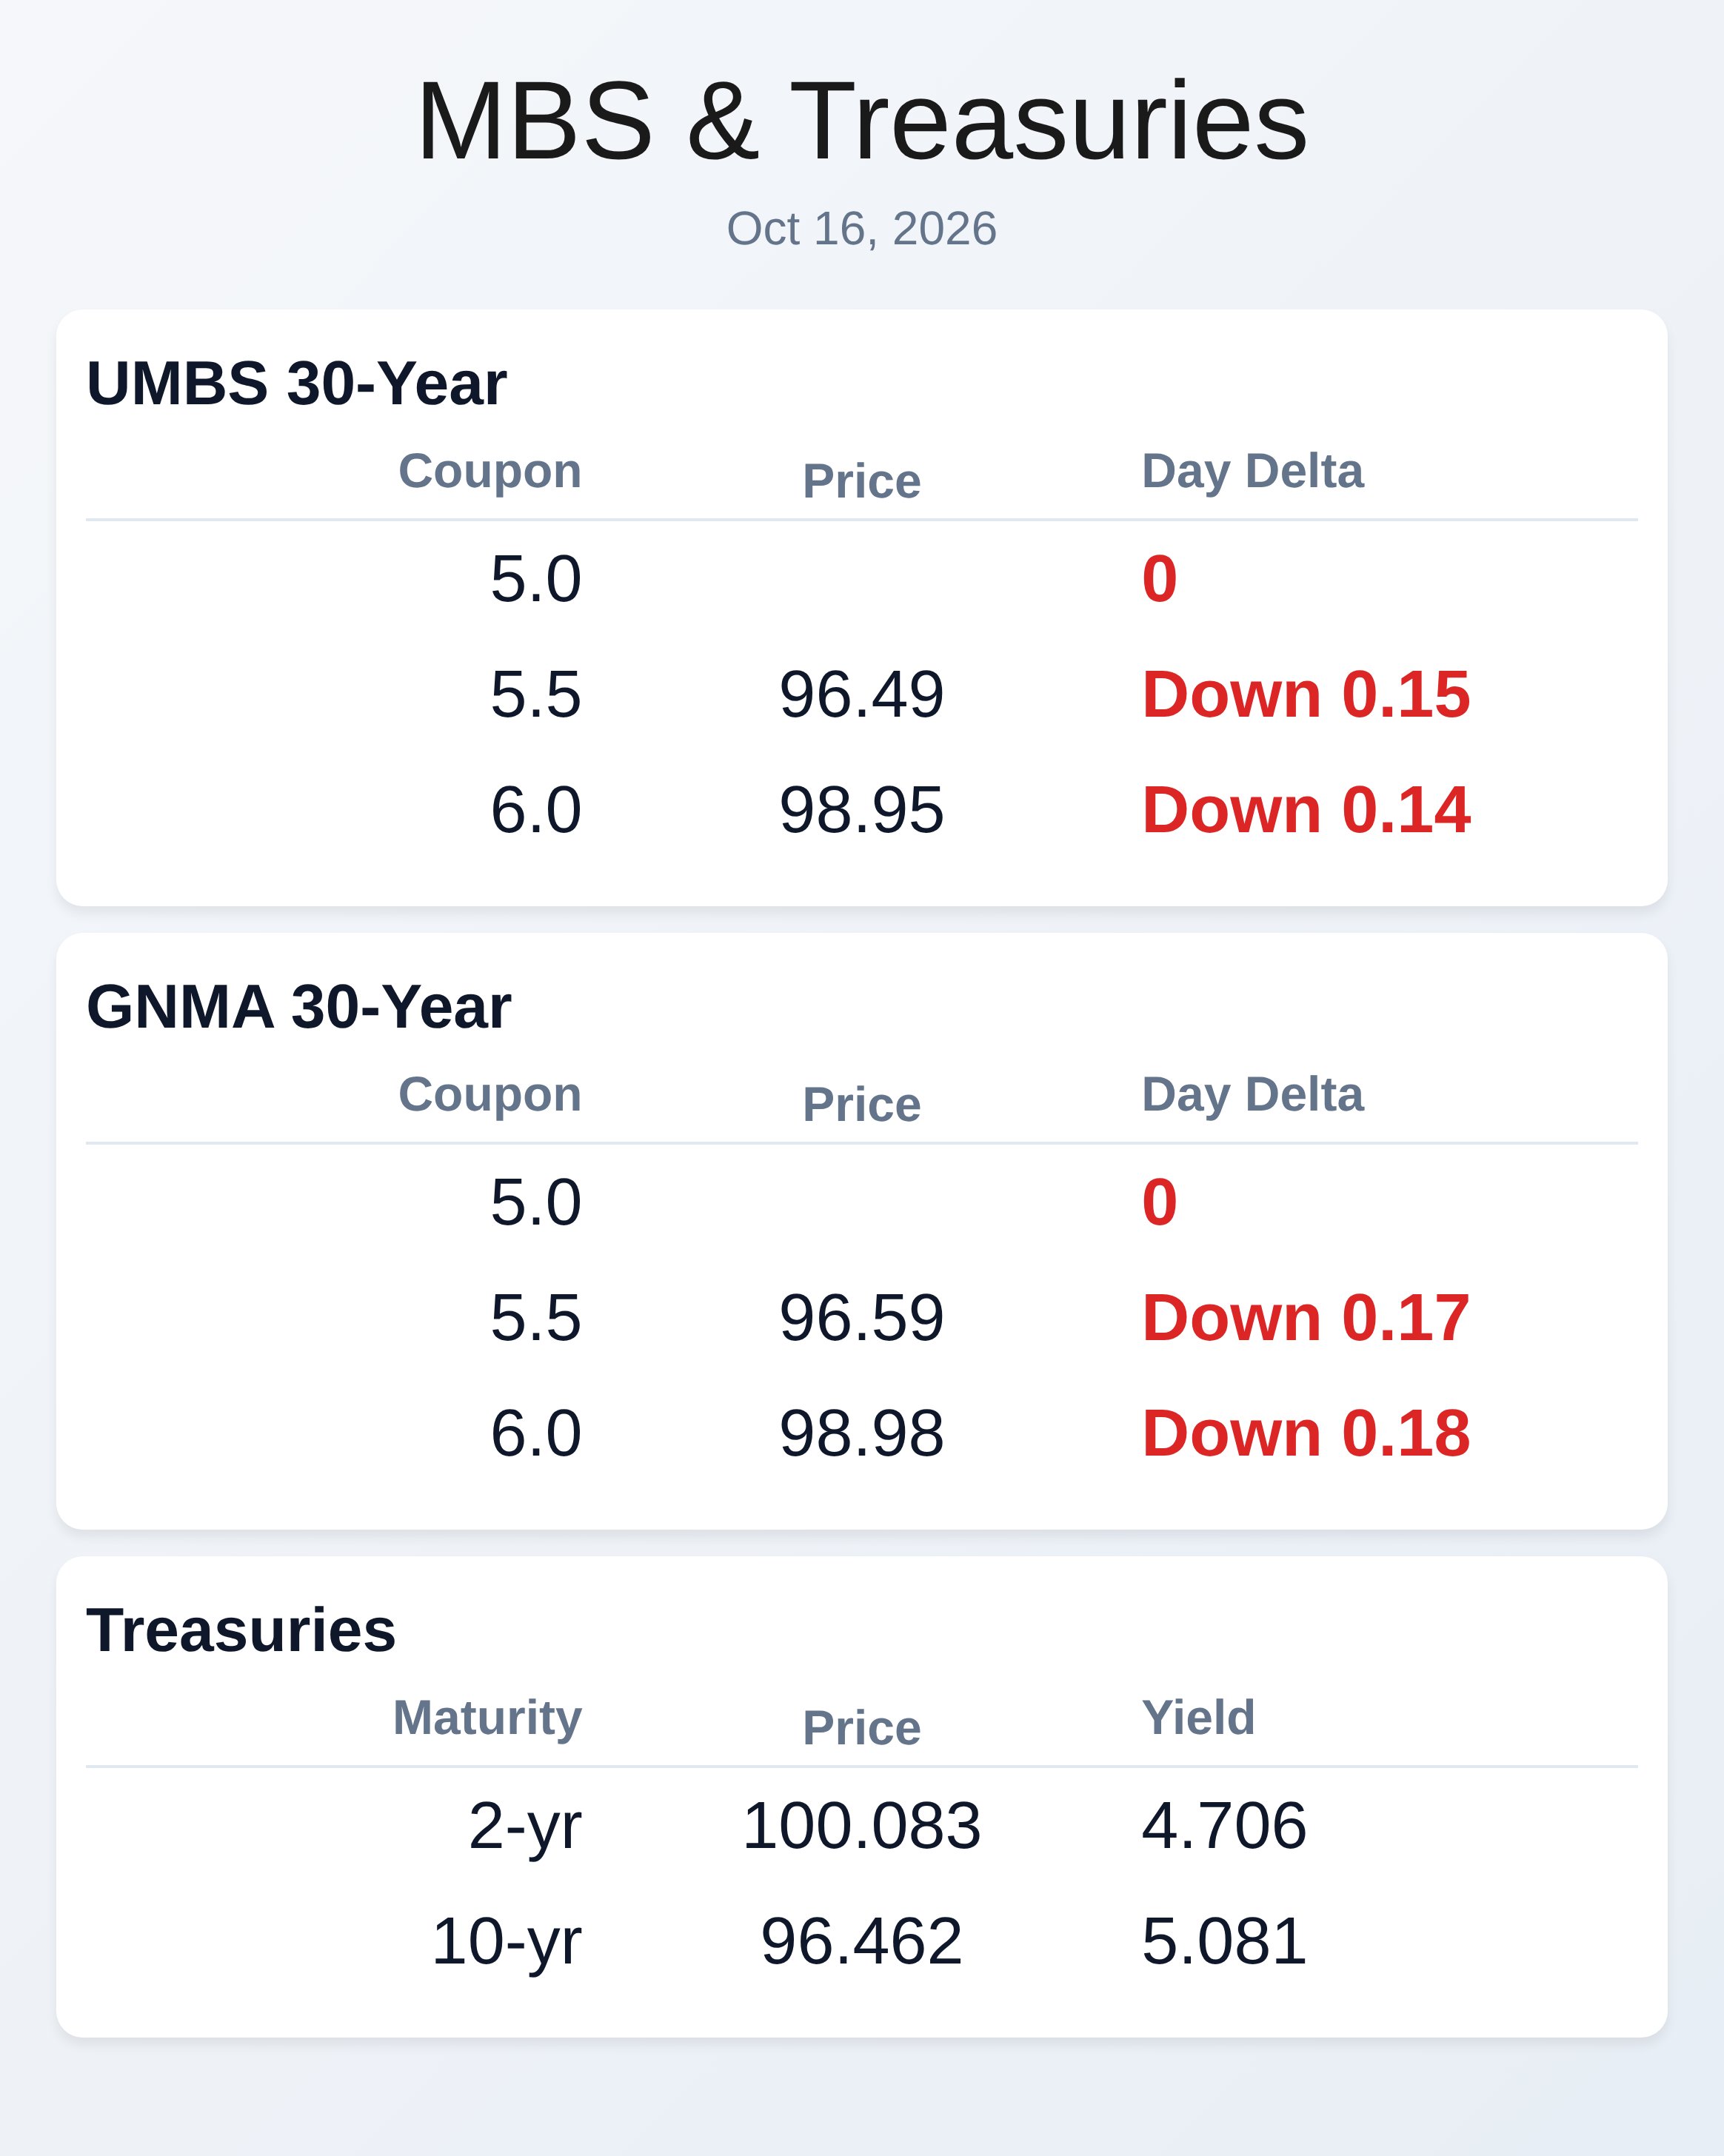
Mortgage rates caught their breath Friday after one of the best five-day rallies in months, as technology selling and AI contagion concerns gave way to profit-taking and cautious consolidation. The 10-year Treasury yield settled around 5.08 percent after touching 5.05 percent Thursday, still down meaningfully from last week’s 5.36 percent high. UMBS 6.0 prices ended near 98.92, up modestly on the week despite Friday’s choppy action reflecting uncertainty about whether bond weakness driven by earlier inflation data will resurface Monday.
Mortgage origination pressures intensified as the industry absorbed the MBA’s revised 2027 forecast—origination volume expected to decline 5 percent below $2 trillion next year. September applications fell 4.2 percent week-over-week, with purchase applications down 16 percent year-over-year and refinancing activity constrained by elevated rates and limited economically attractive refi candidates. Lenders are trimming LO staffing and shifting toward wholesale and correspondent channels to manage margins in an environment where gain-on-sale compressed to historic lows, with one major bank reporting a 56-basis-point quarterly decline.
Credit quality remains a focal point as GSE repurchase activity climbed 19.5 percent in Q2 2026, with Rocket Mortgage, United Wholesale Mortgage, and Lakeview Loan Servicing leading repurchase shares. Home sellers now outnumber buyers by 63 percent—the widest gap since records began in 2013—while inventory sits at a 4.8-month supply, the highest level since March 2020. Just five of fifty major metros still favor sellers, placing considerable pressure on transaction volume and borrower qualification as affordability deteriorates.
VantageScore 4.0 implementation across Fannie Mae and Freddie Mac continues reshaping credit policy and pool composition, with sub-700 FICO loans now representing 11.4 percent of 2026 UMBS issuance—the highest share since 2023. Fannie Mae’s November 13 occupancy update will flag potentially inaccurate designations using expanded borrower history and financial profile data, requiring lenders to tighten documentation and verification protocols. UAD 3.6’s November 2 mandate drove market discussion around hybrid appraisal adoption as originators prepare for expanded property data requirements and longer inspection timelines.
Industry consolidation accelerated with Dart Appraisal acquiring ACT Appraisal, while Lower pulled a $300 million-plus team from Supreme Lending despite earlier departures, signaling leadership’s conviction about growth prospects in the downturn. MBA Homebase launched as a professional development platform targeting 25,000 loan officers by year-end through NMLS-approved continuing education, coaching, and access to FirstHome IQ’s Trust Certified program. Capital markets execution became critical as rapid repricing environments, widening MBS spreads, and uncertain investor appetite tested lenders’ discipline on hedging, coupon selection, and delivery strategies.
Monday’s economic calendar brings limited data, but inflation expectations and energy prices remain key drivers as markets await direction from the Fed and incoming economic reports. Bond traders remain cautious despite the week’s rally, viewing it as a potential trial balloon for a broader correction rather than a confirmed trend reversal. Lenders should monitor rate stability heading into next week while preparing for October’s remaining data, including PPI and retail sales, which could shift the inflation narrative and testing whether 5.1-5.2 percent Treasury yields attract sustained value buying or trigger renewed weakness.
**Locking vs Floating**
With Treasury yields near two-week lows and AI-driven stock weakness potentially offering temporary relief, borrowers closing within two weeks have tactical opportunity, but the broader rally’s durability remains questionable. Tech stabilization or renewed inflation concerns could push yields back toward 5.27-5.34 percent resistance levels, suggesting selective locking for rate-sensitive loans rather than wholesale pivot to aggressive lock positioning.
**Today’s Events**
Import Prices (September): 0.8% forecast, 0.7% prior
Industrial Production (September): 0.4% forecast, 0% prior
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |