**WTMS Blog Today = What’s up in Mortgage Today (AM) – 10/23/2026**
UMBS prices rallied to their highest levels in a month on Thursday as technology stocks sold off and safe-haven flows pushed 10-year Treasury yields below 5 percent for the first time since late September. Bond market volatility remains elevated as geopolitical tensions surrounding Iran, persistent weakness in AI infrastructure companies, and short covering all reinforce demand for defensive assets. The executive order signed this week to reduce housing costs directs Fannie Mae, Freddie Mac, and federal agencies to implement proactive mortgage insurance cancellation pilots, expand title insurance waivers, and reduce USDA and VA loan rates, though real-world impact depends entirely on agency implementation guidance.
GSE repurchase activity jumped 19.5 percent in Q2 2026 to $465.2 million in unpaid principal, with Fannie Mae being notably more aggressive than Freddie Mac at resolving demands. Mortgage application volumes continue to decline despite a small weekly dip in rates, signaling that the absolute level of 7.41 percent remains a ceiling for most borrowers seeking purchase or refinance opportunities. Housing demand remains structurally constrained by elevated affordability pressures and high home prices that persist even after the recent Treasury rally.
Homebuilder confidence has collapsed to its lowest level since June 2012, as rising financing and construction costs, labor shortages, and persistent price pressures force builders to cut incentives and inventory. The MBA and Fannie Mae have both slashed their 2027 mortgage production forecasts, with expectations now below $2 trillion and originations estimated to decline five to eighteen percent depending on rate scenarios. Loan officers continue to face retention pressures as independent mortgage bankers lost 100 net originators through September while non-delegated and broker channels gained 327, reflecting a structural shift toward lower-cost operating models.
AI governance and technology adoption remain top priorities for lenders managing both risk and compliance in an increasingly complex regulatory environment shaped by recent federal interagency expectations.
**Locking vs Floating**
Lock now if you want certainty on closing costs and pricing with rates stabilizing near 5 percent on the 10-year. Float only if you have pipeline visibility and hedging strategies in place to capture potential further yield compression, though geopolitical and oil price volatility create two-sided risk.
Current market positioning suggests short covering and technical consolidation rather than a durable trend toward lower rates.
**Today’s Events**
October S&P Global Composite PMI (9:45 AM ET), October S&P Global Manufacturing PMI (9:45 AM ET), October S&P Global Services PMI (9:45 AM ET), October Consumer Sentiment Preliminary (10:00 AM ET), FOMC Meeting (October 28-29)
**Bond Pricing**
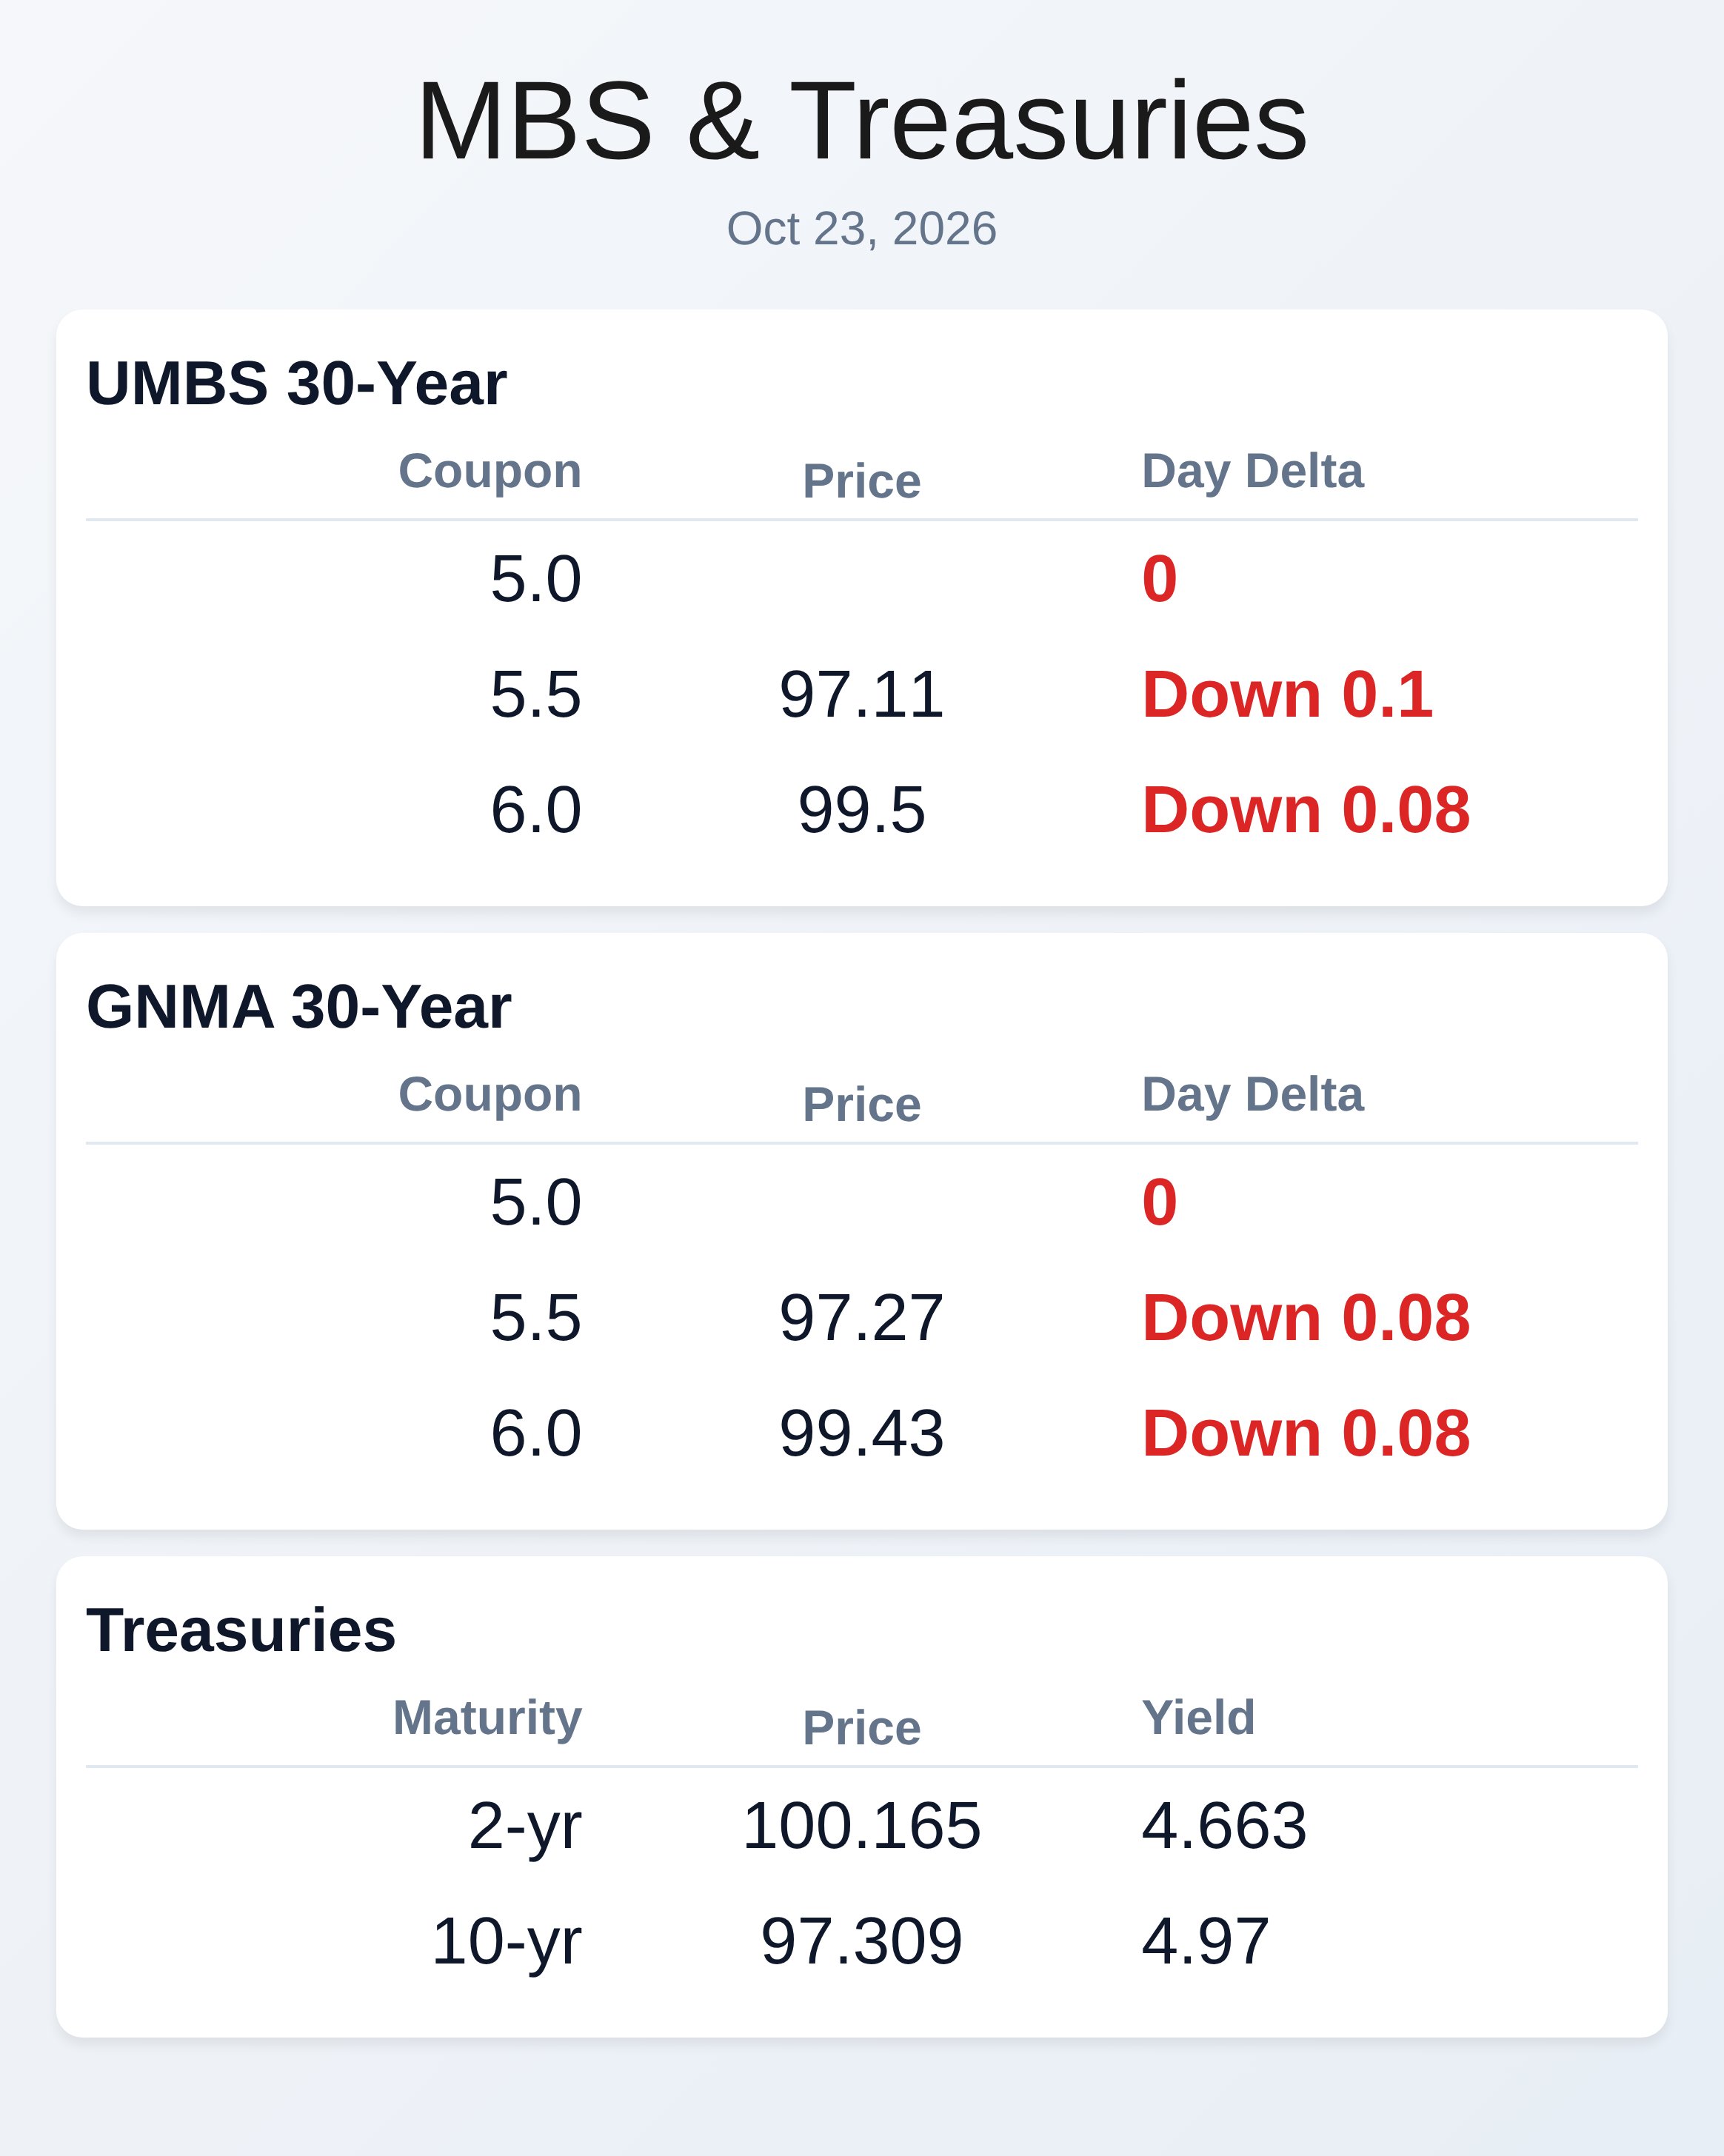
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |