**WTMS Blog Today = What’s up in Mortgage Today (PM) – 10/23/2026**
Mortgage rates improved sharply this week as a technology stock sell-off sent investors fleeing to bonds, with the 10-year Treasury yield dropping nearly 170 basis points to 4.96 percent by Thursday. The MBA ratcheted down 2027 origination volume forecasts to $1.98 trillion, citing persistent affordability pressures and elevated borrowing costs that continue to squeeze both purchase and refinance activity. Trump signed an executive order directing federal agencies to reduce mortgage costs through proactive PMI cancellation for eligible borrowers, permanent title insurance waivers on refinances, and potential reductions to loan-level price adjustments, though most savings would benefit existing homeowners rather than first-time buyers struggling with down payments and elevated home prices.
Homes priced at the median remain unaffordable for average American workers even with 20 percent down, requiring $90,191 in annual income versus the $79,534 average wage according to ATTOM data. Wire fraud incidents continued climbing with 45.9 percent of monitored loans carrying material risk related to wire transfer and title defects, while servicer repurchase activity spiked 19.5 percent in the second quarter with Fannie Mae issues accounting for 58.2 percent of buybacks. The industry saw MBA Annual draw 2,483 attendees representing 657 companies, marking a 4.3 percent year-over-year decline as consolidation pressures and talent churn reshaped conference participation among both lenders and technology vendors.
Technology valuations faced serious headwinds as Coreweave and other AI-backed firms sparked credit concerns, pulling down the Nasdaq and creating safe-haven demand for government bonds. September prepayment speeds slowed sharply with Fannie Mae CPR falling to 6.7 percent and Ginnie Mae declining to 7.6 percent, leaving less than half a percent of mortgages economically attractive to refinance and limiting originator refi revenue. Credit scoring debates intensified around VantageScore 4.0 implementation and LLPA implications as lenders weighed whether alternative models might expand access but weaken underwriting discipline, with sub-700 FICO loans now representing 11.4 percent of 2026 UMBS issuance.
**Locking vs Floating**
Tech weakness has created a temporary trading advantage for bonds this week, but the rally remains dependent on continued equity market concerns rather than fundamental economic improvement. Borrowers should recognize that rates have recovered from recent highs but remain historically elevated; locking makes sense for closings within 30 to 45 days unless Treasury volatility settles decisively lower. Floating is riskier given persistent inflation, fiscal deficits, and geopolitical risks that could reignite rate pressure once equity market anxiety fades.
**Today’s Events**
Existing home sales rose 1.5 percent month-over-month to 3.99 million, but remained 2.2 percent below year-ago levels. Housing starts reached 1.221 million versus forecast of 1.300 million. Building permits totaled 1.400 million against expectations of 1.390 million.
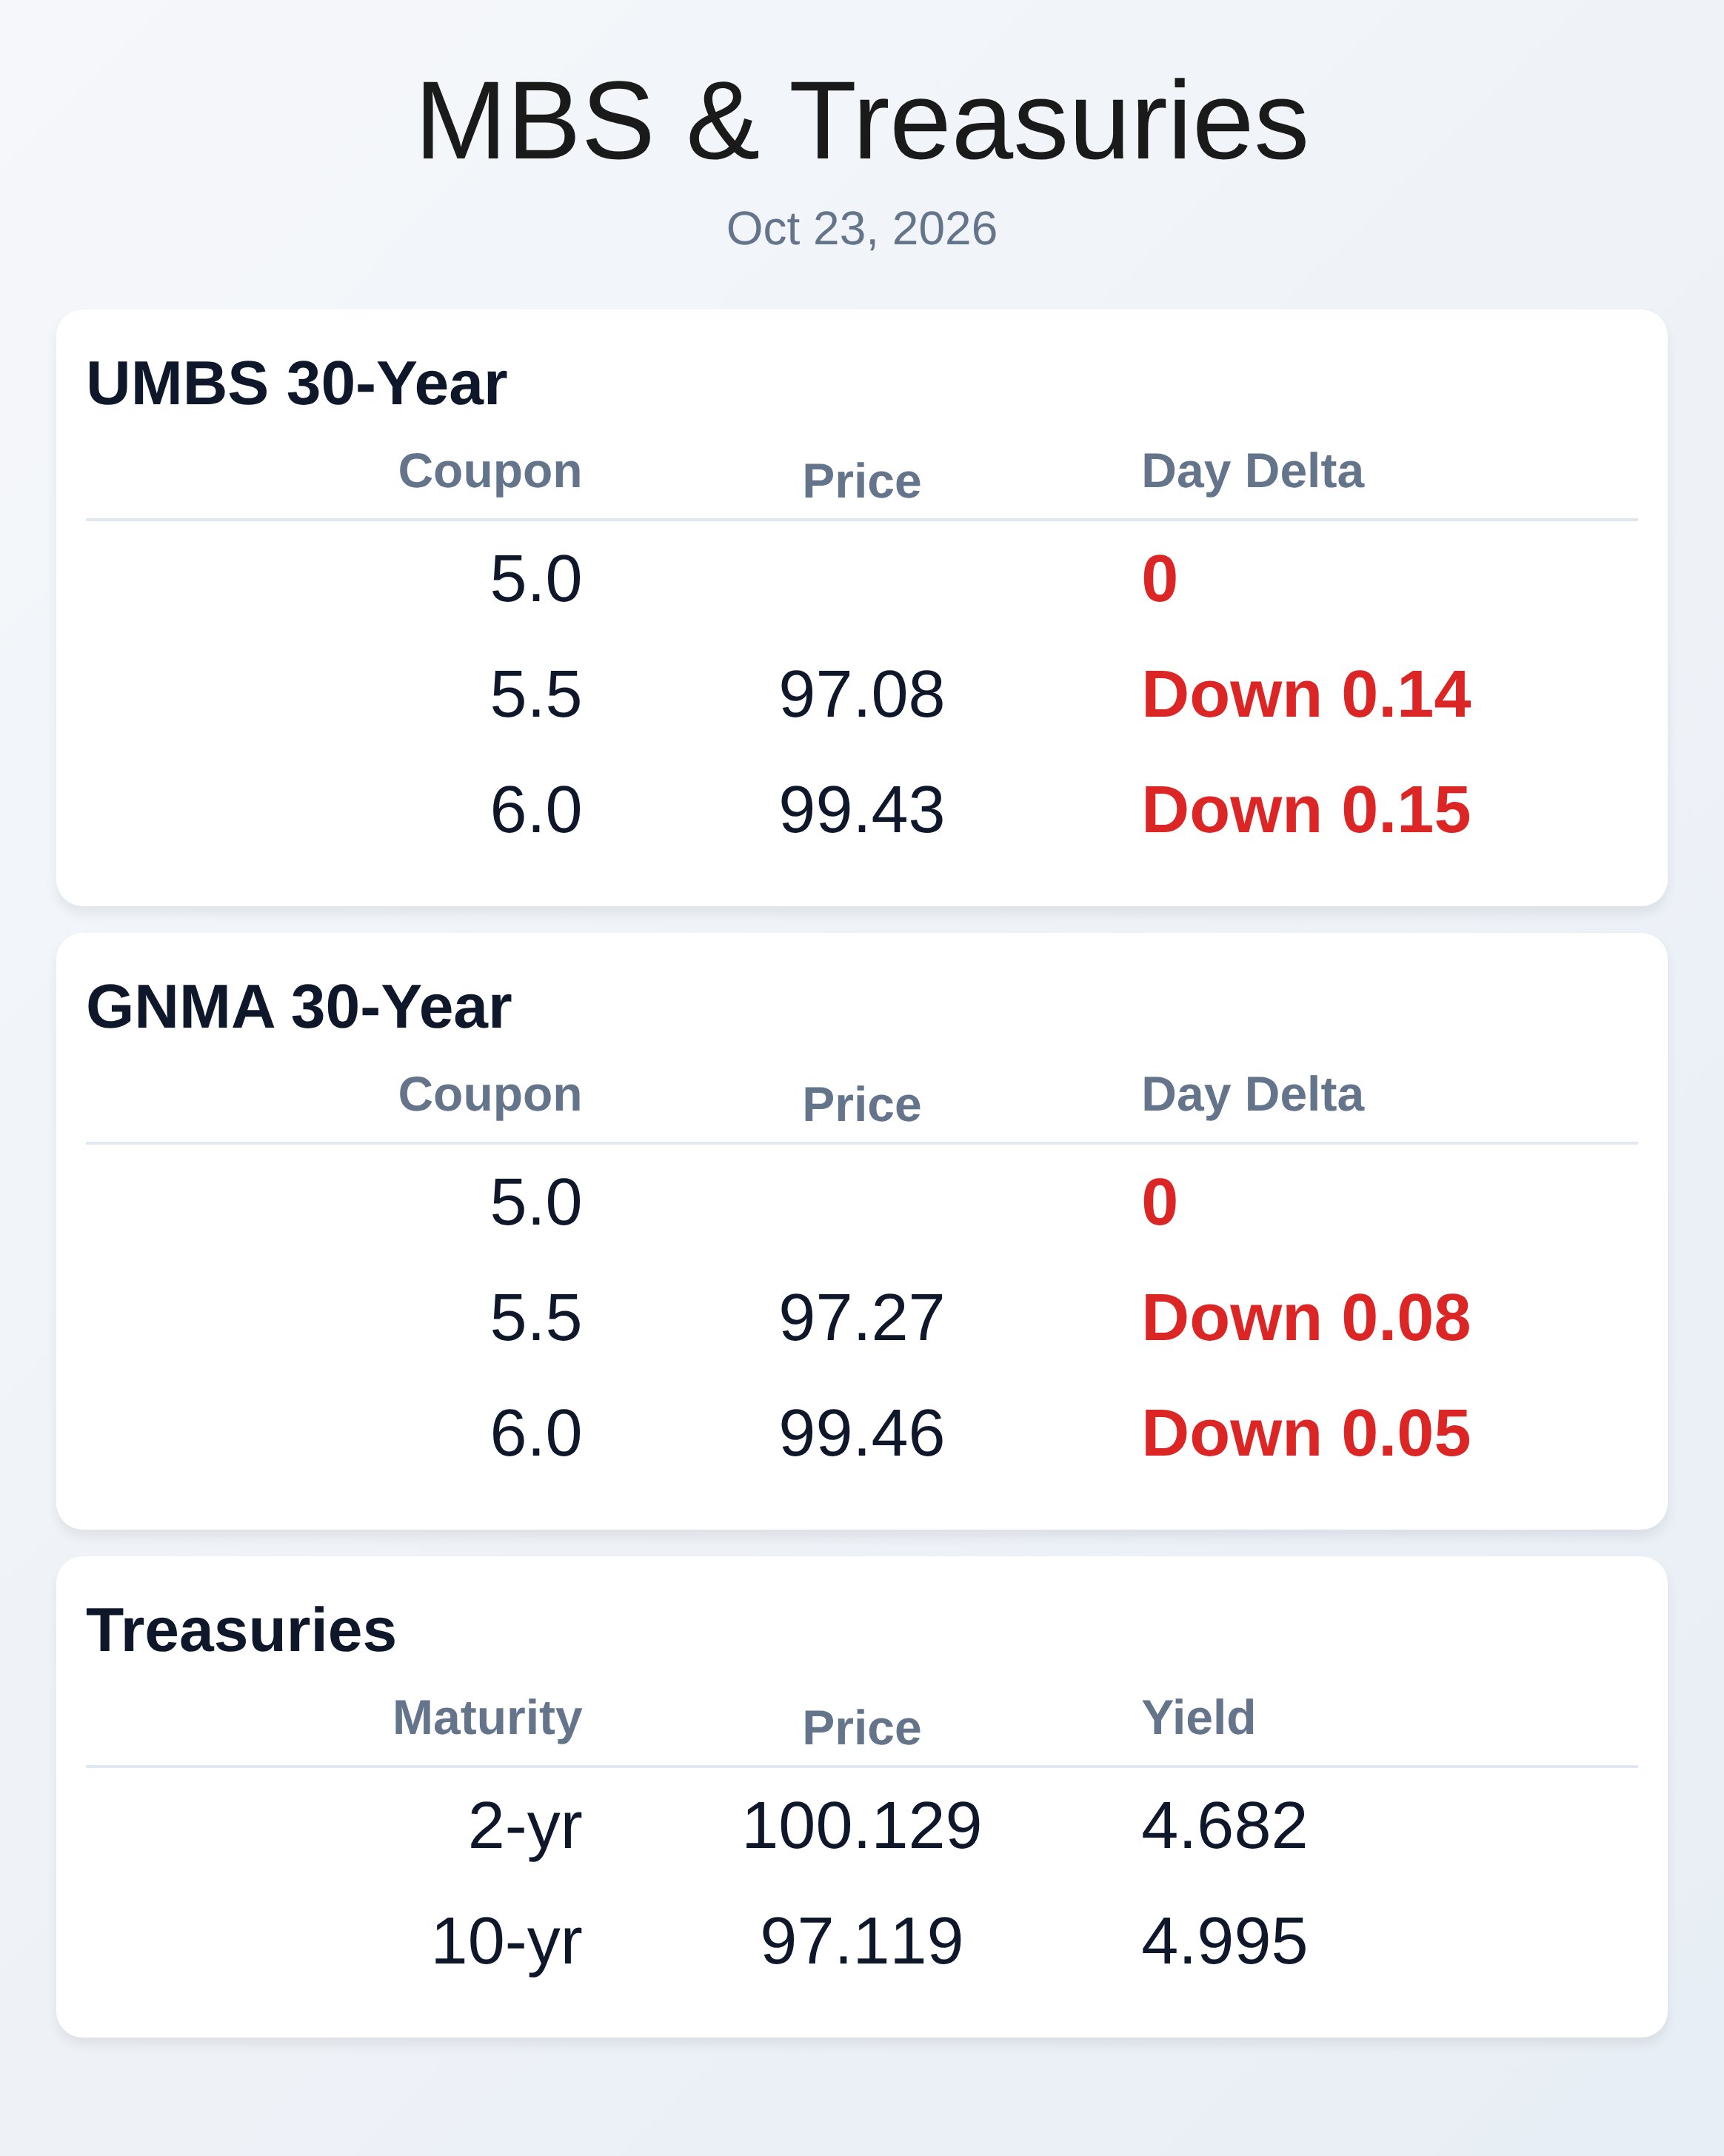
**Bond Pricing**
**UMBS 30 yr**
| Coupon | Price | Intra-Day Change |
**GNMA 30 yr**
| Coupon | Price | Intra-Day Change |
**Treasuries**
| Term | Yield | Price | Intra-Day Yield Change |