“Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.
I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.
I still remember how it started for me. It started in June of 2008. After 11 years …..Click to continue
November 6, 2026
November 6, 2026
WTMS Blog Today= Why Meta's Robot Butler and Walmart's Warehouse Bet Matter to Your Home Value
Two billion-dollar automation bets reveal what lenders and appraisers might value in homes within five years.
Picture this: You're touring a home built in 2028. The listing boasts 36-inch doorways, a dedicated charging alcove off the laundry room, and "robot-ready infrastructure" as casually as today's listings mention smart thermostats. Sounds absurd—until you notice Meta just built a five-foot humanoid called Max in three months with Chinese partner Fourier, while Walmart committed $6 billion to Symbotic's warehouse robots across 25 regional distribution centers.
These aren't science fiction moonshots. They're two competing automation strategies with a decade of collaboration behind them, and they're about to reshape what makes a home valuable and where people want to live. One vision puts robots in your kitchen. The other puts them 20 miles away, moving the goods that stock your kitchen. Both have mortgage implications you haven't considered yet.
Here's what the collision between household humanoids and industrial automation actually means for property values, and why your next appraisal might factor in things that sound ridiculous today.
Meta's Max Isn't About Folding Your Laundry (It's About Infrastructure)
Meta's prototype stands five feet tall, weighs 106 pounds, displays facial expressions, and can pick up small objects with redesigned hands. Max 2, reportedly in development since September, adds a projector, extra sensors for stairs, and a redesigned torso. It runs on Nvidia's Jetson Thor with 128GB of memory—the kind of specs that sound impressive until you remember current humanoids still struggle with basic tasks like folding clothes.
The real story isn't whether Max will scrub your toilets by 2030. It's that Meta is building a physical platform to train AI systems in real-world environments, which means they're solving for the infrastructure requirements before the robots work reliably. Think about what happened with electric vehicles: charging stations became a selling point years before EVs dominated the market. Early adopters paid premiums for homes with 240-volt garage outlets.
Now imagine the home features a general-purpose humanoid might require. Doorways wide enough for a 106-pound robot to navigate without damaging frames. Dedicated 240-volt charging stations (those robots need serious power). Reinforced flooring in high-traffic paths. Clear sight lines for navigation sensors. None of this exists in today's building codes, but if Meta and competitors like Tesla's Optimus push humanoids into even 5% of households over the next decade, "automation-ready" could become the new "smart home."
The mortgage angle: appraisers value features the market wants. In 2015, granite countertops added measurable value. By 2020, it was open floor plans and home offices. If household robots move from prototype to product, lenders may start factoring automation infrastructure into valuations—not because the robots work well, but because buyers expect the option.
Walmart's $6B Bet Reveals What Actually Works (Spoiler: Not Humanoids)
While Meta tinkers with a prototype that might pick up your socks, Walmart just committed $6 billion to expand Symbotic's warehouse automation across 25 U.S. regional distribution centers. This follows more than a decade of collaboration and comes with $125 million in new R&D for picking, racking, and inventory flow. Symbotic's systems store cases, move inventory, pick goods, and build outbound loads—specialized tasks performed by purpose-built machines, not general humanoids.
The timing is pointed. A Wall Street Journal report detailed Walmart's automation headaches: cartons the machines can't handle, robots that break down too often. Walmart's response was essentially "new technology is never perfect," then they doubled down with six billion reasons they believe in specialized automation over flexible humanoids. Amazon has deployed more than one million robots using the same philosophy: build machines for specific tasks, not android butlers.
This matters for real estate because specialized automation creates different job markets than humanoids would. A humanoid future might eliminate warehouse jobs entirely. Walmart's actual approach creates demand for robot maintenance technicians, AI system programmers, and automation oversight roles—jobs that pay $55,000 to $85,000 and require proximity to the facility.
The neighborhood economics shift accordingly. Properties near Symbotic-equipped distribution centers aren't just near "warehouses" anymore. They're near automation hubs that employ skilled workers, which historically correlates with property value increases. The caveat: increased truck traffic and 24/7 operations, which can depress values for immediately adjacent properties while lifting values for homes 1-3 miles away with access to the job market but not the noise.
The Mortgage Connection You Didn't See Coming
Here's where two seemingly unrelated automation trends converge in your local housing market. Meta's humanoid research pushes home builders to consider future-proofing for in-home automation. Walmart's warehouse investments reshape the economic geography around distribution centers. Both create valuation questions lenders haven't systematically addressed.
Consider a home built in 2027 near a newly automated Symbotic distribution center. The builder includes wider doorways and charging infrastructure targeting future robot adoption (adds $8,000 to construction cost). The neighborhood sees an influx of automation technicians earning $70,000 (supports higher home values). But truck traffic increases 30% (depresses values for homes on main routes). How does an appraiser weight these factors when there's no comparable sales data for "robot-ready homes near automated warehouses"?
Lenders will need frameworks. Do automation-ready features count as value-adds like solar panels, or are they speculative like wine cellars (valuable to some buyers, irrelevant to most)? Does proximity to an automated distribution center get treated like proximity to a hospital (job center premium) or a traditional warehouse (industrial discount)? These aren't hypothetical questions when Walmart is deploying across 25 facilities and Meta is iterating on Max 2.
The practical impact for current homeowners: if you're within five miles of a major distribution center, track automation announcements. The Symbotic deal included a separate agreement that could bring systems to hundreds of Walmart stores, expanding the geographic footprint of automation-adjacent real estate. If you're building or renovating, wider doorways and dedicated electrical capacity cost little now but might matter in resale if household robots move from prototype to even modest adoption.
What Appraisers Will Actually Look For (Eventually)
Appraisers value features when they're common enough to affect marketability but rare enough to command premiums. That window typically opens when 15-30% of new construction includes the feature and resale buyers specifically request it. We're nowhere near that threshold for robot infrastructure, but the path is visible.
Likely near-term factors: Smart home integration that could support future robotics (Z-wave hubs, robust WiFi infrastructure, whole-home battery backup). Doorway widths of 36 inches or more, which accommodate wheelchairs now and robots later. Dedicated 240-volt circuits beyond the dryer and range. Open floor plans that facilitate navigation. These features already add value for accessibility and modern aesthetics; robot-readiness would be additional justification, not the primary driver.
For properties near automated warehouses, appraisers will likely adopt frameworks similar to data center proximity (job market premium, infrastructure concerns) rather than traditional industrial facility discounts. The Symbotic deal's $6 billion scale and multi-year timeline means these facilities will anchor regional employment for a decade-plus, which supports sustained property value effects rather than speculative bumps.
The wildcard is timing. If Meta or Tesla gets humanoids to even basic reliability by 2028-2029, adoption curves could accelerate faster than building codes and appraisal standards adapt. That creates a 2-3 year window where automation-ready features might command premiums from early adopters before becoming standard requirements that add no marginal value. Similar pattern to how home offices spiked in value during COVID, then normalized as they became expected.
The Two Futures Converging in Your Neighborhood
Meta's humanoid research represents the high-visibility, low-probability automation future: robots in every home, handling household tasks, requiring new infrastructure. Walmart's warehouse investment represents the low-visibility, high-probability reality: specialized automation in concentrated facilities, reshaping local job markets and traffic patterns. Both affect housing, but on different timelines and through different mechanisms.
For homeowners and buyers, the practical takeaway isn't to retrofit your house for a robot that doesn't reliably exist. It's to recognize that automation infrastructure and proximity to automated facilities are moving from science fiction to appraisal considerations. If you're building or renovating, future-proofing for flexibility (wider doorways, robust electrical, open layouts) costs little and serves multiple purposes. If you're buying near a major distribution center, research whether automation upgrades are planned—the Symbotic deal covers 25 facilities, but Walmart operates hundreds of distribution centers, and Amazon's million-plus robots are deployed across a similar footprint.
The mortgage industry will adapt as it always does: slowly, then suddenly, once enough transactions involve these factors that lenders need standardized approaches. We're in the "slowly" phase, where awareness matters more than action. By the time "robot-ready" appears in MLS listings without irony, the premium will have evaporated. The value accrues to people who recognize the shift early, not those who wait for certainty.
The Bottom Line on Automation and Home Values
Meta spent three months building a humanoid that can't reliably fold laundry. Walmart spent $6 billion on warehouse robots that occasionally break down but handle millions of cases daily. Neither is ready for prime time, but both signal where billions in capital are flowing, and capital flows reshape real estate markets before the underlying technology fully works.
For homeowners: monitor automation announcements affecting nearby distribution centers, and consider flexibility features in renovations that serve current accessibility needs while potentially supporting future automation. For buyers: properties marketed as "robot-ready" are likely overpriced for speculative features, but homes near newly automated warehouses may be underpriced if sellers and appraisers haven't factored in the skilled job market developing around those facilities. For loan officers: start conversations with appraisers about how to value automation infrastructure and warehouse proximity before you're scrambling to justify a comp adjustment on a deal that's already in underwriting.
The robots are coming—slowly, imperfectly, and not quite how anyone predicted. But they're coming with enough capital behind them that your next appraisal might need to account for them, whether they work or not.
You made it through an entire post about household robots without a single Jetsons reference—that deserves recognition. If you want more early warnings about trends that'll show up in appraisals before they show up in guidelines, subscribe to Well That Makes Sense at WellThatMakesSense.com and follow us on social. We'll keep tracking where the billions go, so you know where the value follows.
Just promise us you won't try to get a charging station comp-adjusted until at least 2029.
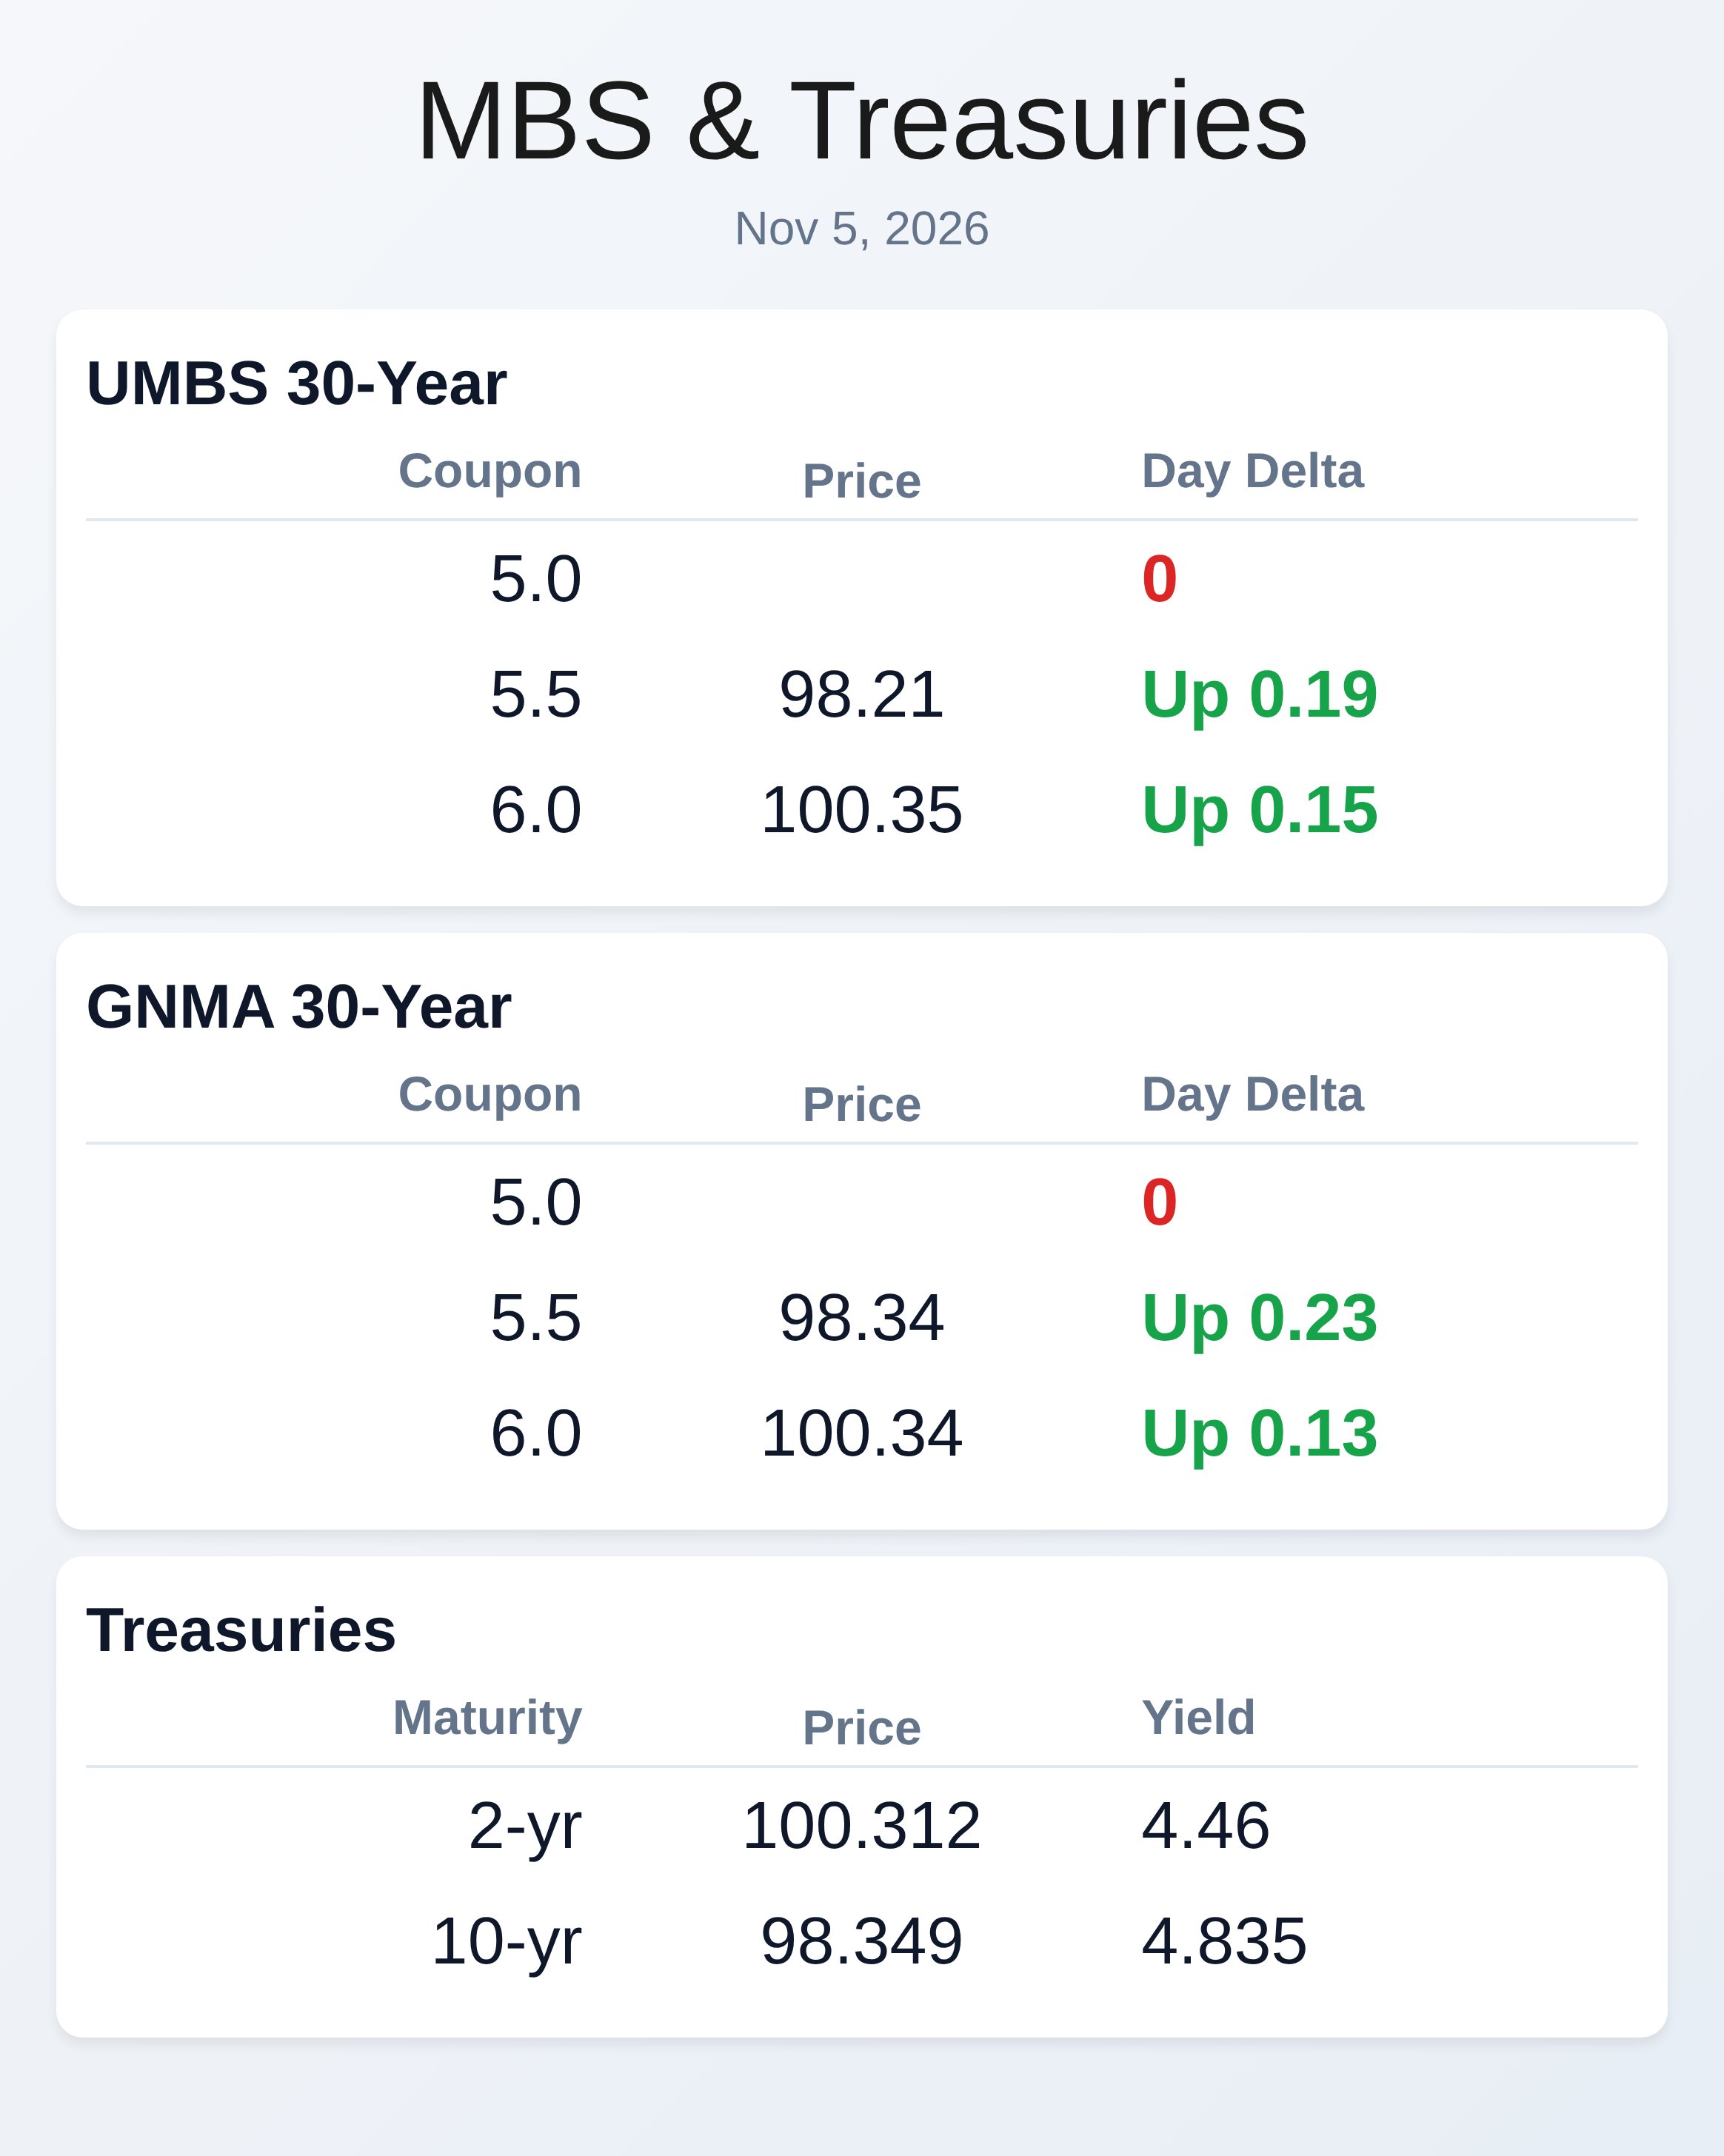
November 5, 2026
RECENT ARTICLES


My Reading Notes for “Invisible Selling Machine” by Ryan Deiss
🎯 The Ultimate Sales Weapon 🎯 You’re a pro at selling—but what if you could multiply your efforts without multiplying your workload? Invisible Selling Machine by Ryan Deiss gives you the tools to [...]
Mortgage Today 10/09/24 – Antitrust Case Against Google Drags Tech, Bonds Weak Ahead of CPI
Wednesday - October 9, 2024 UMBS on the wrong side of up on the open. Down 6 bps. Stock futures down 3 points. Stocks are lower as the Federal Government considers an antitrust [...]
Mortgage Today 10/08/24 – Bond Market Stabilizes After NFP, Mortgage Payments Hit Record High
Tuesday - October 8, 2024 UMBS pretty flat on the open - up 2 bps. Stock futures up 21 points. Friday's NFP gave the bond market a solid whack, sending yields quickly higher. [...]
Article Archive

TAGF3
All thoughts have power, but thoughts in combination with strong emotion are the most powerful. A majority of your thoughts, then, have no great attracting power. They are more of less maintaining what you have [...]
LOA
“The law of attraction and it’s magnetic power reaches out into the universe and attracts other thoughts that are vibrationally like it ....and brings that to you. Your attention to subjects, your activation of thoughts, [...]
Silence is Power
Professional negotiators have said that they can generally tell the outcome of negotiations fairly early on by "Whoever has less endurance for silence - loses."
Which of Cialdini’s Principles can make you Influential for 100 years?
Whether we like it or not, much of our life experience is determined by our ability to influence other people. Whether it's inspiring them to do more, or persuading them to do what we [...]