Loading...
HOME2023-01-22T13:43:33-07:00

“Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (AM) - 11/11/26 {{catlist}}
November 11, 2026
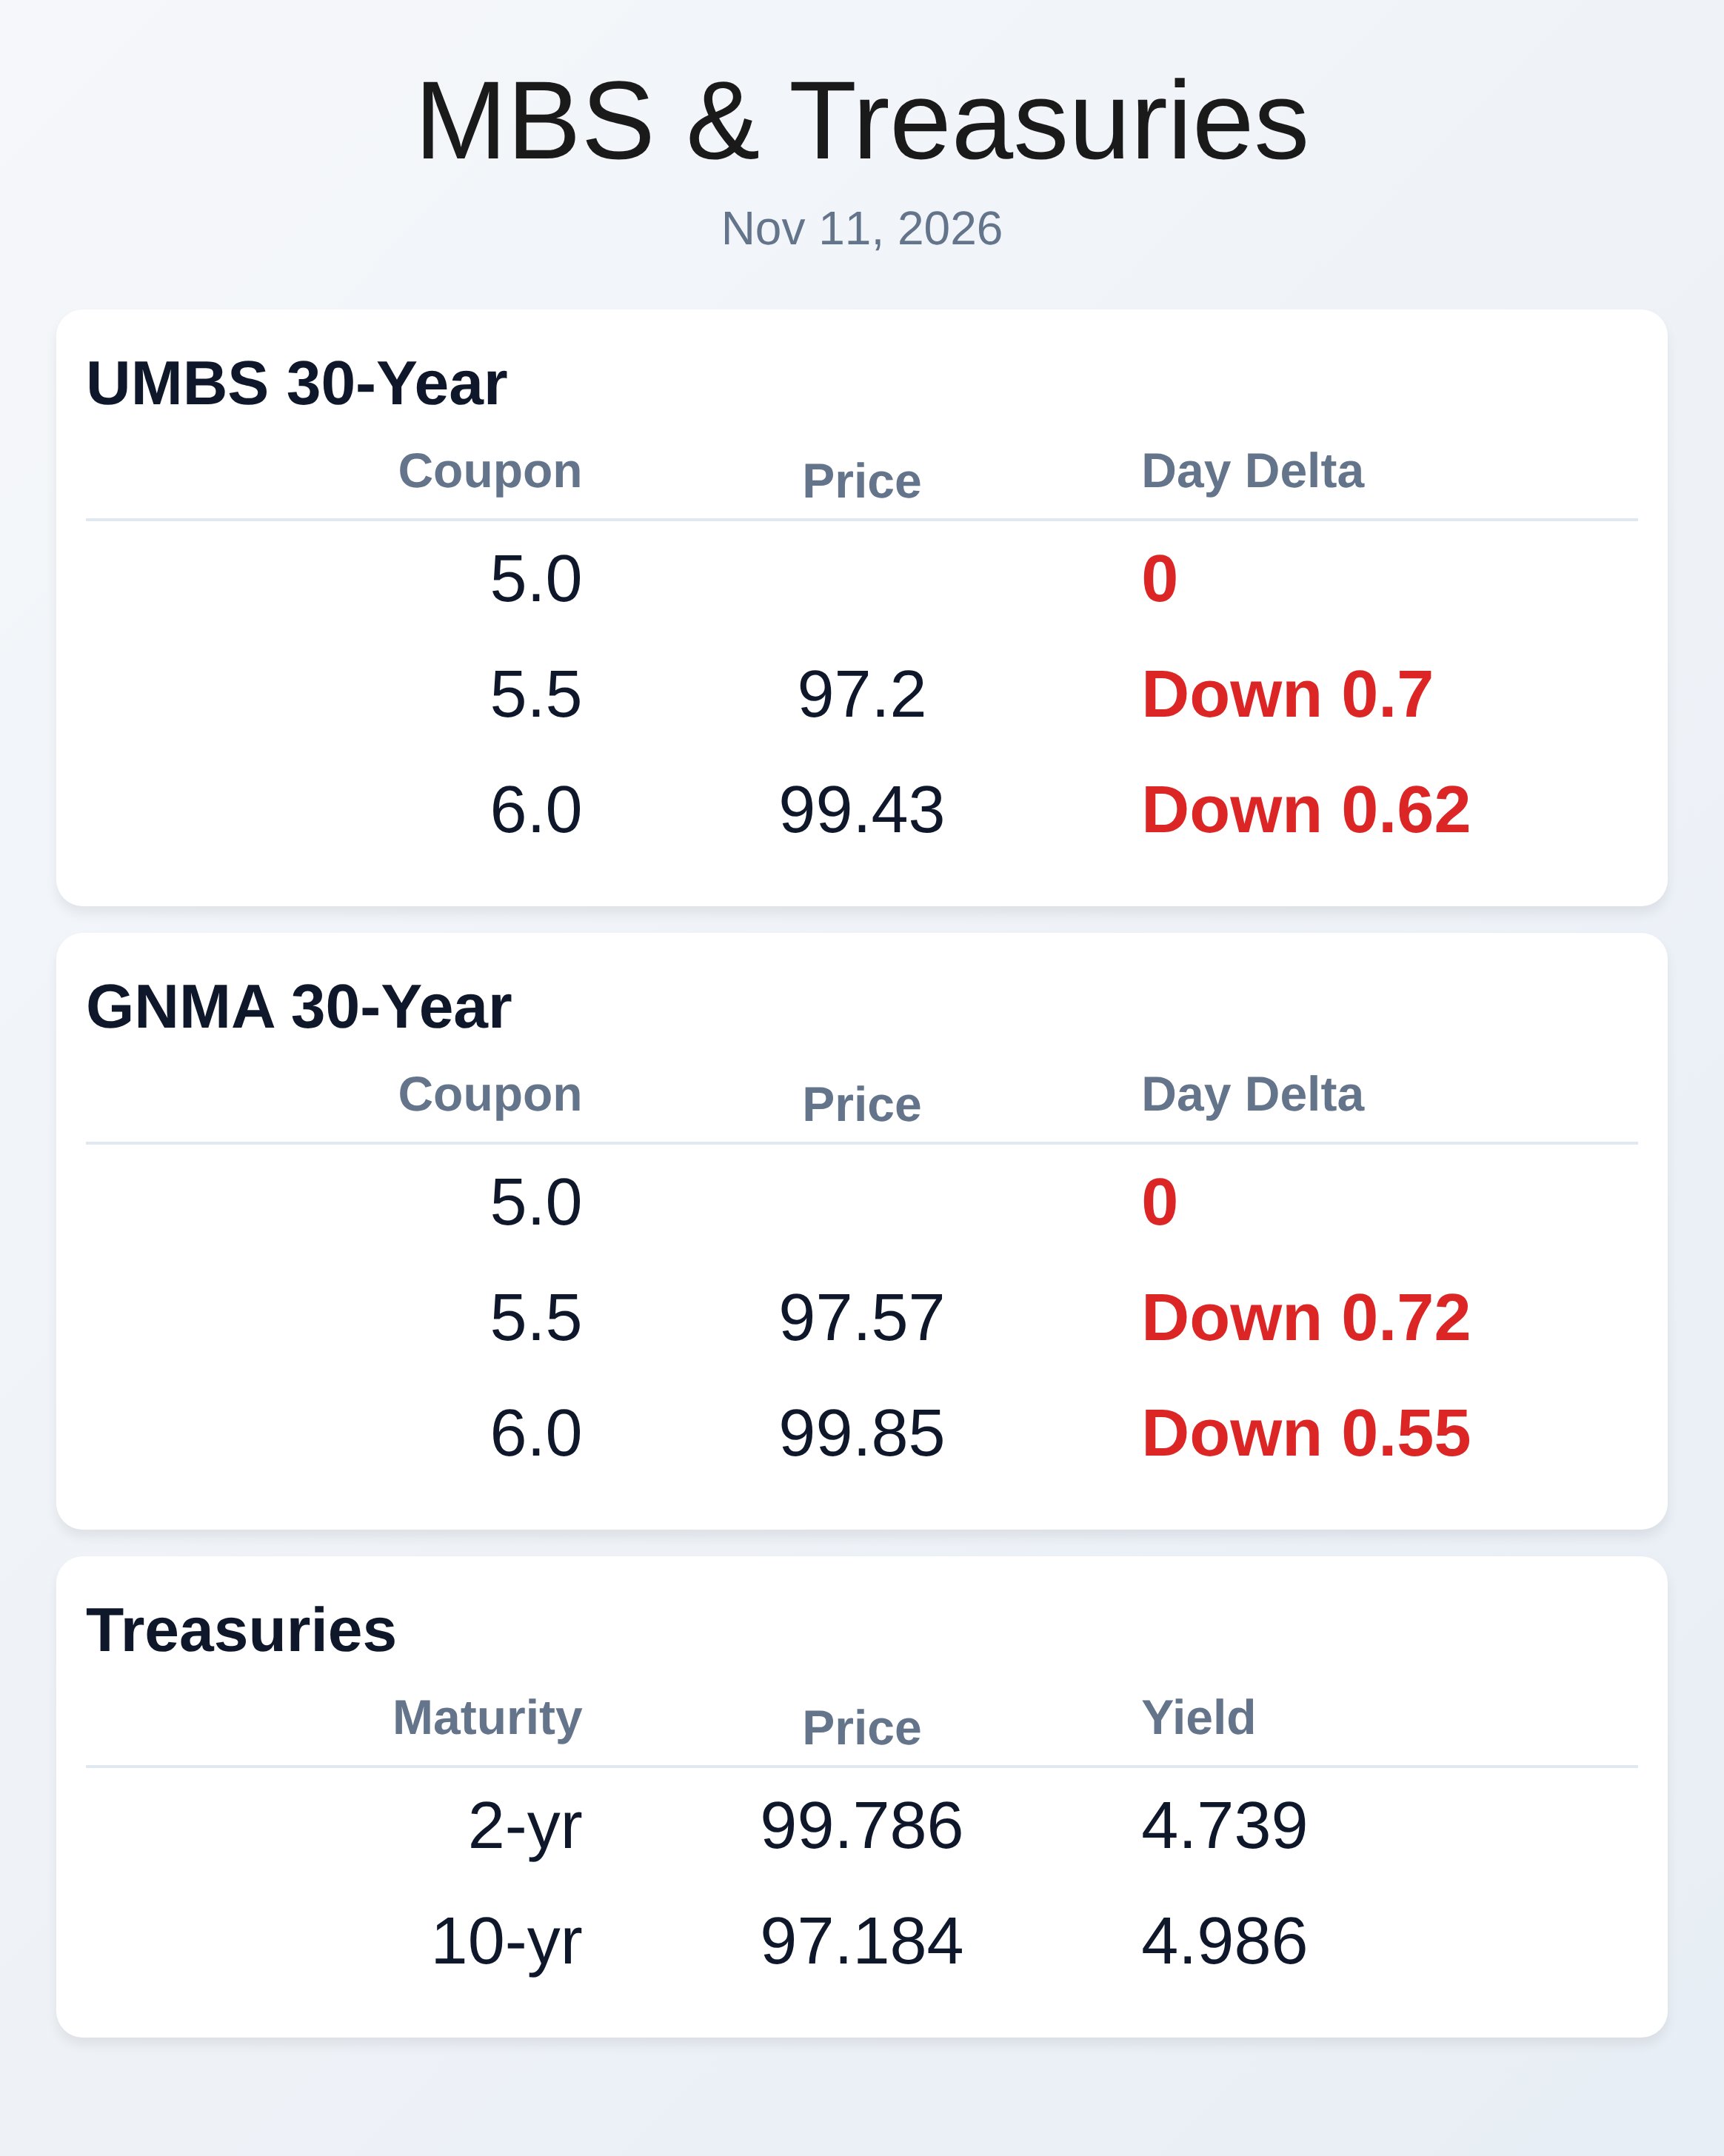
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 11/11/2026** Bonds are catching their breath after Tuesday’s hotter CPI (+0.4% headline, +0.3% core) revived rate-hike odds and pushed the 10-year back toward 5.00%. UMBS prices slipped on the print, with production coupons lagging Treasuries as volatility picked up and liquidity thinned into the holiday. With the bond market closed today for Veterans Day, lenders should expect limited or static rate sheets until trading reopens. Near term, auction supply and Friday’s PPI will steer the next leg. Bigger picture, last week’s five-week rally bent but didn’t fully break. Ginnie Mae remains the growth engine: it’s 42% of agency issuance year-to-date and reached 47% in October as FHA/VA outpaced conventional. That tilt matters for pipelines and servicing, given slower seasonals, slightly higher delinquency sensitivity, and cash-flow timing. VA volume deserves a nod today: zero-down remains a powerful tool, even as affordability tightens. Prepay speeds softened again in October, reducing convexity risk but stretching MSR cash flows. Expect investors to keep favoring specified pools with cleaner VA/FHA attributes. The 10-year’s round-trip near 5.00% has been fueled by hawkish Fedspeak (Waller opened the door to a December move), hotter CPI, and soft auction demand. Real yields remain elevated, keeping mortgage spreads sticky even when Treasuries rally. Oil’s retreat helped briefly, but the inflation trend still rules the tape. Until core inflation convincingly cools, the market will fade rallies on strong data and thin liquidity days. Translation: volatility remains a feature, not a bug. Origination mix keeps shifting to where execution lives. ARM share climbed to 17%—the highest since 2019—as buyers trade rate for payment relief and future refinance optionality. HELOCs remain ascendant on record tappable equity, giving lenders a durable recapture lane while first-lien refi incentives stay scarce. Non-QM grows as product fit, but execution discipline is paramount; bid/ask and pool sale risk can erase thin gains. Credit-score modernization is here too: VantageScore 4.0 vs. FICO 10T choices carry pricing, hedging, and investor-acceptance implications. Housing demand remains rate sensitive: contract signings fell to a record-low October pace, even as inventory improved and asking prices edged down. Competitive pressures are shifting to cash-to-close, not just rate. That’s why programs like Zillow’s FHA down-payment assistance (forgiving second) matter—they change the math on borrower eligibility and lender win rates. Expect more lenders to pair buydowns, DPA, and ARMs to keep purchases moving through year-end. Execution and education will separate winners. Playbook for today: with markets closed, focus on file quality, pricing exceptions discipline, and Monday’s pipeline posture. For VA and FHA pipelines, recheck AUS after CPI and confirm MI/DPA math still appraises cleanly. For HELOCs, compress cycle time—speed is winning share. And prep talking points now for Friday’s PPI and next week’s refunding supply, when rate sheets will need quick lock decisions. **Locking vs Floating** Post-CPI, the path of least resistance is choppy and upward for yields, with rallies prone to fade on strong data or supply. If recent improvements meet borrower goals or price exceptions are stacking, bias to lock on strength rather than gambling into PPI and next week’s auctions. Floating only makes sense with tight triggers, clear milestones, and minimal fallout risk. Production coupons are underperforming on volatility—assume headline sensitivity remains high. In short: protect wins; don’t chase dimes into data. **Today's Events** - Veterans Day: U.S. bond markets closed; rates likely static until trading reopens - No major economic releases scheduled; next key data is Friday’s PPI and University of Michigan Sentiment Subscribe free at WellThatMakesSense.com to get this in your inbox each morning.

Market Data
Mortgage Today (PM) - 11/10/26 {{catlist}}
November 10, 2026
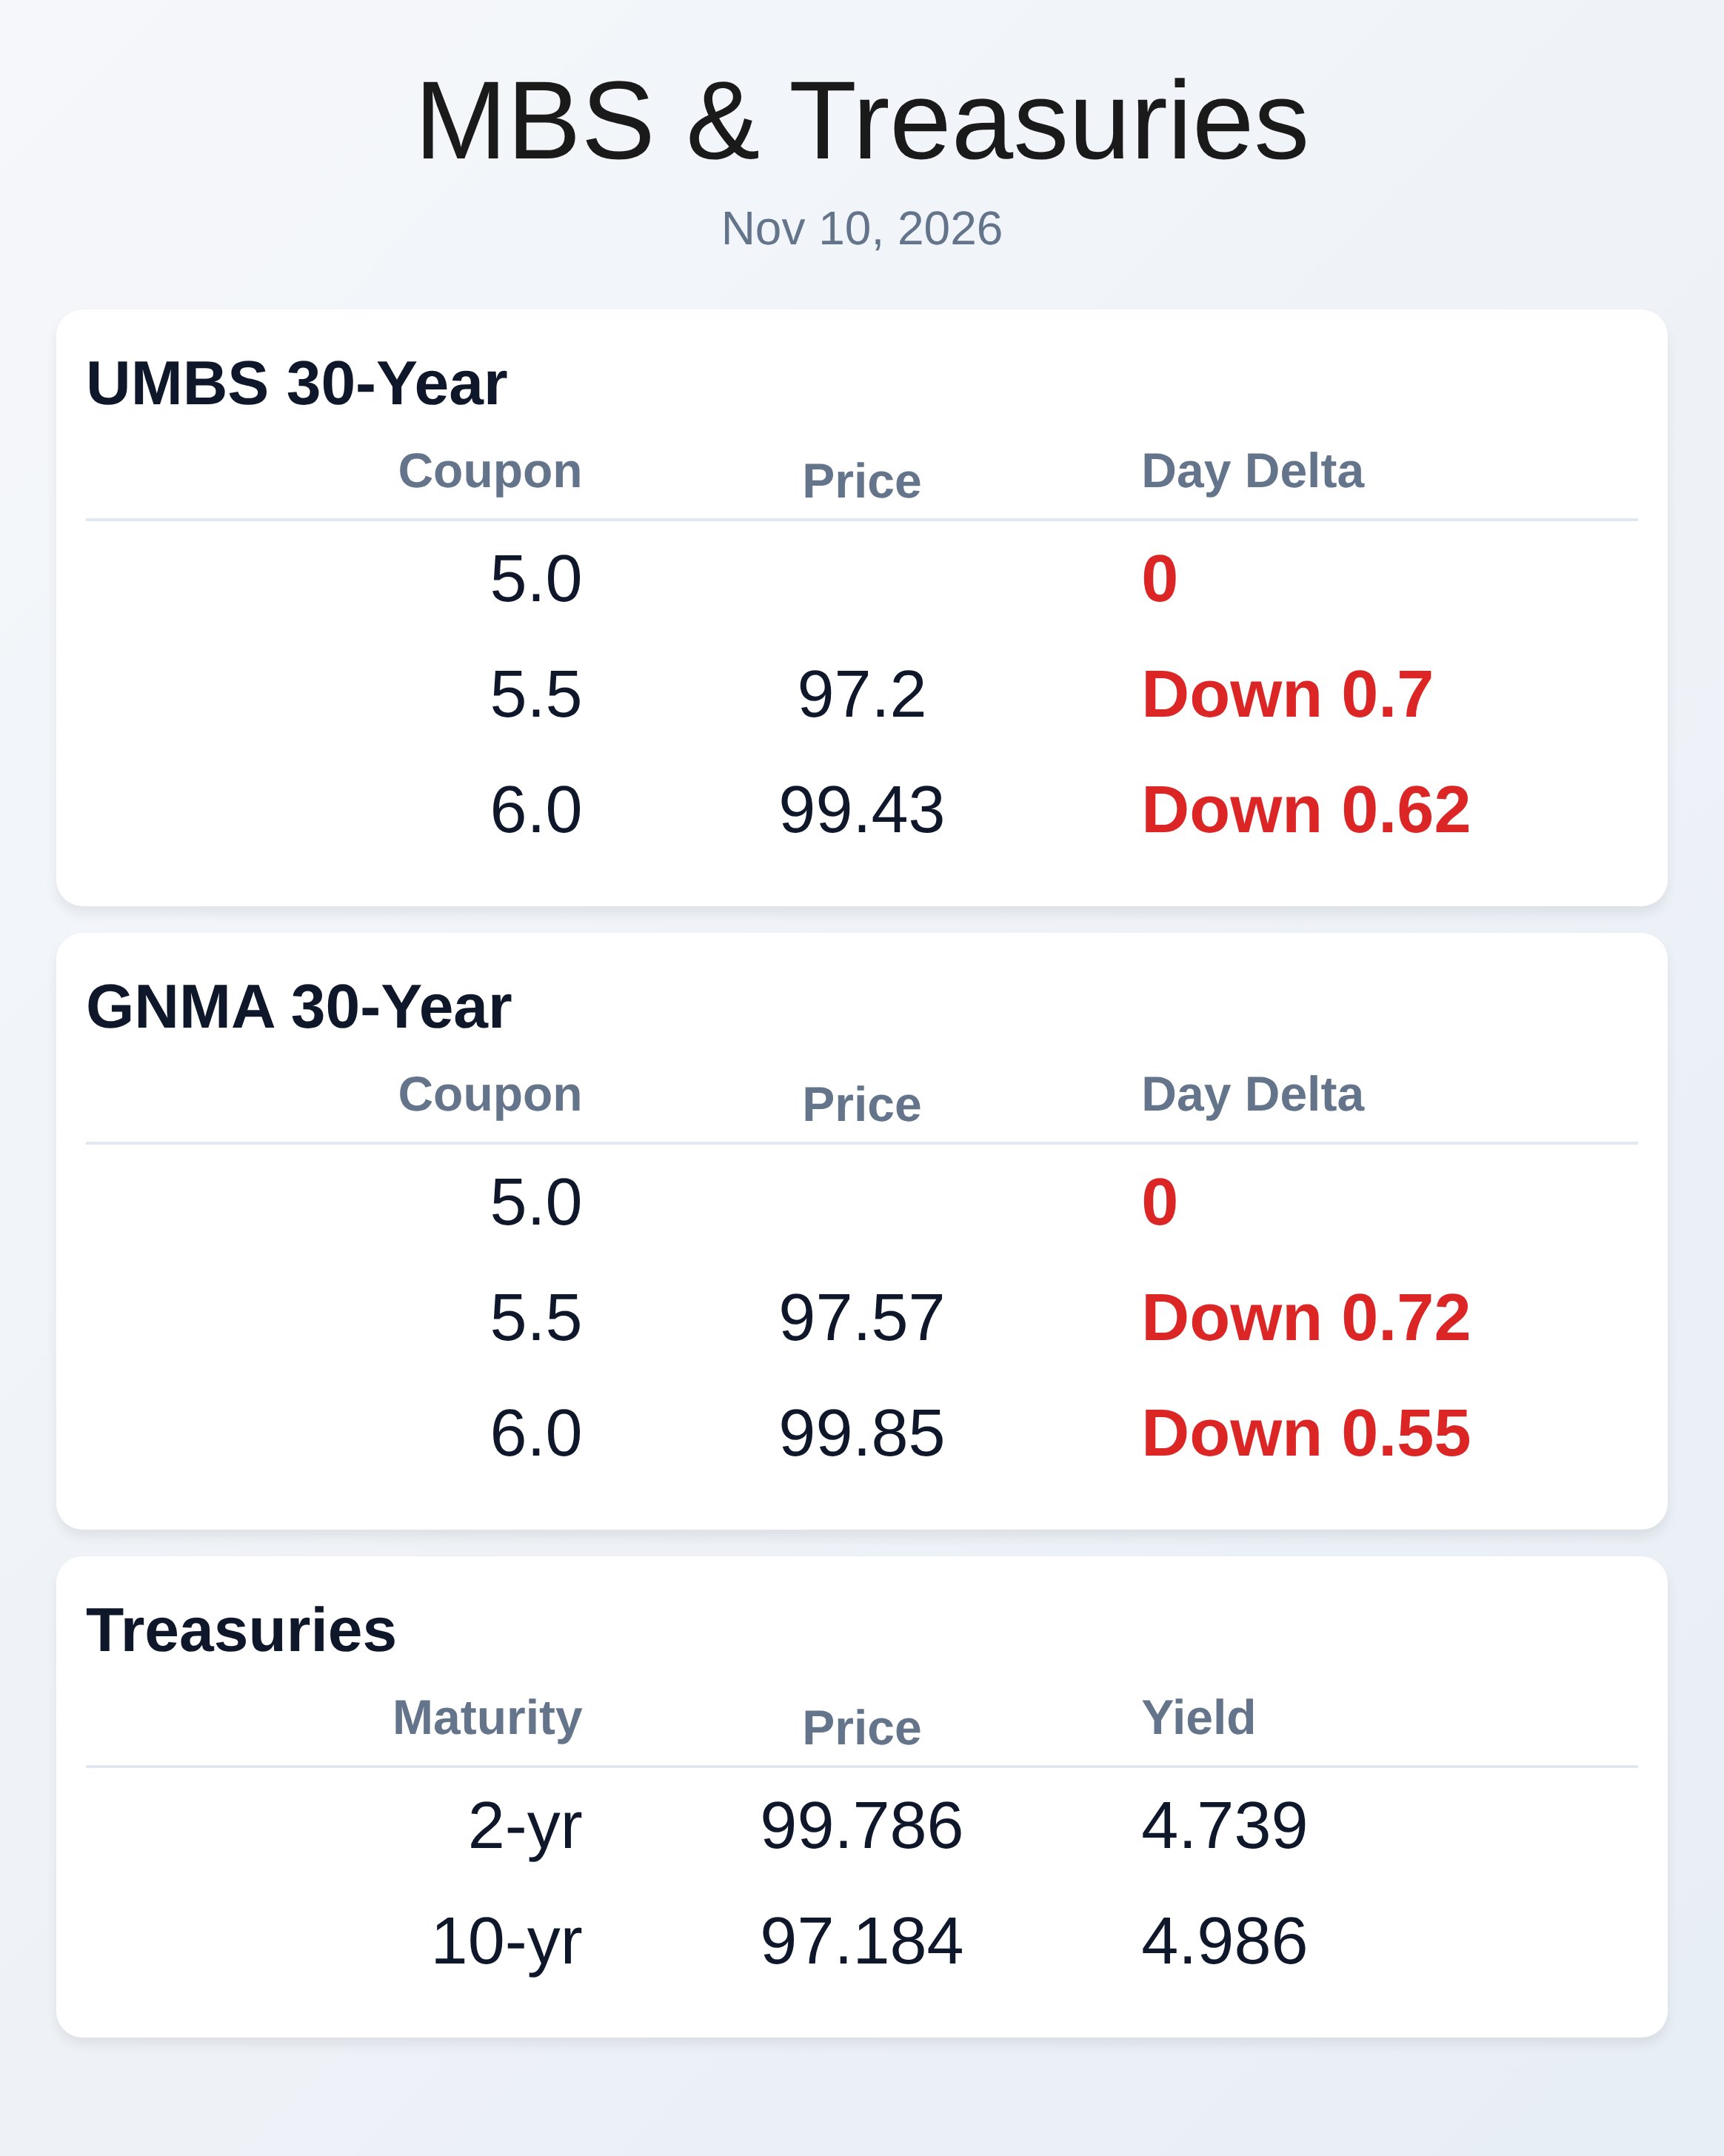
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 11/10/2026** Hotter CPI ended the early‑November bond rally, sending mortgage bonds and rates sharply the wrong way. Traders shed the “tech-jitters” safe‑haven trade and repriced for more Fed restraint. The move resets near‑term momentum and puts the recent downtrend in rates at risk. Volatility is elevated into the mid‑week holiday. Expect choppy price action around liquidity pockets. UMBS led the downturn as front‑end Treasury yields surged on the inflation surprise. By the close, 30‑year UMBS 6.0 fell 62 ticks to 99.43, while the 10‑year Treasury yield jumped roughly 10 bps to 4.98 percent. Losses were broad across coupons and GNMA stacks, with Ginnie 6.0 down 59 ticks. Fed‑funds futures nudged higher for December hike odds, reflecting the stickier inflation profile. Bid/ask and liquidity widened intraday before stabilizing late. Context matters: last week’s rally rested on AI/tech credit fears and slumping oil, not on softer inflation. With that cover fading today, the market refocused on the Fed’s inflation mandate. A mid‑week holiday can distort flows, so follow‑through may be uneven. A durable trend reversal likely needs either renewed tech stress or unequivocally softer inflation data. Until then, respect the range and trade defensively. On the origination front, modest rate relief into early November didn’t lift activity much. MBA data showed purchase apps slipping again, while Mortgage News Daily’s rate index hovered in the low‑7s (about 7.30–7.37 percent). Adjustable‑rate share pushed to a yearly high as borrowers hunt payment relief. Turn times and pricing discipline matter more than ever with secondary spreads still sensitive to volatility. Expect intraday reprice risk to stay lively. Servicing strategy remains pivotal as equity‑driven refis dominate what little refi volume exists. ICE estimates homeowners hold a record $17.5 trillion in tappable equity, yet servicers retained only 27 percent of refinancing borrowers last quarter. Cash‑out transactions are the main runoff driver. Lenders with strong database monitoring, HELOC/cash‑out options, and timely outreach will win more of that business. Housing remains a tale of leverage, not lift. Inventory has improved and buyers are negotiating more, but pending sales and contract signings continue to lag. Payments rose ~13 percent year‑over‑year even with largely flat prices, keeping affordability strained. For originators, that favors precise structuring: concessions, buydowns, and ARMs tailored to borrower cash‑flow constraints. **Locking vs Floating** Today’s CPI upside puts the recent rate rally at risk, so near‑term closings should favor locking on morning strength and avoiding late‑day whipsaws. Tactical floaters need tight triggers (e.g., 10‑year holding below 4.93–5.00 percent) and a willingness to lock quickly on adverse moves. A sustained leg lower in rates likely requires fresh downside surprises in inflation or renewed tech/AI credit stress. Expect elevated intraday volatility around the mid‑week holiday and data headlines; keep pipeline hedges snug and be selective with premium pricing. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change |

Market Data
Mortgage Today (AM) - 11/10/26 {{catlist}}
November 10, 2026
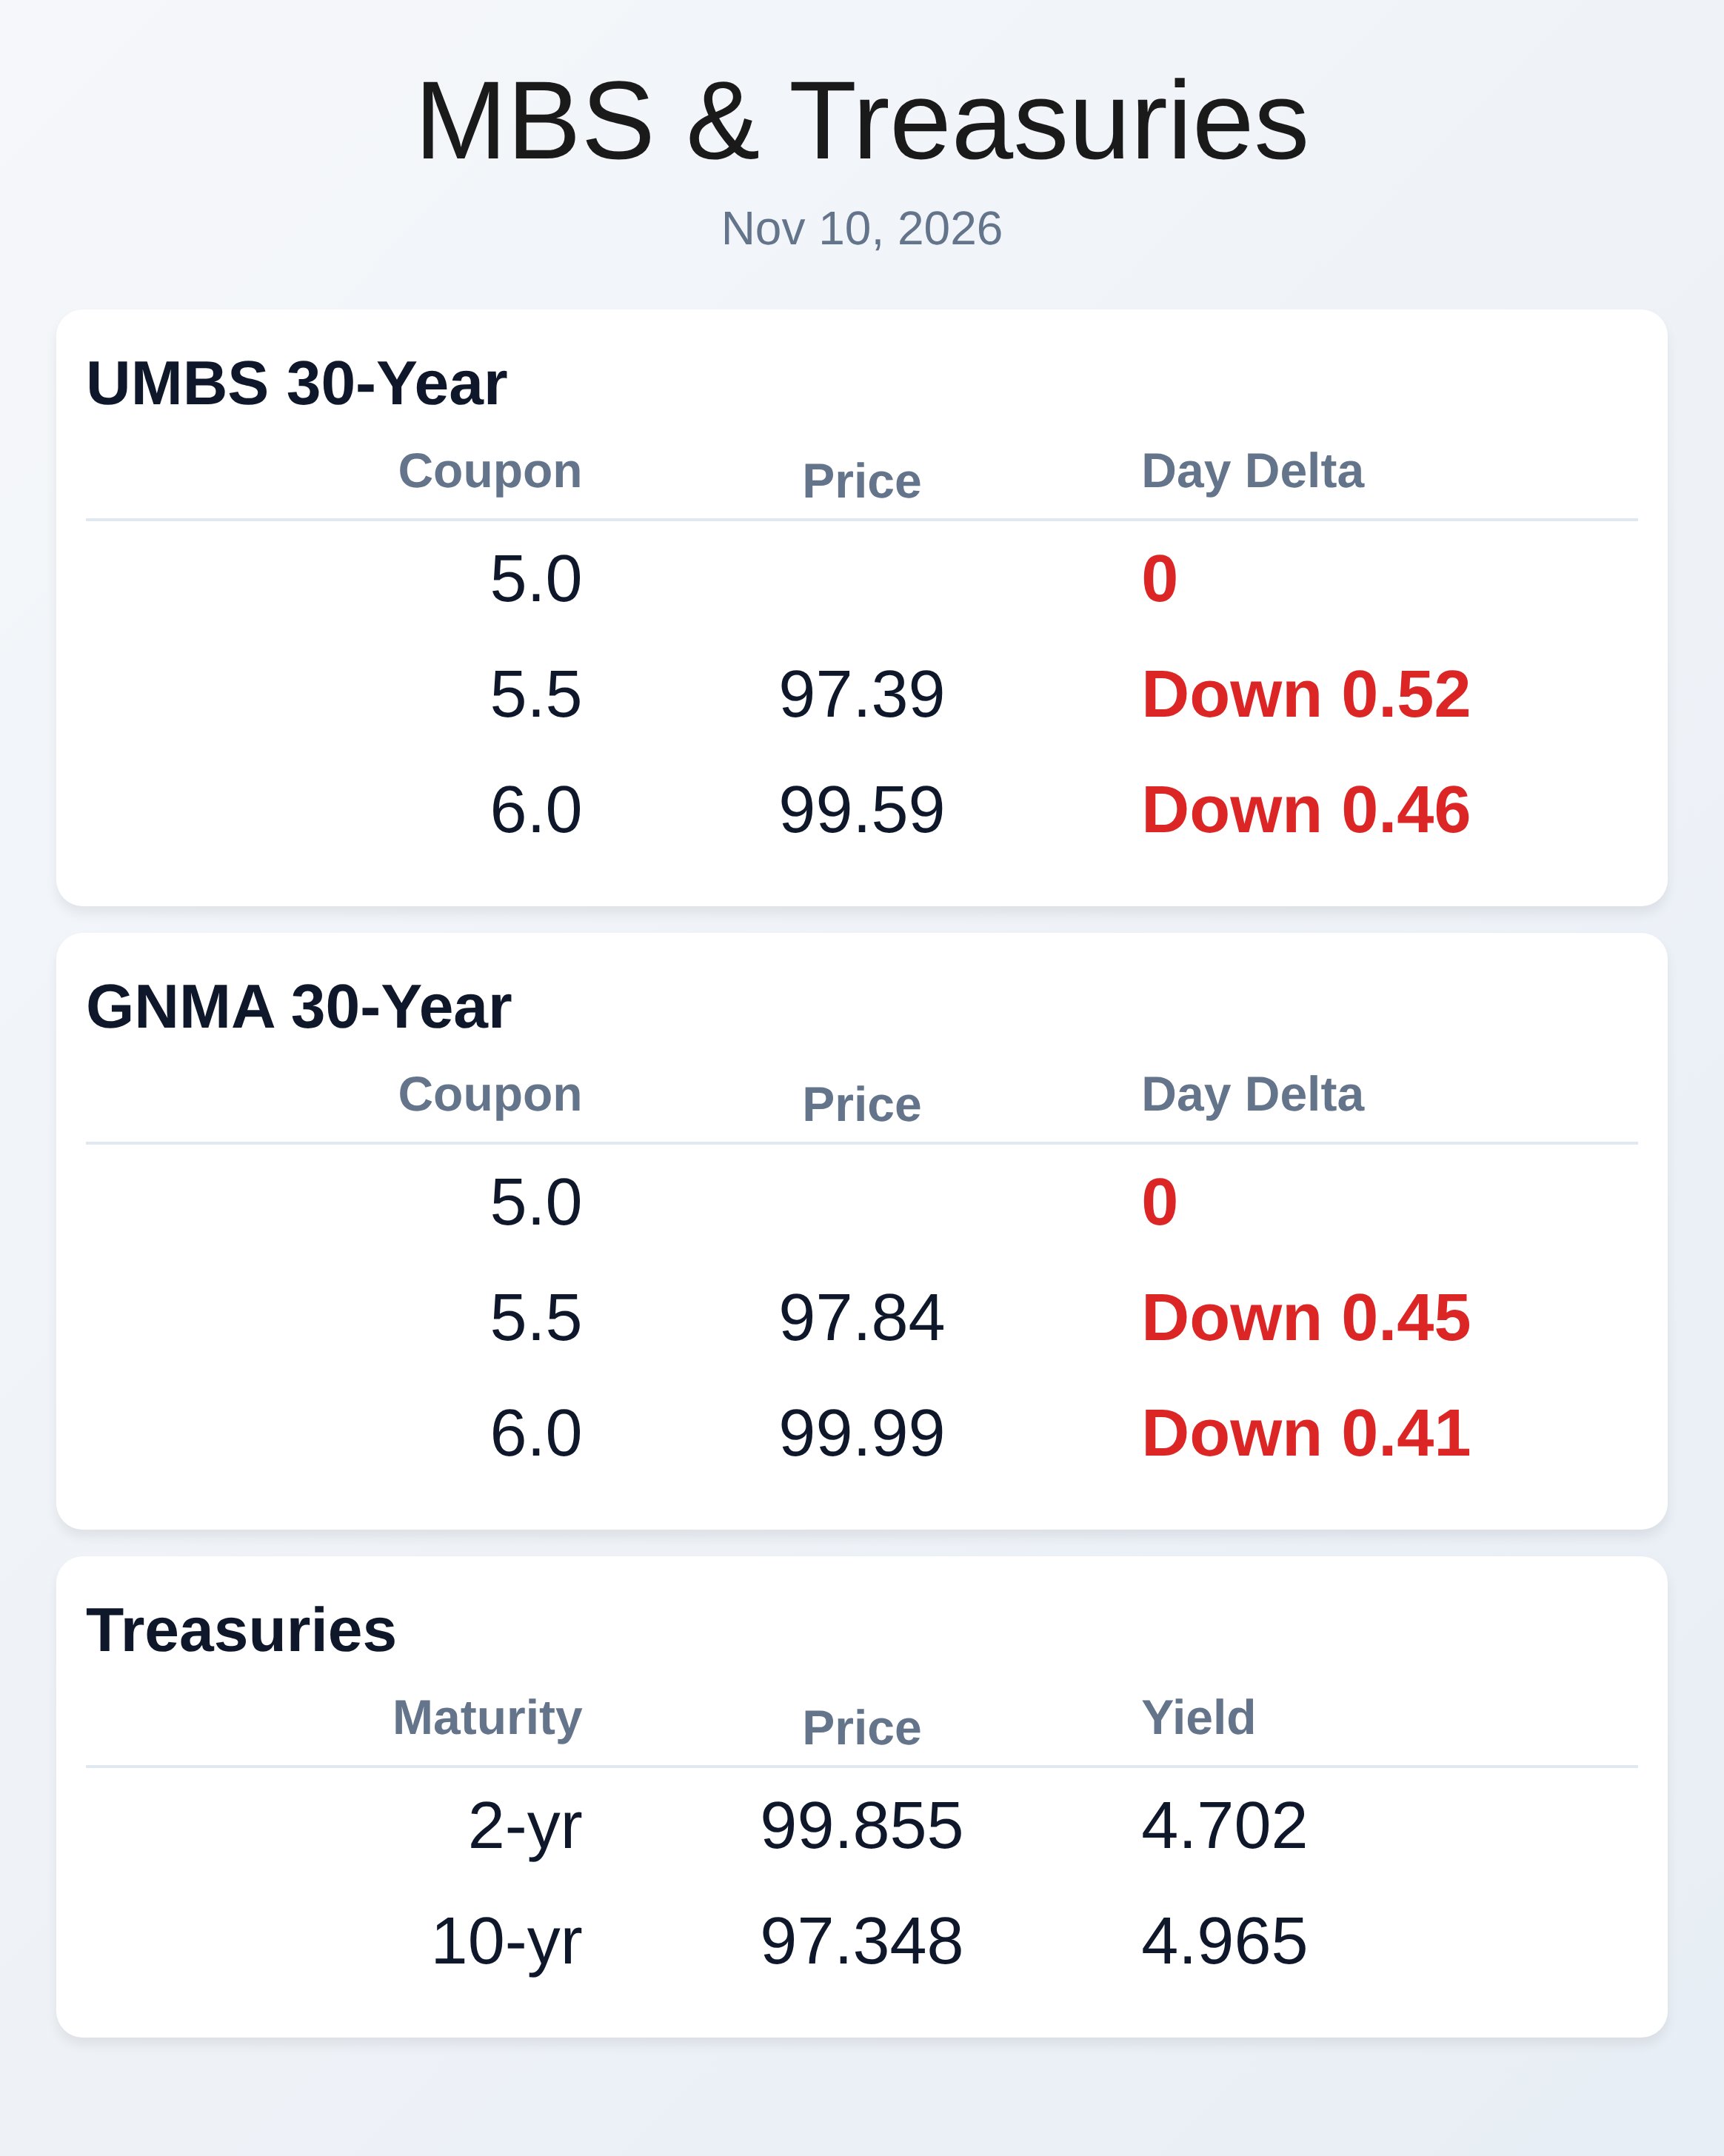
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 11/10/2026** Hotter CPI slammed bonds this morning, with core +0.3% m/m (vs. 0.2% est) and headline +0.4% (vs. 0.3% est) pushing the 10-year back toward 4.90–4.95%. UMBS prices slipped on the print as Fed Governor Waller backed a December hike and said he’d support a larger move if inflation re-accelerates. Rate sheets face renewed pressure after last week’s relief. Markets now lean more decisively toward a December move while watching how much of today’s weakness passes through to primary mortgage pricing. Expect intraday volatility around the 10-year auction. The backdrop remains whipsaw volatility: an AI-led equity selloff and a sharp oil drop briefly rekindled a flight-to-quality, pulling the 10-year below 5.0% late last week. That rally stalled as tech stabilized and policy hawks reasserted the inflation fight, leaving MBS lagging Treasuries on spread. With convexity still a headwind, production coupons haven’t fully captured the Treasury rally. For secondary teams, that means two‑sided risk into auctions and data. On the mortgage tape, prepayments slowed in October (Ginnie speeds -14.8% m/m; conventional -9.2%), and refinancing incentives remain scarce with the modeled par rate still near 7%. ARM usage continues to climb (October locks ~17%) as borrowers hunt monthly savings. GNMA liquidity remains orderly, but mid-coupon UMBS/GNMA 5.0–6.0s offer the best relative value if volatility moderates. Expect servicing-heavy names to benefit near-term from slower speeds despite today’s rate pop. Origination flow is mixed: MBA apps dipped last week (purchases -2% w/w; -19% y/y), though TransUnion’s Q2 showed originations +12.8% y/y with HELOCs +20.3%. Competitive dynamics are shifting—Zillow Home Loans’ FHA down-payment assistance (a 0%/no‑payment subordinate forgivable after five years) raises the bar on borrower offers, not just rates. LOs should lead with total-cost solutions (buys, ARMs, buydowns, HELOCs) and be ready to counter real-time with fully priced scenarios. Pipeline hedgers face familiar “rally fades/risk lingers” math: a further rate rise widens MBS basis; a bond bid shortens duration and forces hedge trims. Keep lock desks nimble into supply and data, and prioritize execution where investor appetite is deepest in higher coupons. Explain rate-sheet moves proactively—especially around auction tails and CPI‑driven reprices—to reduce concession creep. Housing demand is still constrained: October contract signings fell 17% y/y to a record low for the month, even as active listings rose 7.4% and median asking prices eased 2.2%. Cancellations were steady at 7.8%, but fewer fresh listings (-7.5% y/y) limit true inventory churn. Translation: tighter pipelines, longer cycle times, and more rate sensitivity per file. Focus on turn-times, lock discipline, and cost-to-manufacture. **Locking vs Floating** With the CPI miss and a 10-year auction on deck, bias tilts toward locking on day-of-closing and short-horizon loans; float only if you have cushion, time, and a defined stop. The 10-year’s 5.00% area remains a key pivot—failed rallies there have reversed quickly. Recent bond strength was tech/oil driven, not a fundamental disinflation shift; treat rate dips as tactical. Be ready for headline whipsaws and negative reprices through the auction window. Take wins early if pricing meets borrower goals. **Today's Events** - October CPI: headline +0.4% m/m; core +0.3% m/m - U.S. 10-year Treasury auction (1:00 PM ET) - Fed speakers: Waller, Logan, Schmid - NFIB Small Business Optimism (AM) - Wholesale Inventories (PM) Subscribe free for daily brevity at WellThatMakesSense.com.

Market Data
LATEST ARTICLES

RECENT ARTICLES

Is there a “More Worried”

December 12th, 2020|Money|

I love lessons in perspective - and Yuval Noah Harari (author of bestseller "Sapiens" - a book so popular that spellcheck recognizes "Harari") delivered a great one. Is a World Leader MORE worried about [...]

Article Archive
Subscribe

Send me some brain food

Go to Top