“Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.
I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.
I still remember how it started for me. It started in June of 2008. After 11 years …..Click to continue
October 27, 2026
October 27, 2026
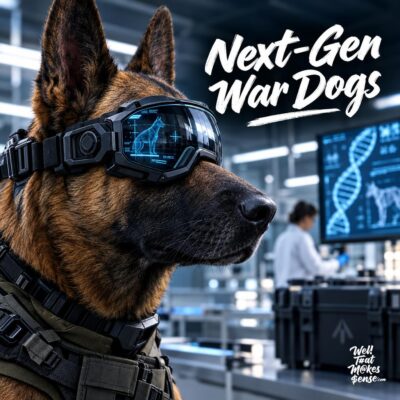
Gene-Edited War Dogs in Body Armor: The $1.2 Billion Startup That Sounds Like Science Fiction
You probably didn't have "cloned war dogs in high-tech armor" on your 2027 bingo card, but here we are. Two billionaire tech founders just launched a startup that wants to genetically engineer elite military dogs, clone them, and outfit them with advanced battlefield equipment. It sounds like a rejected screenplay, except it's real, it's already raised $200 million, and the first gene-edited puppies are expected in about two years.The Players Behind This Wild Idea
Warhound is the brainchild of Ben Lamm, who founded Colossal Biosciences (the company working to bring back woolly mammoths), and Palmer Luckey, the Oculus VR creator who now runs Anduril, a defense technology company. Lamm brings the genetic engineering expertise; Luckey brings the military hardware and software. Together, they've convinced investors that genetically optimized dogs in sensor-laden armor represent the future of military and law enforcement operations. The company is already valued at $1.2 billion before it's produced a single animal. That valuation tells you how seriously the defense and biotech worlds are taking this concept, even if it sounds like something from a Marvel movie.How the Technology Actually Works
The process starts with collecting cells from proven working dogs—military dogs, police K9s, and first-responder animals that have demonstrated exceptional performance in real situations. Warhound's scientists will edit the genomes of these cells to remove genes associated with inherited health problems and potentially add genes that enhance desirable traits. Then they'll use cloning technology to create embryos that develop into puppies carrying those modifications. This isn't hypothetical science; the cloning part is established technology that's been used on pets and livestock for years. The gene-editing component uses CRISPR and related tools that are now standard in biotech labs. What's new is applying both techniques specifically to create optimized working dogs at scale.The Health Improvements Come First
The initial gene edits will target inherited diseases that plague many dog breeds, especially the larger breeds commonly used in military and police work. Hip dysplasia, a painful joint condition, affects roughly 20 percent of German Shepherds and Belgian Malinois—the breeds most commonly used as working dogs. Other targets include heart conditions, certain cancers, and joint problems that force dogs into early retirement or cause chronic pain. Eliminating these conditions would genuinely improve animal welfare, extending working dogs' careers and quality of life. A military dog costs approximately $40,000 to $50,000 to acquire and train, so keeping them healthy and operational longer has real economic value beyond the moral argument. This is the least controversial part of Warhound's mission, and it's where the company will likely start.The Performance Enhancements Are Where It Gets Complicated
Once the health issues are addressed, Warhound plans to move into enhancement territory—editing genes to improve speed, agility, endurance, and olfactory capability. The company has mentioned potentially incorporating wolf genes to boost certain traits. Wolves can sustain running speeds of about 35 miles per hour and have scent detection abilities that exceed even the best dog breeds. They also have different pain tolerance and pack behavior patterns. This is where the technology shifts from therapeutic to enhancement, from fixing problems to creating capabilities that don't exist in current dogs. It raises questions about what we're creating and why. Are we making better tools, or are we creating animals that exist primarily to serve human military objectives in ways that might compromise their welfare?The Anduril Hardware Adds Another Layer
Palmer Luckey's Anduril isn't just an investor; the company will develop the physical and software systems these dogs will carry into the field. We're talking about advanced body armor designed specifically for canine anatomy, protective goggles that could include heads-up displays or low-light enhancement, and integrated sensor systems that feed battlefield awareness data to handlers and command centers. Current military dogs already wear some protective gear, but Anduril's track record suggests something far more sophisticated—think networked systems that turn each dog into a mobile sensor platform. The dog becomes both a biological operator and a piece of connected battlefield infrastructure. That integration could save human and canine lives by providing better situational awareness, but it also means these animals are being designed as weapons systems from the genome up.The Timeline Is Surprisingly Close
Warhound expects its first gene-edited puppies in early 2027—roughly two years from now. That aggressive timeline is possible because both the cloning technology and the gene-editing tools already exist and have been proven in other applications. The company isn't inventing new science; it's combining established techniques in a new context. After those first puppies are born, there will be years of training and evaluation to see if the genetic modifications translate into real-world performance improvements. A military working dog typically requires 18 to 24 months of training before deployment, so we're looking at operational animals around 2029 at the earliest. That's still remarkably fast for a technology that didn't exist as a company until 2026.The Potential Civilian Benefits Are Real
While Warhound's focus is military and law enforcement, the technology could have significant civilian applications. Search-and-rescue dogs that are healthier, have longer careers, and possess enhanced scent detection could save more lives in disaster scenarios. Detection dogs used in conservation work, at borders for agricultural inspection, or in medical settings for disease detection could all benefit from genetic improvements that make them better at their jobs and healthier throughout their lives. Guide dogs and service animals could be bred without the hereditary conditions that currently force many promising dogs out of training programs. If the technology proves safe and effective, and if it's made available beyond military contracts, the welfare and capability improvements could extend to working dogs across many fields.The Ethical Questions Can't Be Ignored
Creating animals specifically designed for combat roles through genetic engineering crosses lines we haven't crossed before. We've bred dogs for thousands of years, selecting for traits we wanted, but genetic engineering is more direct, faster, and capable of changes that wouldn't occur through traditional breeding. Are we obligated to consider the animal's experience when we design it to be more aggressive, to tolerate more pain, or to perform in ways that put it in greater danger? The animals can't consent to being created for these purposes. There's also the question of what happens to gene-edited dogs that don't meet performance standards or that are retired from service. Will they be adopted into civilian homes? Are there unforeseen health or behavioral consequences of the modifications? These aren't hypothetical concerns—they're questions that need answers before the first modified puppy is born.The Military Demand Is Clearly There
The U.S. military currently uses approximately 1,600 working dogs across all branches, with demand consistently exceeding supply. Training programs struggle to produce enough qualified animals, and many dogs wash out due to health problems or temperament issues. If Warhound can reliably produce dogs that are healthier, perform better, and last longer in service, the military market alone would justify the investment. Law enforcement agencies use thousands more K9s, and many face similar supply challenges. The $200 million in funding and the $1.2 billion valuation reflect investor confidence that this demand is real and that Warhound's approach can meet it. Whether that demand should be met through genetic engineering rather than improved breeding and training is a separate question, but the market clearly exists.What This Means for Genetic Engineering Broadly
Warhound represents genetic engineering moving out of the laboratory and into operational, real-world applications in a very visible way. Colossal Biosciences' work on extinct species is fascinating but abstract; gene-edited military dogs are concrete and immediate. If this succeeds, it will normalize genetic modification of animals for human purposes in ways that could accelerate similar applications elsewhere—agriculture, conservation, medicine, even pets. That's not inherently good or bad, but it's a significant shift. It will force conversations about regulation, oversight, animal welfare standards, and the limits of what we should do just because we can. The technology is moving faster than our ethical frameworks and legal structures, which is often how transformative technologies work, but it means we're figuring out the rules as we go.The Bottom Line on Gene-Edited War Dogs
This is simultaneously impressive, useful, and deeply strange. The technology could genuinely improve the lives of working dogs by eliminating painful inherited diseases and could enhance their capabilities in ways that save human lives. It could also push us into territory where we're creating sentient beings primarily as optimized tools for combat, with all the ethical complications that entails. The first gene-edited puppies will arrive in about two years, which doesn't leave much time for society to figure out how it feels about this or what guardrails should exist. The science is real, the funding is secured, and the market demand is clear. Whether this is a breakthrough in animal welfare and capability or a troubling step toward treating living beings as programmable hardware depends partly on how Warhound executes and partly on what values we decide to prioritize. What do you think—is genetically engineering working dogs for health and performance a genuine improvement, or does it cross a line we shouldn't cross?
October 26, 2026

RECENT ARTICLES

Mortgage Today (PM) – 05/05/26
WTMS Blog Today = What's up in Mortgage Today (PM) - 05/05/2026 Bonds staged a modest recovery today as oil prices stabilized and economic data came in near expectations, but mortgage-backed securities gained less than [...]
Mortgage Today (AM) – 05/05/26
WTMS Blog Today = What's up in Mortgage Today (AM) - 05/05/2026 Bond markets are getting hammered on the heels of escalation headlines that have spooked investors globally. The 10-year Treasury jumped to 4.42%, exceeding [...]
Mortgage Today (PM) – 05/04/26
WTMS Blog Today = What's up in Mortgage Today (PM) - 05/04/2026 War-related headlines hammered mortgage bonds as Iran escalated tensions in the Middle East, sending oil prices to their highest levels in weeks. The [...]
Article Archive

My Reading Notes for Discipline Equals Freedom by Jocko Willink
🚀 Face Your Fears, Step by Step 🚀 Every salesperson knows the feeling—fear of rejection, fear of failure. But what if you could step into that fear and turn it into fuel? In [...]
Mortgage Today 09/30/24 – Powell Speaks, Jobs Report Ahead & Bond Market Reaction!
Monday - September 30, 2024 UMBS continued their red run this morning, down 6 bps. S&P futures are down 11.75 points. US equity futures started the week on the backfoot after last week’s [...]
Mortgage Today 09/27/24 – Inflation Cooling, Spending Slows & Bond Markets Stabilize!
Friday - September 27, 2024 Finally in the green! UMBS were up 9 bps in the first hour of trading. Stock futures up 2.75 points PCE inflation data only wishes it could be [...]
Mortgage Today 09/26/24 – Jobless Claims, Durable Goods Beat, and New Home Sales Surge!
Thursday - September 26, 2024 Mortgage Backed Securities were down 13 bps on the open. S&P stock futures are up 45 points. Bonds were moderately stronger overnight, but all of the gains have [...]
My Reading Notes for Discipline Equals Freedom by Jocko Willink – Part 3
🚫 Stop the Slow Decline 🚫 Sales isn’t won in one battle. It’s a war of daily discipline. But how do you stay strong when comfort whispers in your ear? Jocko Willink’s Discipline [...]
Mortgage Today 09/24/24 – S&P 500 Hits 40th All-Time High Amid China Stimulus, Fed Rate Cuts Expected!
Tuesday - September 24, 2024 UMBS opened up 5 bps in early trading. S&P Futures up 6.75 points. US stock futures were volatile, while global equities rallied after China announced significant stimulus measures [...]
WTMS Blog Today = My Reading Notes for Discipline Equals Freedom by Jocko Willink – Part 2
⏰ Every Day is Monday ⏰ In sales, there are no weekends off. Jocko Willink’s Discipline Equals Freedom teaches you to embrace the grind, where every day is a fresh opportunity to [...]
Mortgage Today 09/23/24 – Fed Speakers, Yield Curve & Key Economic Data for the Week Ahead!
Monday - September 23, 2024 UMBS opened down 5 bps. S&P futures are up 8.25 points. Bonds were slightly weaker overnight with some additional selling in the opening hour. The S&P data has [...]