The Mortgage Flywheel: Why Your Best Sales Strategy Might Be Spinning You in Circles
Inside the industry’s most seductive trap—and how to escape before you’re too dizzy to close deals
Picture this: You’re pedaling harder than ever, watching your competitors cruise past you, wondering why all your effort isn’t translating into more closed loans. Welcome to the mortgage flywheel—the industry’s equivalent of a hamster wheel, except the hamster has a college degree and a CRM subscription.
Here’s the thing nobody tells you at your first mortgage sales training: the very system designed to create momentum can actually work against you. And right now, thousands of loan officers are trapped in it without even realizing they’re stuck.
What Exactly Is This Flywheel Everyone’s Talking About?
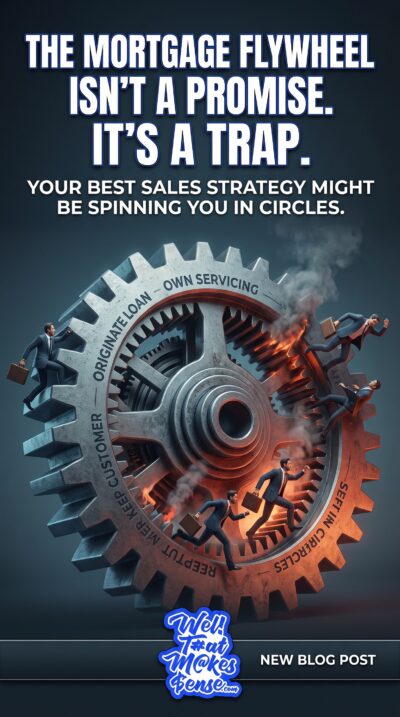
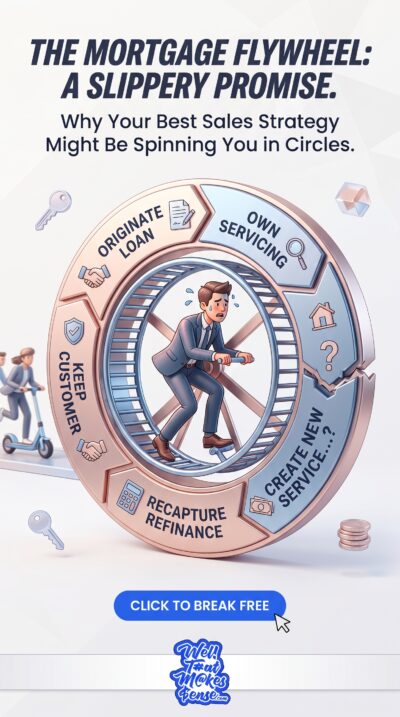
The mortgage flywheel is the industry’s golden promise: Originate the loan → Own the servicing → Keep the customer → Recapture the refinance → Originate a new loan → Create new servicing → Repeat. It sounds beautiful, doesn’t it? Like a perpetual motion machine that prints money while you sleep.
The big players—think Rocket Mortgage and PennyMac—have built empires on this concept. They originate your loan, service it for the next 30 years, send you birthday cards (okay, maybe just payment reminders), and when rates drop, they’re Johnny-on-the-spot with a refinance offer. It’s vertical integration at its finest, and it works brilliantly for companies with billions in capital.
Here’s where it gets interesting for you as a mortgage salesperson. The flywheel creates what finance nerds call a “natural hedge.” When rates rise and origination volume tanks, the servicing portfolio becomes more valuable because borrowers aren’t refinancing away. When rates fall and everyone’s scrambling to refi, origination business booms even though servicing values drop. One side picks up the slack when the other side stumbles. Beautiful symmetry, right?
Except there’s a catch. Actually, several catches. And they’re all wearing your face.
How the Flywheel Becomes Your Enemy
For individual loan officers and smaller mortgage shops, the flywheel doesn’t spin—it grinds. Here’s why:
First, you probably don’t own the servicing rights to your loans. Your company might, but you don’t see a dime when that borrower makes their monthly payment for the next three decades. You originated the loan, did the hard work, built the relationship, and then… crickets. Someone else is getting paid to maintain contact with YOUR client.
Second, even if your company owns the servicing, you’re not necessarily positioned to recapture that refinance. Maybe you’ve moved to a different company. Maybe that borrower moved to a different state. Maybe they’ve been getting monthly “special rate” offers from seventeen other lenders who bought their contact information. Your perfect flywheel just became everyone else’s opportunity.
Third—and this is the killer—the flywheel mentality can trap you in a scarcity mindset. You start thinking: “I need to close THIS loan because I need the servicing income because I need the future refi because…” Stop. You’re now making decisions based on a theoretical future transaction instead of serving the client in front of you RIGHT NOW.
The flywheel also creates what I call “relationship laziness.” You close the loan, pat yourself on the back, assume the servicing relationship will keep you top-of-mind, and then wonder why that client refinanced with someone else two years later. Spoiler alert: monthly payment reminders aren’t relationship building. They’re just… reminders that your client owes money.
The Capital Trap Nobody Mentions
Here’s what Karen Postiglioni nailed in her analysis: the real question isn’t whether the flywheel works—it’s whether it’s the best use of capital. For big lenders, maintaining massive servicing portfolios ties up enormous amounts of money in MSRs (Mortgage Servicing Rights). That capital has financing costs, hedging requirements, and liquidity needs.
For you as a salesperson, your “capital” is your time, energy, and mental bandwidth. Every hour you spend trying to maintain contact with past clients who are being serviced by someone else is an hour you’re not spending on new business. Every mental cycle you waste worrying about recapture rates is a cycle you’re not using to build your personal brand or deepen your referral relationships.
The MBA found that 78% of lenders were profitable with servicing included, but only 64% without it. That’s a meaningful difference—but it doesn’t tell you what return they earned on the capital committed to make that happen. Similarly, your “profitability” as a loan officer isn’t just about closed loans—it’s about return on invested effort.
Breaking Free: A Different Spin on Success
So how do you escape the flywheel trap? By recognizing that owning the MSR and maintaining access to the customer are separate decisions. This is the insight that changes everything.
You don’t need to own the servicing to own the relationship. In fact, some of the most successful loan officers I know have zero servicing rights but maintain incredibly strong client relationships through intentional, valuable touchpoints that have nothing to do with monthly payment reminders.
Start by shifting your mindset from “I need to capture the whole flywheel” to “I need to be the most valuable mortgage resource in my clients’ lives.” That might mean:
Sending quarterly market updates that actually explain what’s happening (not just rate sheets). Checking in when you see news that affects their specific situation. Offering annual mortgage reviews that look at their whole financial picture, not just whether they should refi. Building a referral network of real estate agents, financial planners, and insurance professionals who can serve your shared clients. Creating content that educates and entertains, keeping you top-of-mind without being salesy.
The AI revolution that’s coming (already here, really) might actually work in your favor. As Postiglioni points out, AI could help you maintain meaningful contact with a large book of former customers without requiring massive servicing infrastructure. Imagine having tools that alert you when a past client’s home value hits a threshold that makes a cash-out refi attractive, or when their loan seasoning makes them eligible for better terms, or when their ZIP code’s market conditions suggest it’s time for a conversation.
You’re not trying to replace the human relationship—you’re augmenting your capacity to maintain it at scale.
Your New Competitive Advantage
Here’s the beautiful irony: while the big players are dumping billions into owning every piece of the flywheel, you have the agility to invest in something they can’t easily replicate—genuine, personalized relationships at scale.
Rocket Mortgage recently sold $53 billion in MSRs while retaining subservicing and recapture rights on nearly 80% of them. They got paid for the asset without walking away from customer contact. Smart move for them. But notice what they’re really saying: the asset and the relationship are separate things.
You can learn from this. Focus your energy on the relationship, not the asset you don’t own anyway. Build a personal brand that makes you the obvious call when anyone in your sphere needs mortgage advice. Create systems that keep you relevant in your clients’ lives beyond the transaction.
The question isn’t “How do I own the whole flywheel?” It’s “How do I create recurring value that makes me indispensable regardless of who owns the servicing?”
Stop chasing the flywheel. Start building something better: a reputation, a relationship network, and a client experience so valuable that you don’t need to own the servicing to own the next transaction. That’s not a flywheel—that’s a rocket ship.